
Should Holiday Delivery Push Require Action From Kohl's (KSS) Investors?
- Kohl's rolled out its The North Kohl's holiday campaign in October 2026, adding curated gift hubs, refreshed assortments, clearer price tiers, and expanded same day delivery and flexible payment options for budget conscious families.
- The push concentrates spend on higher margin owned brands, Sephora at Kohl's, and expanded toy and home assortments to support traffic and basket size during the peak gifting season.
- We will look at how Kohl's investment narrative is shaped by this holiday push, particularly the broader same day delivery rollout.
Scan how Kohl's holiday push compares to other retailers leaning into value, same day fulfilment, and resilient balance sheets by zeroing in on our hand picked list of solid balance sheet and fundamentals (24 results) as a starting universe.
Kohl's Investment Narrative Recap
To own Kohl's, you need to believe the value repositioning and owned brand focus can offset soft store traffic and cautious low to middle income shoppers. The North Kohl's holiday push leans into that belief by concentrating attention on clearer price tiers and high margin categories during the most important seasonal window.
The key near term catalyst remains whether comparable sales and traffic stabilize through this holiday period. Same day delivery and flexible payments could support that, although higher fulfillment and marketing spend risk weighing on profits if demand or Sephora at Kohl's momentum underwhelms.
The nationwide expansion of same day delivery through DoorDash, Instacart and upcoming Uber Eats may be the most operationally important piece of this holiday update. It builds on existing omnichannel use, such as Store Pickup driving over 20% of digital demand, and gives Kohl's another way to meet shoppers who are already buying online.
For you as an investor, the question is whether these new delivery and checkout options lift digital orders enough to offset weaker in store trends without pushing fulfillment and technology costs too high. If Kohl's can hold gross margins while absorbing these investments, the omnichannel build out can remain a support for earnings rather than a drag.
Kohl's narrative projects US$15.5b revenue and US$240.9m earnings by 2029. This assumes revenue stays broadly flat over the next few years and earnings decline by about US$29.1m from US$270.0m today.
Uncover why Kohl's fair value indicates a 21% potential downside to its current price, which leaves little room for error.
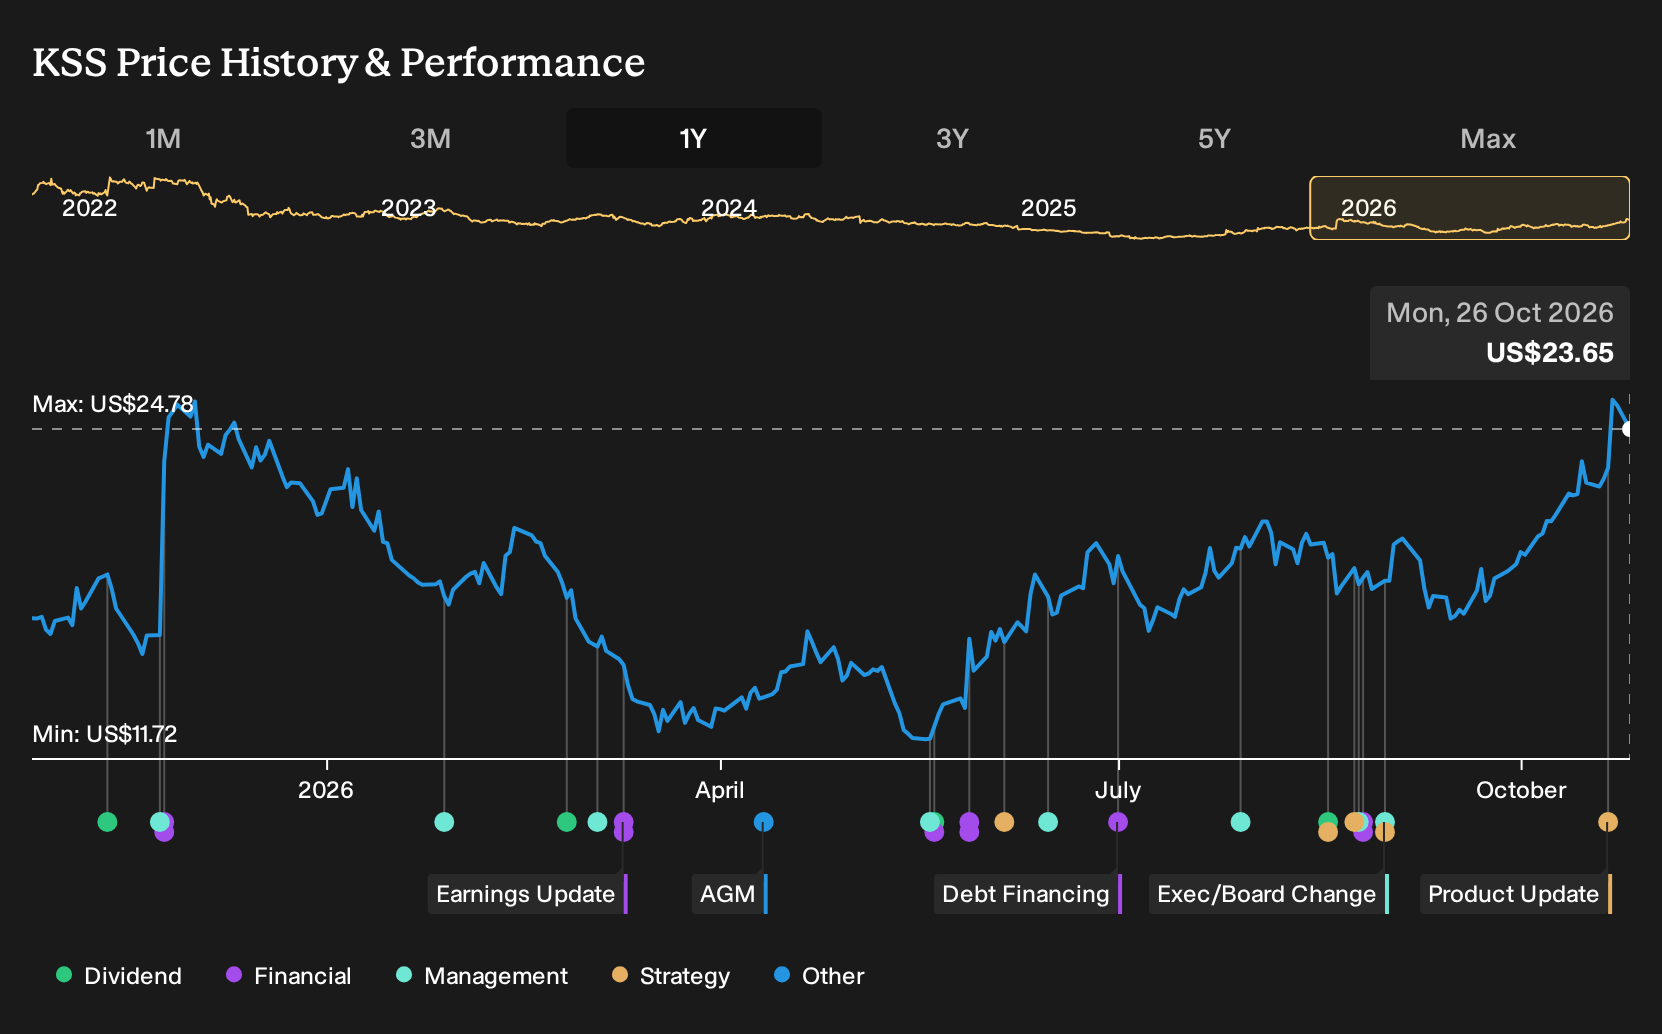
Exploring Other Perspectives
Some of the most optimistic analysts treat Kohl’s marketplace and shop in shops as the real catalyst, not holiday campaigns. Before this news, that group was modeling roughly US$15.7b in revenue and about US$204.7m in earnings by 2029, tied to a higher P/E of 28.3x. Use those stronger assumptions as a contrast and explore how views might shift after The North Kohl’s rollout.
Explore 3 other Kohl's fair value estimates, including one that suggests potential upside of as much as 125% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment results rarely come from following the herd, so consider forming your own view.
- A great starting point for your Kohl's research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Kohl's. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kohl's overall financial health at a glance.
Looking For More Investment Ideas Beyond Kohl's?
If the Kohl's story leaves you wanting a broader watchlist, use this holiday update as a springboard into other opportunities with stronger balance sheets, different risk profiles, or higher income potential.
- If capital protection is a priority, start with companies that pair resilience with lower risk scores through the 30 resilient stocks with low risk scores.
- Income focused investors can scan for businesses offering higher yields by checking out the 5 dividend fortresses.
- For those hunting for under followed quality, widen the search with our 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com