
Altarea (ENXTPA:ALTA) Reaffirms 2026 Dividend as Investors Ask if Shares Look Fully Valued
Altarea (ENXTPA:ALTA) confirmed it plans to pay a stable dividend of €8.00 per share for fiscal 2026, with part of that payout available in stock rather than cash.
Altarea’s confirmation of the 2026 dividend arrives after a tough stretch for the share price, which is down 32.29% on a year to date basis and has fallen 24.85% over the past three months, even though the three year total shareholder return is still up 35.15%. Recent setbacks include a 10.76% decline in the 30 day share price return. Shorter term trading has turned slightly more positive in the last session as the stock closed at €73.8, suggesting the dividend clarity may be helping to steady sentiment even as longer term momentum has faded.
Compare Altarea’s dividend clarity with other income ideas by scanning a hand picked set of 224 dividend fortresses that prioritize reliability alongside yield.
That kind of price slide, alongside a reaffirmed €8.00 payout, puts Altarea at an interesting crossroads. Is the recent weakness pointing to cracks in the business, or just a reset in sentiment that leaves the valuation out of sync?
Preferred P/E of 48.1x: Is it justified for Altarea?
Altarea closed at €73.8 while trading on a P/E of 48.1x, and that valuation sits well above both its peers and an estimated fair level for its earnings power.
The P/E ratio compares the current share price to earnings per share and gives you a quick sense of how much investors pay for each euro of profit. For a real estate group like Altarea, a high P/E often implies the market is baking in strong, sustained profitability or very low perceived risk around its earnings profile.
For this stock, the signals point in a different direction. The business has only recently turned profitable and its Return on Equity sits at a low 3.6%, while the Fair P/E ratio is estimated at 19.2x. That gap suggests investors are currently paying a much richer price than the earnings record and quality would usually support, even though earnings are expected to grow significantly over the next few years.
The contrast with peers is sharp. Altarea’s P/E of 48.1x is more than double the peer average of 23.3x and far above the European Residential REITs industry average of 9.7x. This indicates the market is attaching a much higher price tag to each euro of its profit than to comparable groups.
Explore the SWS fair ratio for Altarea.
Result: Price-to-earnings of 48.1x (OVERVALUED)
Still, Altarea’s thin €35.8 million net income on €1,928.4 million of revenue, along with a value score of 0, leaves little room for earnings disappointments.
Find out about the key risks to this Altarea narrative.
Another view on Altarea’s value using our DCF model
The P/E ratio paints Altarea as expensive, yet the SWS DCF model points in a softer direction. On that framework, the estimated value of future cash flows sits at €67.71 per share, which leaves the current €73.8 price trading above that number. So is the share price already running ahead of its cash flow story?
Look into how the SWS DCF model arrives at its fair value.
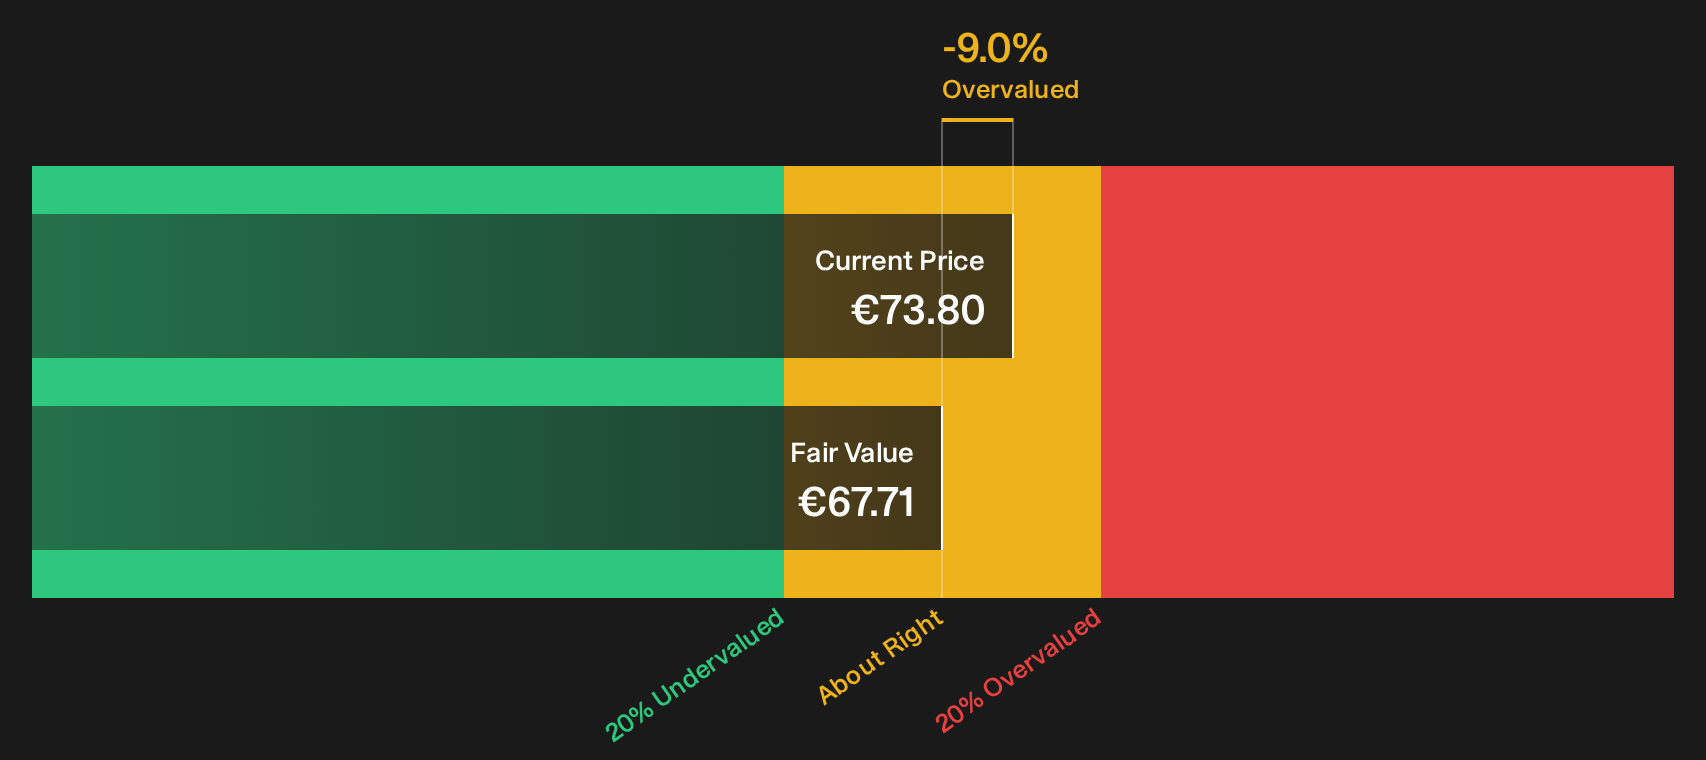
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Altarea for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Altarea’s valuation and dividend can pull you in both directions, so act early, review the figures yourself and consider both risks and potential upsides through the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Altarea?
Do not stop with one stock. Broaden your watchlist using focused screeners that surface different types of opportunities and help you pressure test your thinking across the market.
- Target potential mispricing by scanning a curated set of companies that screen as 195 high quality undervalued stocks and compare how their valuations stack up against their fundamentals.
- Strengthen portfolio resilience by reviewing a list of solid balance sheet and fundamentals (207 results) and focus on businesses with sturdier financial footing.
- Hunt for underfollowed opportunities by checking a 610 high quality undiscovered gems that highlights quality stocks flying under most investors’ radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com