
Is Centerra Gold (TSX:CG) A Bargain After Its Québec Option Deal?
Centerra Gold (TSX:CG) has moved back into focus after signing an option agreement with Azimut Exploration that gives it a path to a majority stake in Québec’s Corvet and Kaanaayaa gold copper properties.
For context, Centerra Gold’s share price has pulled back over the past week and month, with 7 day and 30 day share price returns of 7.66% and 10.47% respectively. However, the 90 day share price return of 25.77% and year to date gain of 47.01% suggest momentum over the longer stretch is still positive, supported by a 1 year total shareholder return of 90.76% and a 5 year total shareholder return of 247.57% that point to meaningful compounding for investors who have stayed in the stock.
Scan how Centerra Gold compares to other producers gearing up around precious metals momentum by reviewing the hand picked 35 elite gold producer stocks in this corner of the market.
Centerra Gold’s recent pullback sits against very strong multi year returns and fresh exploration commitments in Québec. Are you looking at a brief sentiment reset, or a price that already reflects that progress?
Most Popular Narrative: 15% Undervalued
Measured against the latest fair value estimate of CA$33.61 and a last close of CA$28.55, the most followed narrative sees Centerra Gold as underpriced while still incorporating falling revenue and earnings forecasts that keep expectations restrained.
The analysts have a consensus price target of CA$33.61 for Centerra Gold based on their expectations of its future earnings growth, profit margins and other risk factors.
Given the current share price of CA$28.32, the analyst price target of CA$33.61 is 15.7% higher. Despite analysts expecting the underlying business to decline, they seem to believe it is more valuable than what the market thinks.
See why 19 investors see Centerra Gold as 15% undervalued.
Result: Fair Value of CA$33.61 (UNDERVALUED)
Still, if Centerra Gold misses already reduced revenue and earnings forecasts, or if margins tighten faster than analysts model, that 15% discount argument weakens quickly.
Find out about the key risks to this Centerra Gold narrative.
Another View: DCF Flags an Overhang
The fair value story around Centerra Gold looks very different when switching from analyst targets to the SWS DCF model. On that cash flow lens, the estimate sits at CA$10.11 per share, well below the current CA$28.55 price. This implies the stock screens as expensive rather than discounted. Which version of “value” feels more realistic to you?
To see exactly how those future cash flows are treated and where the gap comes from, take a closer look at the Look into how the SWS DCF model arrives at its fair value..
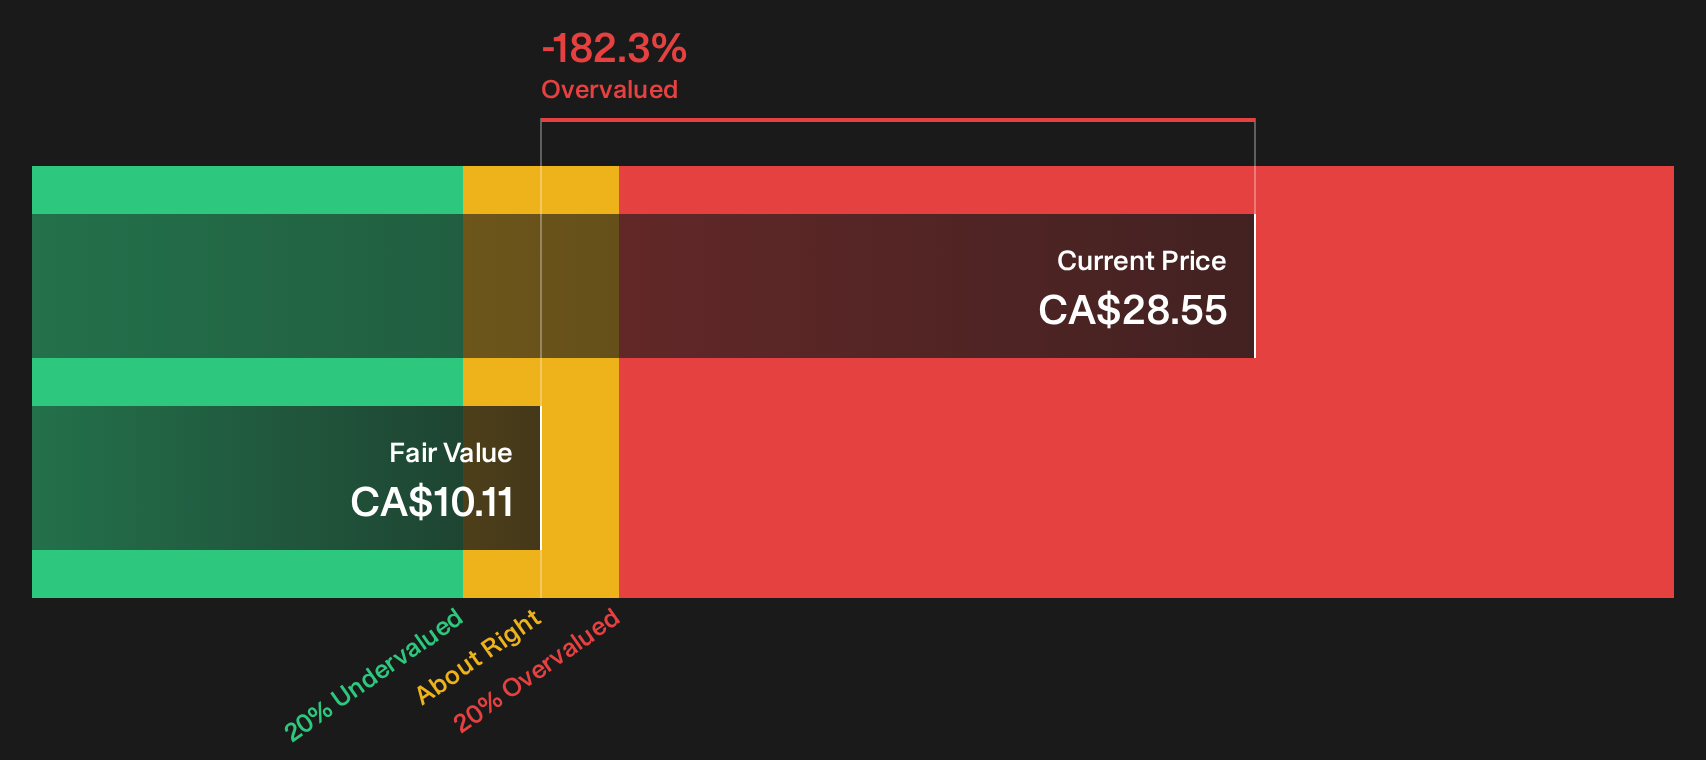
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Centerra Gold for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 3 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Centerra Gold can create a lot of noise, so move quickly, review the core data for yourself, and weigh both sides of the story by checking the 3 key rewards and 2 important warning signs
Looking for more Centerra Gold sized ideas?
If Centerra Gold has your attention, do not stop there. Use the Simply Wall St Screener to spot other opportunities before they move without you.
- Target quality at a discount by scanning companies that currently appear mispriced through the 3 high quality undervalued stocks.
- Lock in reliable income streams by focusing on businesses in the 3 dividend fortresses that offer higher yields with supporting fundamentals.
- Prioritise capital preservation and steadier compounding by filtering for the 8 resilient stocks with low risk scores that clear tougher balance sheet and risk checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com