
Sinch (OM:SINCH) Adds RCS To SAP Integration, Is The Valuation Upside Already Priced In?
Sinch (OM:SINCH) just extended its long-running collaboration with SAP by adding Rich Communication Services to the native integration with SAP Engagement Cloud, widening the range of messaging channels available to enterprise customers.
Investors have been rewarding Sinch for this kind of product expansion, with the share price at SEK47.71 and a 90 day share price return of 19.9%, contributing to a 55.5% year to date share price gain and a 42.2% one year total shareholder return.
Scan other communication and AI engagement plays that show similar momentum to Sinch through our curated list of 39 profitable AI stocks that aren't just burning cash.
Some investors see the SAP tie up and Sinch's double digit returns as the start of a re rating. Others think the past five year share price record still argues for caution. Which side do the current valuation signals support?
Most Popular Narrative: 6% Overvalued
Sinch closed at SEK47.71 against a most-followed fair value estimate of SEK44.83. This puts the current quote modestly above that narrative benchmark and raises the question of whether enthusiasm has run ahead of execution.
Sinch's rapid integration of AI and machine learning capabilities across its communications platform, including AI-enabled products, conversational solutions, and partnerships with platforms like Salesforce and Microsoft, is positioned to unlock new product revenue streams and boost customer engagement, likely accelerating revenue and supporting long-term growth.
See why 15 investors see Sinch as 6% overvalued.
Result: Fair Value of SEK44.83 (OVERVALUED)
Still, Sinch faces pressure if organic net sales stay around 2% and if RCS traffic continues to displace SMS instead of adding fresh revenue.
Find out about the key risks to this Sinch narrative.
Another View: Sinch Through A Cash Flow Lens
The earlier narrative leans on earnings multiples, where Sinch screens as expensive with a P/E of 74.7x against a 40.9x fair ratio and lower peer averages. A very different picture comes from our DCF model, which points to a fair value of SEK67.61 and suggests the current SEK47.71 level trades at a discount. Which yardstick do you trust more when the signals clash?
Our DCF model points to one outcome, while the earnings multiple work tells a different story. Look into how the SWS DCF model arrives at its fair value.
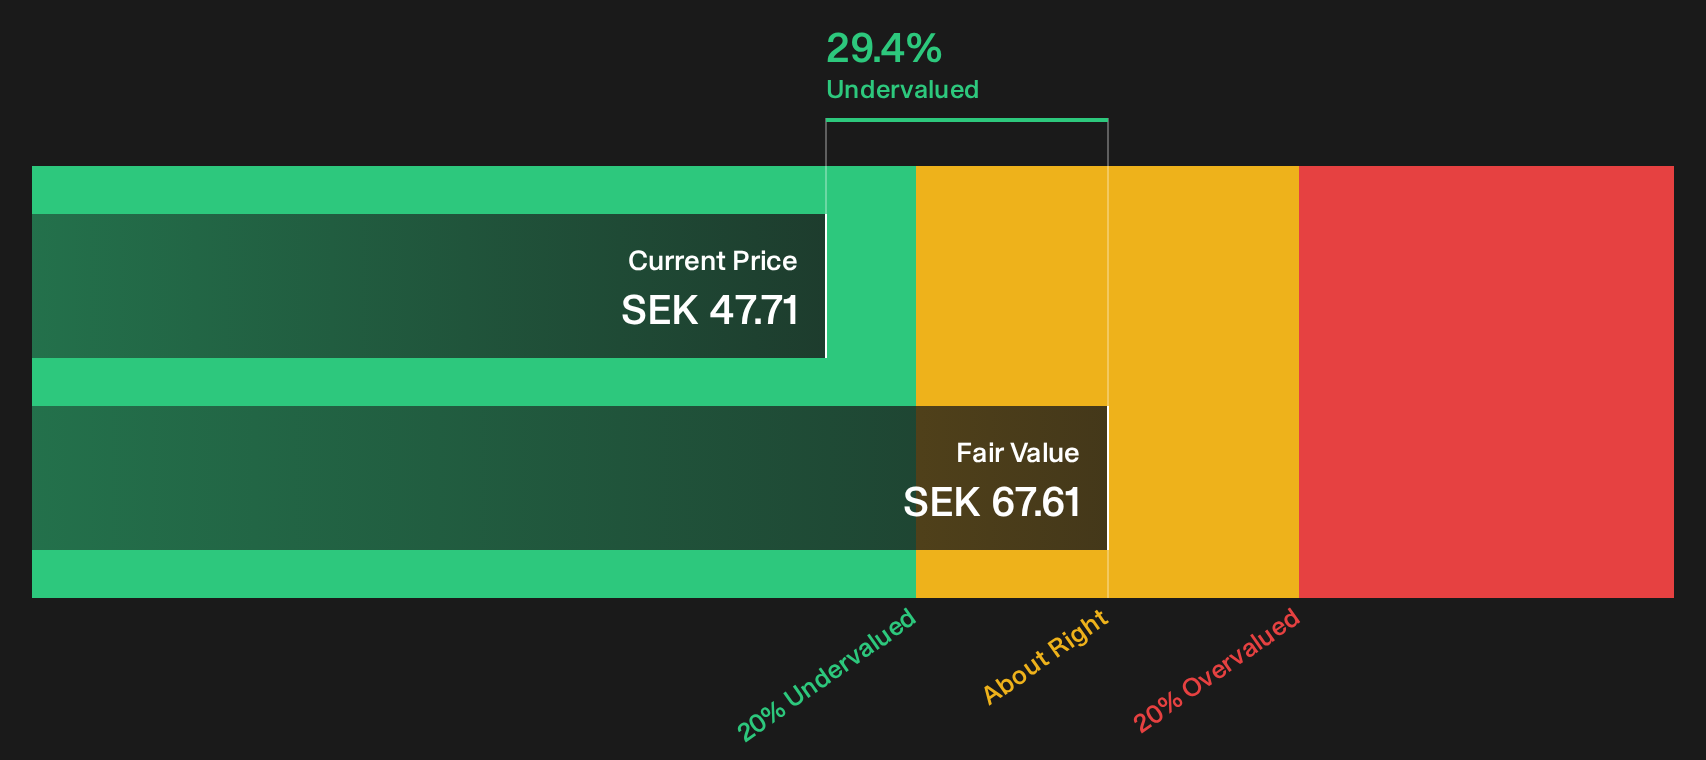
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sinch for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Sinch so far, with strong recent returns on one side and valuation friction plus flagged issues on the other. If you want to move fast and build your own view from the ground up, start by weighing the balance of 3 key rewards and 1 important warning sign.
Looking for more ideas beyond Sinch?
If Sinch has sharpened your appetite for opportunity, do not stop here. Broaden your watchlist with other angles that could suit your approach and risk profile.
- Target resilient businesses that combine quality with a margin of safety by scanning our curated 195 high quality undervalued stocks.
- Lock in potential income streams by reviewing companies that feature in the 224 dividend fortresses.
- Reduce downside surprises by focusing on financially robust candidates surfaced in the list of solid balance sheet and fundamentals (207 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com