
Is Mitsubishi (TSE:8058) Undervalued As Copper World Raises Its Long Term Resource Bet?
Mitsubishi (TSE:8058) is back in focus after approving the final investment decision with Hudbay Minerals to build the Copper World project in the U.S., a long-life copper mine targeting first output in 2029.
The Copper World decision comes after a strong run for Mitsubishi, with the share price at ¥4,910 and a year to date share price return of 34.41% alongside a 1 year total shareholder return of 33.14% and a very large 5 year total shareholder return that is close to 4x. Recent momentum looks positive, with the 1 day share price return of 4.14% and 7 day share price return of 3.13%. This suggests investors are reacting to fresh growth optionality and reassessing the risk profile around long term resource exposure.
Spot opportunities that rhyme with Mitsubishi’s long-life resource push by scanning our hand picked list of 16 top copper producer stocks.Bulls see Mitsubishi using Copper World to extend already strong returns, while bears worry about capital risk and long project lead times. Which case does the current valuation actually lean toward as the stock pushes higher?
Most Popular Narrative: 7% Undervalued
Mitsubishi’s most followed narrative places fair value around ¥5,265, which sits above the latest ¥4,910 close and frames the recent Copper World move against a modest discount.
Active capital recycling and selective divestitures of lower-margin businesses align the portfolio toward higher-margin and recurring revenue streams, which may enhance net margins and improve return on equity over the medium term. Comprehensive digital transformation efforts across business lines are expected to streamline operations and facilitate the creation of new data-driven business opportunities, supporting cost efficiencies and margin improvement.
See why 36 investors see Mitsubishi as 7% undervalued.
Result: Fair Value of ¥5,265 (UNDERVALUED)
Still, the Copper World upside can quickly fade if commodity prices stay weak or large resource projects tie up capital without delivering the cash flow investors expect.
Find out about the key risks to this Mitsubishi narrative.
Another View: Mitsubishi Looks Expensive On Cash Flows
The popular story around Mitsubishi focuses on a fair value of about ¥5,265 and a 7% discount. A different lens tells a tougher story. The SWS DCF model estimates future cash flows at roughly ¥2,732 per share, well below the current ¥4,910 price, which points to the stock trading on the expensive side. So which signal should carry more weight in your own work on Mitsubishi?
Look into how the SWS DCF model arrives at its fair value.
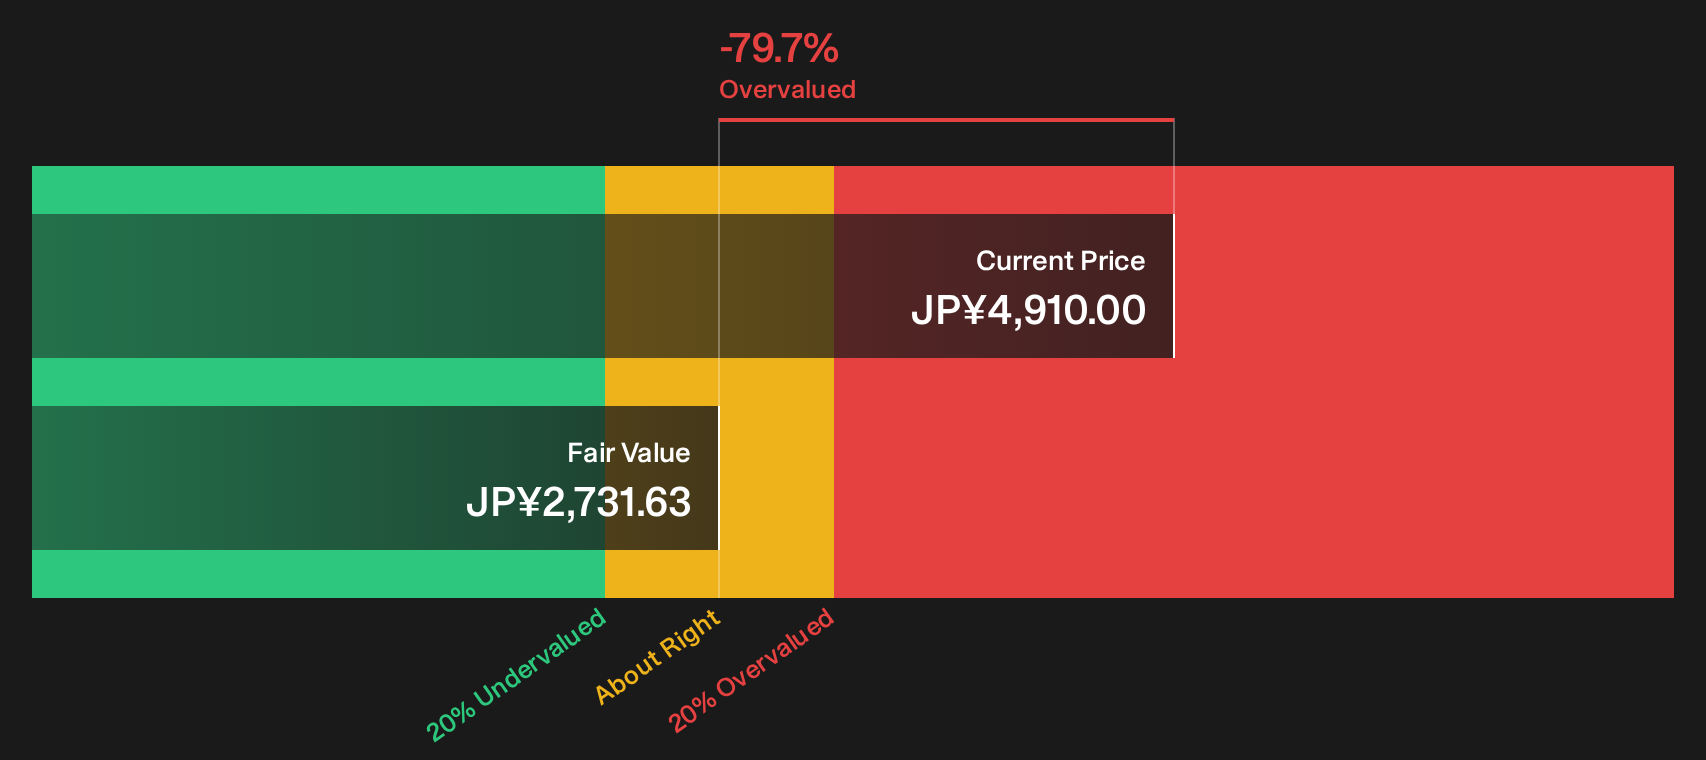
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mitsubishi for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 16 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on value can feel uncomfortable, yet waiting for total clarity often means reacting late. To evaluate Mitsubishi, consider both potential benefits and risks by reviewing the 2 key rewards and 1 important warning sign.
Looking for more Mitsubishi investment ideas?
If Mitsubishi has you thinking harder about where to put fresh capital, do not stop here. Broader opportunity often hides in plain sight on a good screener.
- Target resilient cash generators by scanning a list of solid balance sheet and fundamentals (23 results) that can better handle rough patches and still support long term compounding.
- Hunt for mispriced quality using a 16 high quality undervalued stocks that filters for strong fundamentals trading at what could be attractive entry points.
- Prioritise sleep at night potential with a 22 resilient stocks with low risk scores that focuses on steadier businesses where balance sheets and risk scores do more of the heavy lifting.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com