
Has Space Exploration Technologies (SPCX) Become Cheap As Its $3.42b Shelf Registration Reshapes Valuation?
Space Exploration Technologies (SPCX) has put a fresh funding option on the table, filing a US$3.42b shelf registration for 23.6 million Class A shares. That move immediately raises questions about valuation, dilution, and growth funding.
Investors have already been dealing with a choppy ride in Space Exploration Technologies this year, with the share price return down 8.73% year to date, even after a 26.19% share price return over the past 90 days. This hints at improving momentum despite recent daily softness around the US$146.9 level.
Capitalize on the funding and merger buzz around Space Exploration Technologies by scanning a curated set of 55 AI infrastructure stocks that could also be gearing up for their next big move.Space Exploration Technologies now trades at a hefty discount to both analyst targets and some intrinsic value models after its shelf filing and GPU financing spree. Is the market sensibly discounting risk, or mispricing a rewired business?
Most Popular Narrative: 31,835% Overvalued
The most followed valuation story around Space Exploration Technologies points to a huge gap between its last close at $146.90 and a narrative fair value of $0.46, framing the current shelf registration against a much lower long term payoff.
SpaceX is one of the most important engineering companies in the world, but from a valuation standpoint, it still behaves like a capital‑intensive industrial business with modest margins and high execution risk. With a 30% discount rate to reflect the lack of current profitability, the fair value estimate lands at US$0.87 per share in 2026.
See why 89 investors see Space Exploration Technologies as 31835% overvalued.
Result: Fair Value of $0.46 (OVERVALUED)
Still, if Space Exploration Technologies turns its US$32,043.0m revenue base into sustained profitability, or if the AI segment starts contributing meaningfully, this bearish narrative could unravel fast.
Find out about the key risks to this Space Exploration Technologies narrative.
Another View On Space Exploration Technologies: Cash Flows Tell A Very Different Story
The bearish narrative around Space Exploration Technologies pegs fair value at just $0.46, yet our DCF model that projects future cash flows implies a value of $420.37 per share, leaving SPCX trading at a 65.1% discount. Are investors overpaying for hype, or underestimating future earnings power?
Look into how the SWS DCF model arrives at its fair value.
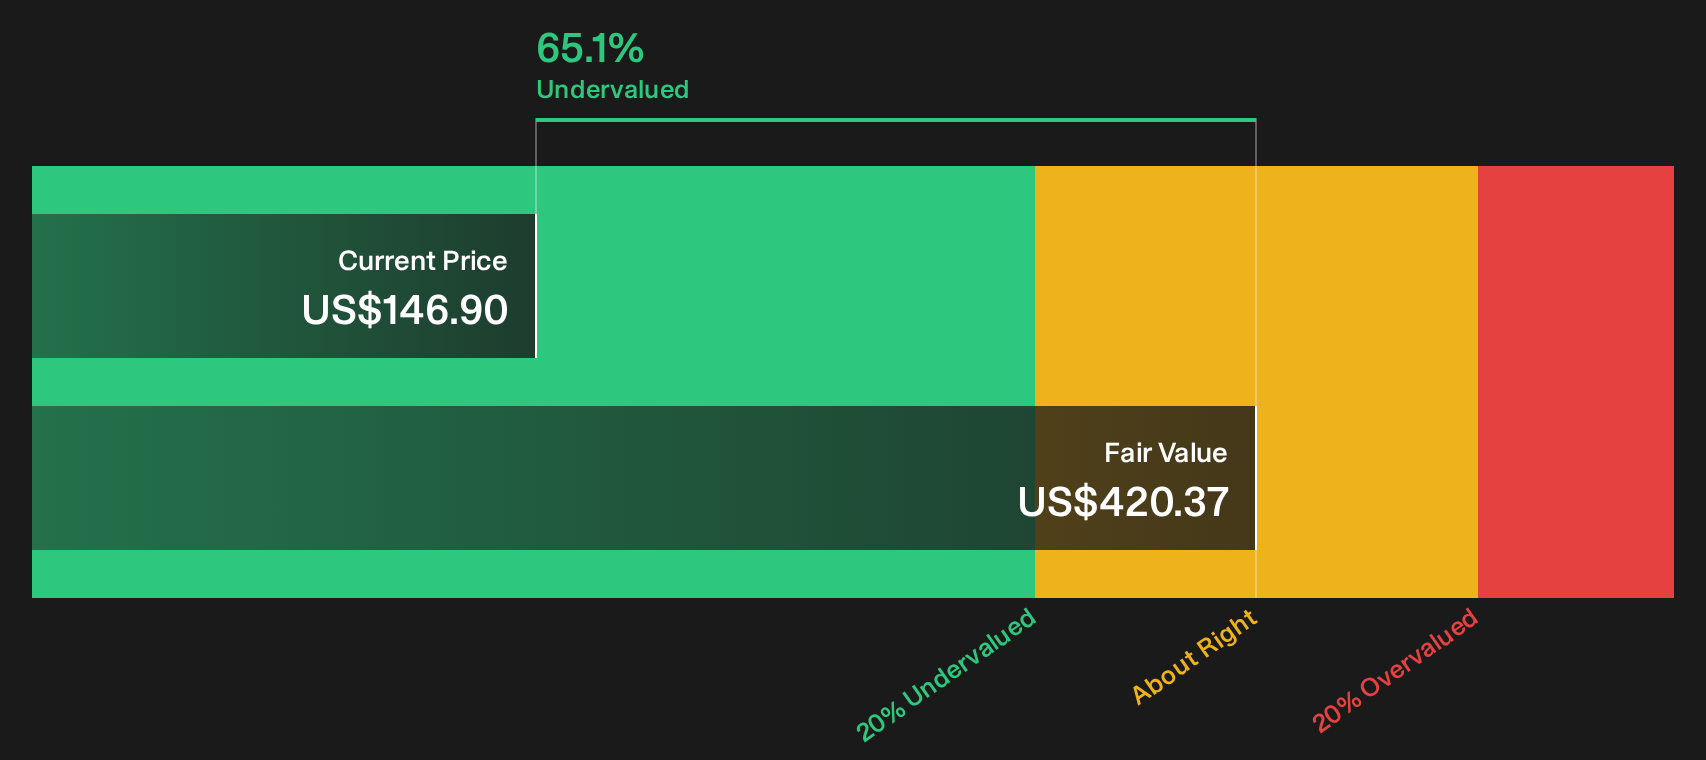
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Space Exploration Technologies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Space Exploration Technologies can easily sway sentiment, so move quickly, examine the underlying data, and weigh both the upside and the risks in context with 3 key rewards and 2 important warning signs.
Looking for more Space Exploration Technologies investment ideas?
You have seen how complex Space Exploration Technologies can be. Do not stop here; widen your opportunity set with a focused search for other potential winners.
- Target resilient compounding potential by reviewing 29 high quality undervalued stocks, which pairs stronger balance sheets with pricing that still leaves room for a margin of safety.
- Protect your downside first and let upside surprise you by scanning 30 resilient stocks with low risk scores, built around sturdier fundamentals and calmer price swings.
- Spot tomorrow’s leaders before the crowd by running through 21 high quality undiscovered gems, where solid financials meet relatively low attention from the broader market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com