
Guidewire Software (GWRE) Beat Expectations, Is It Still 14% Undervalued?
Guidewire Software earnings jolt puts recent share moves in focus
Guidewire Software (GWRE) just posted quarterly revenue of US$411.1 million, up 15.3% year on year, with billings and adjusted operating income both ahead of analyst expectations, yet the stock has fallen 6.5% since the release.
Recent trading in Guidewire Software has been choppy. The stock has climbed strongly in the short term, with a 26.4% 30 day share price return and 15.4% over 90 days. However, the latest post earnings drop comes against a 1 year total shareholder return that has fallen 27.3%, even after a 54.1% gain over five years. This points to momentum that has improved lately but from a weaker medium term base, as investors reassess how much of the reported growth is already reflected in the US$183.96 share price.
Compare how Guidewire Software stacks up against other fast growing software platforms by reviewing a curated 21 high quality undiscovered gems that the market may not be fully pricing in yet.
Guidewire Software now trades at a discount to analyst targets even after the post earnings dip, which raises a sharper question: Is the market’s caution sensible, or has it pushed the reset button too far?
Most Popular Narrative: 14% Undervalued
Guided by the most followed narrative on Guidewire Software, the implied fair value of $213.29 sits above the last close at $183.96. This puts the recent selloff into a different light and shifts attention to the durability of its subscription base and product breadth.
Very low gross ARR attrition, including core systems churn below 1%, together with growth in customers above US$5 million of fully ramped ARR, points to a premium linked subscription base that can support more predictable ARR growth and help stabilize earnings over time.
See why 11 investors see Guidewire Software as 14% undervalued.
Result: Fair Value of $213.29 (UNDERVALUED)
Still, the Guidewire Software story can wobble if insurers pull back on IT budgets or if cloud migrations slow, which could pressure ARR and margins.
Find out about the key risks to this Guidewire Software narrative.
Another View: Guidewire Software looks expensive on earnings multiples
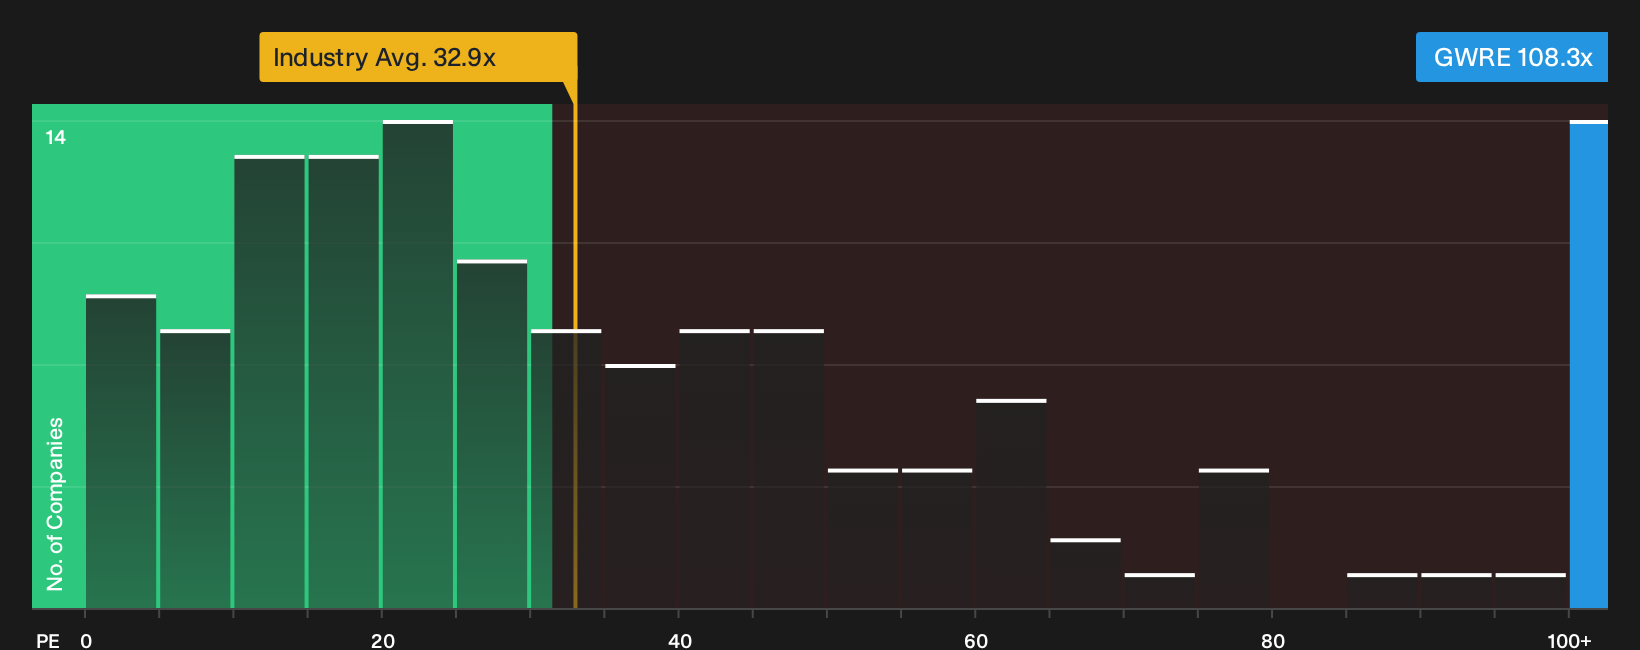
Guidewire Software may look undervalued against the $213.29 fair value from the leading narrative, but its current P/E of 108.3x is far above the US Software industry at 32.9x and the peer average at 69.9x. It also sits well above a 39.8x fair ratio. That gap suggests meaningful valuation risk if sentiment cools.
Investors comparing these signals can use the earnings multiple work as a cross check on their own assumptions, then decide which story feels more realistic for the next few years. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The mix of enthusiasm and caution around Guidewire Software is clear. Move quickly, review the numbers for yourself, and pressure test both sides of the argument using the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Guidewire Software?
If Guidewire Software has sharpened your thinking, do not stop here. Broaden your watchlist now and give yourself more options before the next move.
- Target resilient upside potential by scanning a carefully filtered group of companies on the 29 high quality undervalued stocks.
- Prioritise capital preservation and steadier price action by focusing on stocks with stronger risk profiles through the 30 resilient stocks with low risk scores.
- Strengthen your shortlist with businesses backed by healthier finances and cleaner balance sheets using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com