
Did Health100 AI Launch Just Shift CVS Health (CVS) Investment Narrative?
- CVS Health recently launched its Health100 AI platform, expanded GLP 1 programs, and reported quarterly results that showed stronger profitability from its integrated healthcare model.
- These moves shift more of CVS Health's business mix toward technology enabled services and higher margin care offerings, reshaping how the group uses its Aetna, Caremark, and retail assets together.
- We will now look at how CVS Health's Health100 AI push could reshape the investment narrative built around its integrated platform.
Scan how CVS Health fits into the wider shift toward tech enabled care by comparing it with list of solid balance sheet and fundamentals (24 results).
CVS Health Investment Narrative Recap
To own CVS Health, you need to believe the integrated platform of Aetna, Caremark and retail can keep turning healthcare demand into steadier earnings, even as medical cost trends remain a swing factor. The key near term catalyst is execution on margin targets in insurance and Health Care Delivery, where elevated medical benefit ratios could still cap progress.
Membership trends and 340B pressures sit on the other side of the ledger. Client exits, tougher renewals or weaker PBM economics could offset pharmacy growth and mute any benefit from AI driven efficiencies. The new midlife collaboration does not materially change these core operational swing factors right now.
The most relevant context around this midlife initiative is CVS Health's broader push into higher margin services and technology, including the Health100 AI platform and expanded GLP 1 programs. These efforts aim to deepen relationships across insurance, PBM and retail. This can matter for future membership stickiness and prescription volumes if the offerings gain traction.
For you as a shareholder, the operational questions stay practical. Can CVS Health scale these health programs and research backed offerings fast enough to matter for segment earnings while managing debt, one off legal costs and PBM headwinds? Execution on disciplined Aetna underwriting and tech driven cost savings remains the clearer near term catalyst to watch.
CVS Health's current analyst narrative points to revenues of US$458.7b and earnings of US$11.3b by 2029, based on an assumed 3.6% yearly revenue growth rate and a move from US$4.9b of earnings today to that 2029 consensus level, which is an increase of about US$6.4b.
Discover why CVS Health's fair value suggests a 26% potential upside to its current price before the market fully reflects that difference.
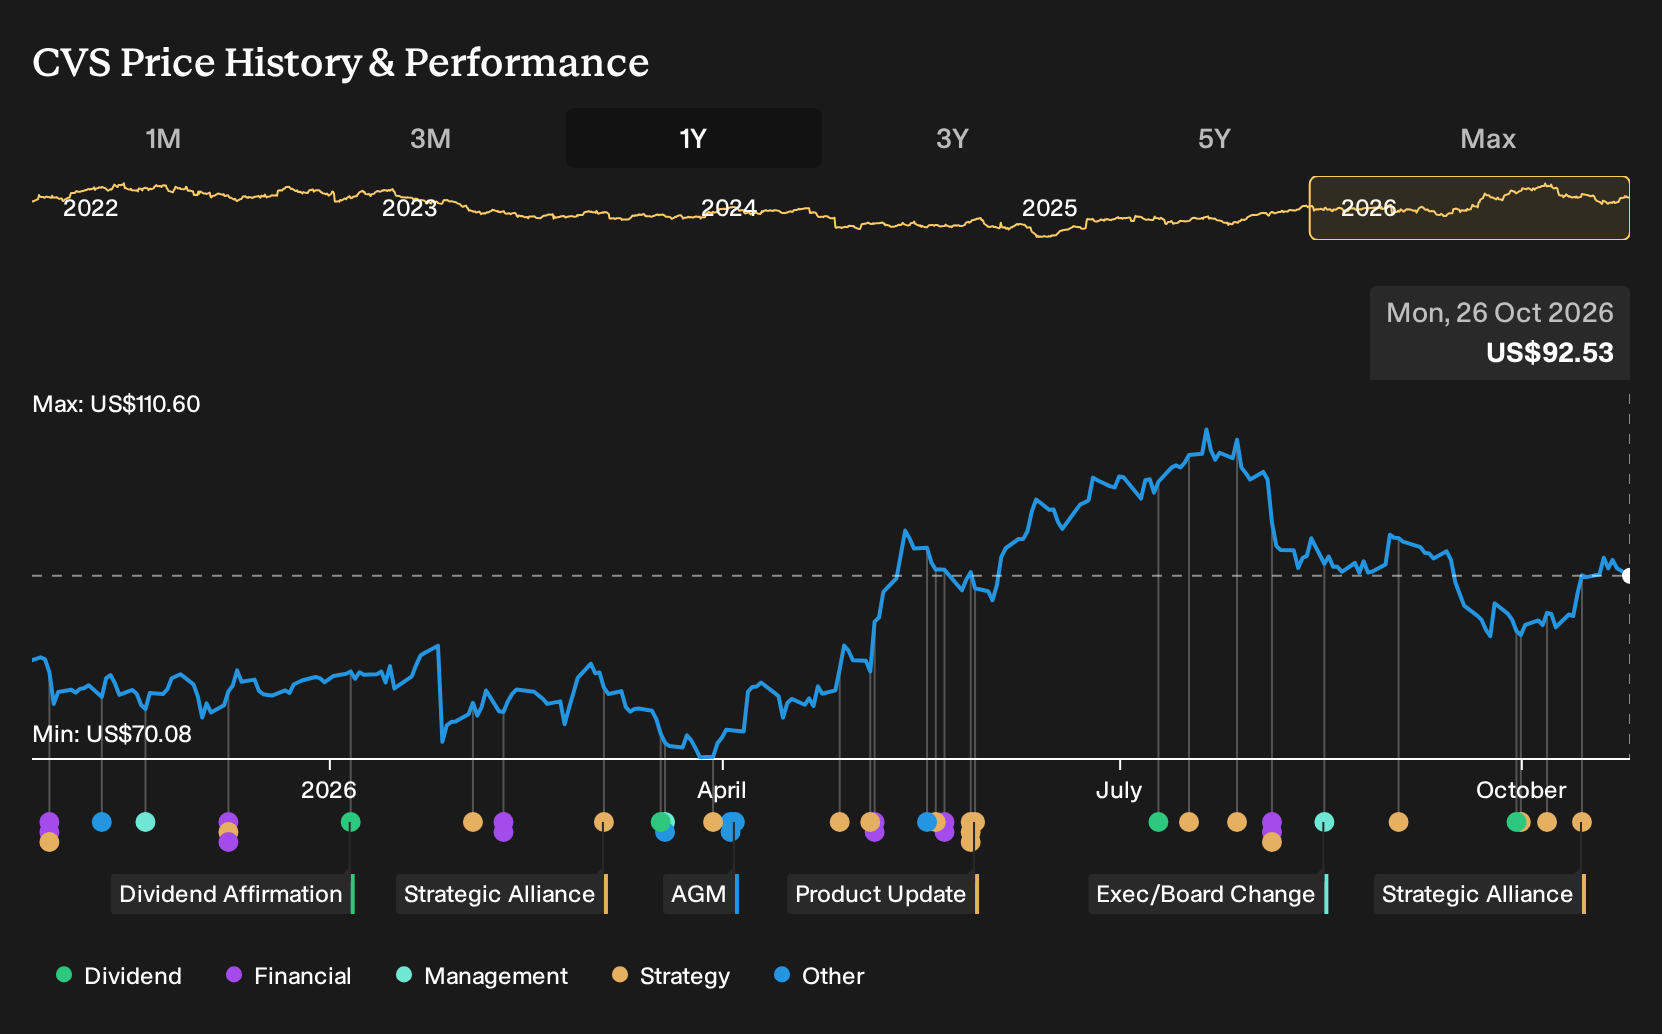
Exploring Other Perspectives
Five fair value estimates from the Simply Wall St Community span roughly US$104 to about US$277 per share, so you are looking at almost a 3x gap between the lowest and highest views. That spread sits against risks around medical benefit ratios and PBM pressure, plus catalysts tied to CVS Health's GLP 1 push and heavy AI investment. Opinions are likely to diverge sharply, so it may be useful to explore several of these viewpoints before deciding how CVS fits your own thesis.
Explore 4 other CVS Health fair value estimates, including one that suggests it could be worth just $104.01.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your CVS Health research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for CVS Health. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CVS Health's overall financial health at a glance.
Looking For More CVS Health Style Ideas?
If the CVS Health story has you thinking about where else integrated care, balance sheet strength and earnings quality might line up, a focused screener can save you hours of manual trawling through filings and charts.
- If resilience matters most to you, start with a shortlist of companies screened for lower risk profiles and steadier fundamentals through the 30 resilient stocks with low risk scores.
- If you want to hunt for potential mispricings with quality in mind, filter the market for financially sound businesses that screen as undervalued using the 21 high quality undiscovered gems.
- If income is a priority, zero in on candidates offering stronger yields and more robust payout histories by scanning the market through the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com