
How Investors Are Reacting To ExxonMobil Stock As Earnings Near
- Persian Gulf exports have already moved above pre conflict levels, while ExxonMobil heads into an earnings week supported by higher Brent crude and strong refining margins.
- Operational efforts to lift recovery in the Permian Basin and potential divestment of the Infineum stake highlight ExxonMobil’s focus on controllable efficiency and structural savings rather than short term pricing.
- We will now look at how ExxonMobil’s investment narrative lines up with this earnings backdrop and the stronger Persian Gulf exports.
Scan how ExxonMobil’s setup compares to other oil and gas players positioned for swings in crude and refining margins by reviewing the hand picked 29 high quality undervalued stocks across the sector.
ExxonMobil Holdings Investment Narrative Recap
To own ExxonMobil Holdings, you need to believe the big earnings drivers are still operational, not just price based. That means high return barrels from Guyana and the Permian, an integrated system that can use strong refining margins, and cost programs that keep structural savings flowing. The near term swing factor is whether this earnings season confirms that recent operational efficiency and production levels remain on track.
The main risk is that oil demand or policy pressure changes faster than ExxonMobil can broaden its lower carbon businesses, which are still early. Persian Gulf exports now running above pre conflict levels point to less supply stress, so the news mostly matters for how it colors oil pricing around the earnings print rather than altering the long term thesis.
The clearest tie in with this backdrop is ExxonMobil’s focus on lifting recovery in the Permian Basin through technology that management describes as largely within its control, independent of crude pricing moves. For you, that links directly to the catalyst that many investors watch most closely: whether the company can keep growing advantaged upstream barrels without ballooning operating costs.
This same lens applies to the potential sale of the 50% Infineum stake. Trimming non core exposure could further simplify the portfolio and reinforce the story around structural savings and cash discipline at a time when the stock already trades close to analyst targets and expectations are high heading into earnings.
ExxonMobil Holdings Earnings Setup Versus Analyst Expectations
ExxonMobil Holdings is being judged this earnings season against a fairly tight analyst script. Forecasts build on modest top line expansion and higher profit margins rather than any dramatic shift in the business mix. That puts even more attention on how well the group converts those high return barrels and refining margins into cash while keeping costs in check.
Analysts currently model revenue growth of 1.5% a year over the next three years, with profit margins moving from 9.1% today to 12.6% by 2029. Forecast earnings sit at US$47.4b by that year, up from US$32.8b now, with a wide spread between the most bullish and most cautious profit estimates. For you, that range of outcomes matters because it shows how sensitive sentiment is to execution in the Permian, Guyana and the broader integrated system.
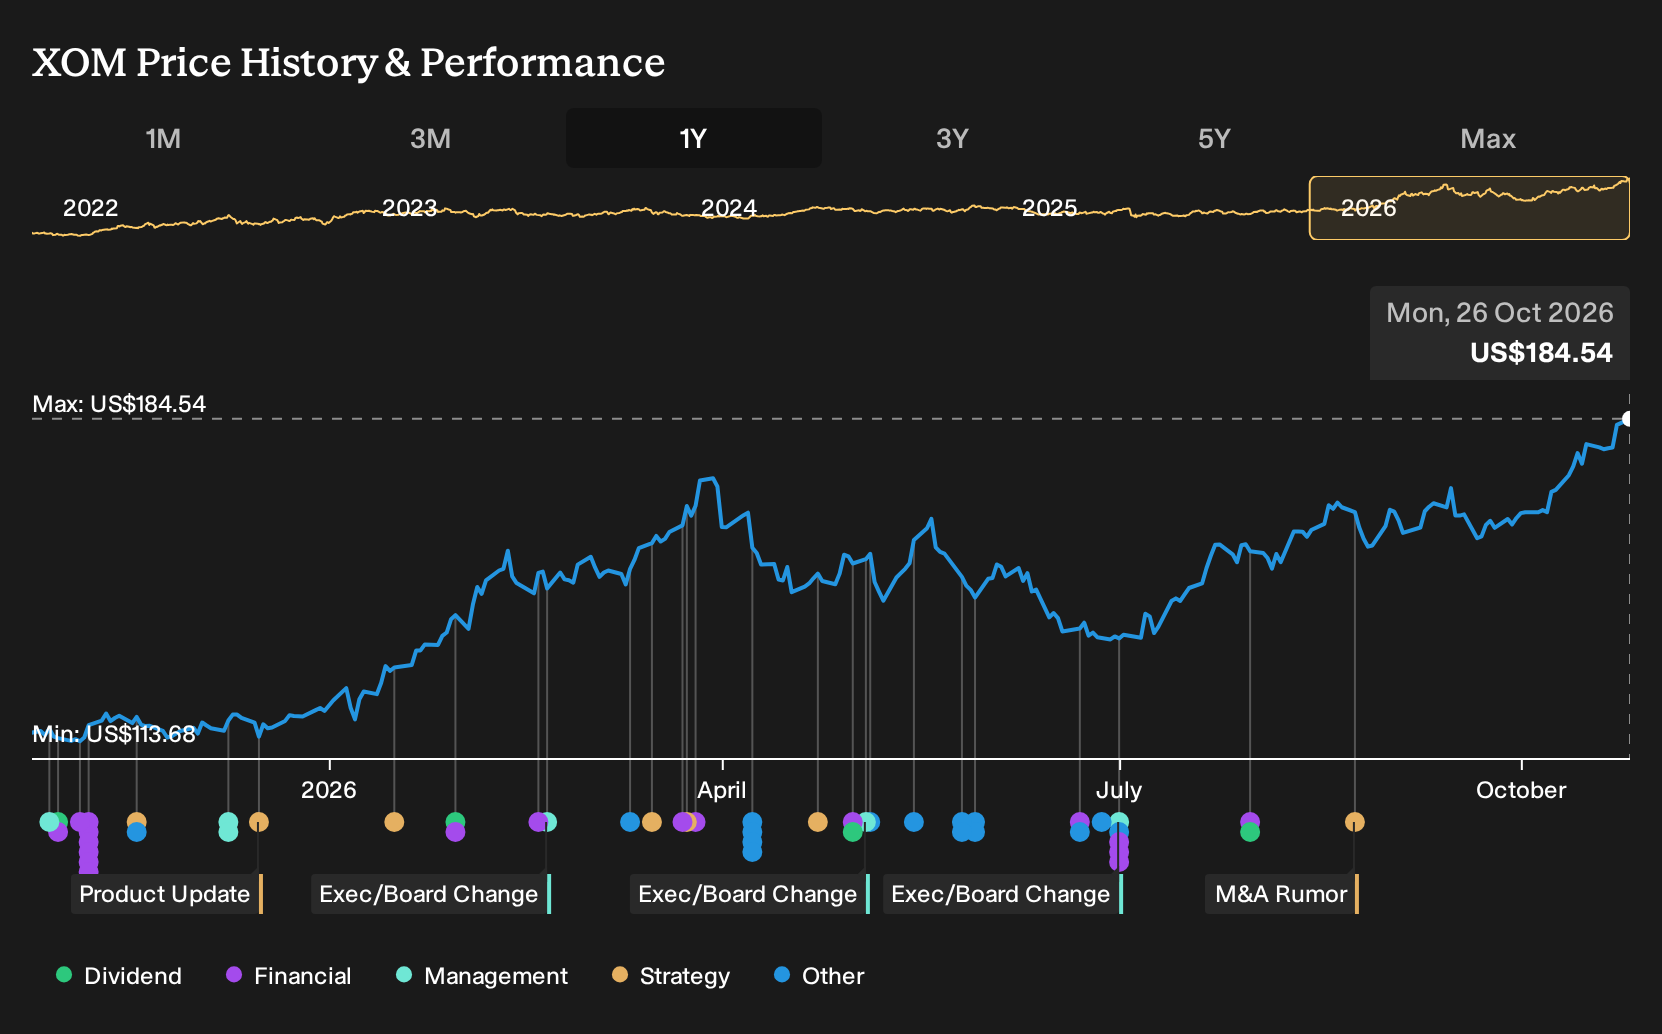
The same assumptions feed straight into how ExxonMobil is valued. Consensus models point to 2029 revenue of US$377.8b and earnings of US$47.4b, with the stock trading on a P/E of 17.4x if those numbers are met, compared with 22.5x today and 12.3x for the wider US oil and gas group. With the current share price at US$178.98 and the average target at US$175.41, analysts on balance see the shares as roughly in line with their fair value work.
ExxonMobil Holdings' narrative projects US$377.8b revenue and US$47.4b earnings by 2029. That implies 1.5% yearly revenue growth and an earnings increase of US$14.6b from US$32.8b today.
Uncover why ExxonMobil Holdings' fair value indicates a 5% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
One alternate take puts ExxonMobil’s Guyana exposure front and center. You saw bullish analysts earlier penciling in US$507.5b of revenue and US$55.6b of earnings by 2029, far above consensus, before Persian Gulf exports eased supply strain. That optimism depends heavily on Guyana risks resolving cleanly, which could shift as this new data feeds into fresh forecasts.
Explore 5 other ExxonMobil Holdings fair value estimates, including one that suggests there may be as much as 15% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your ExxonMobil Holdings research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for ExxonMobil Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ExxonMobil Holdings' overall financial health at a glance.
Looking For More ExxonMobil Holdings Style Ideas?
If the ExxonMobil Holdings story has sharpened your thinking and you want to keep building a watchlist with similar depth, the Simply Wall St Screener can help you scan the wider market for opportunities that line up with your own risk and return preferences.
- For investors who want potential value with quality fundamentals, start with a curated set of companies that screen as 29 high quality undervalued stocks based on earnings strength and balance sheet support.
- If resilience matters more than excitement, focus on a 30 resilient stocks with low risk scores that highlights businesses with sturdier financial profiles and lower risk scores.
- When you want to cast a wider net for less crowded opportunities, broaden your research with a 21 high quality undiscovered gems that filters for strong fundamentals in companies that are still off most radars.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com