
Will Flat Revenue Outlook Change FirstService Stock Narrative
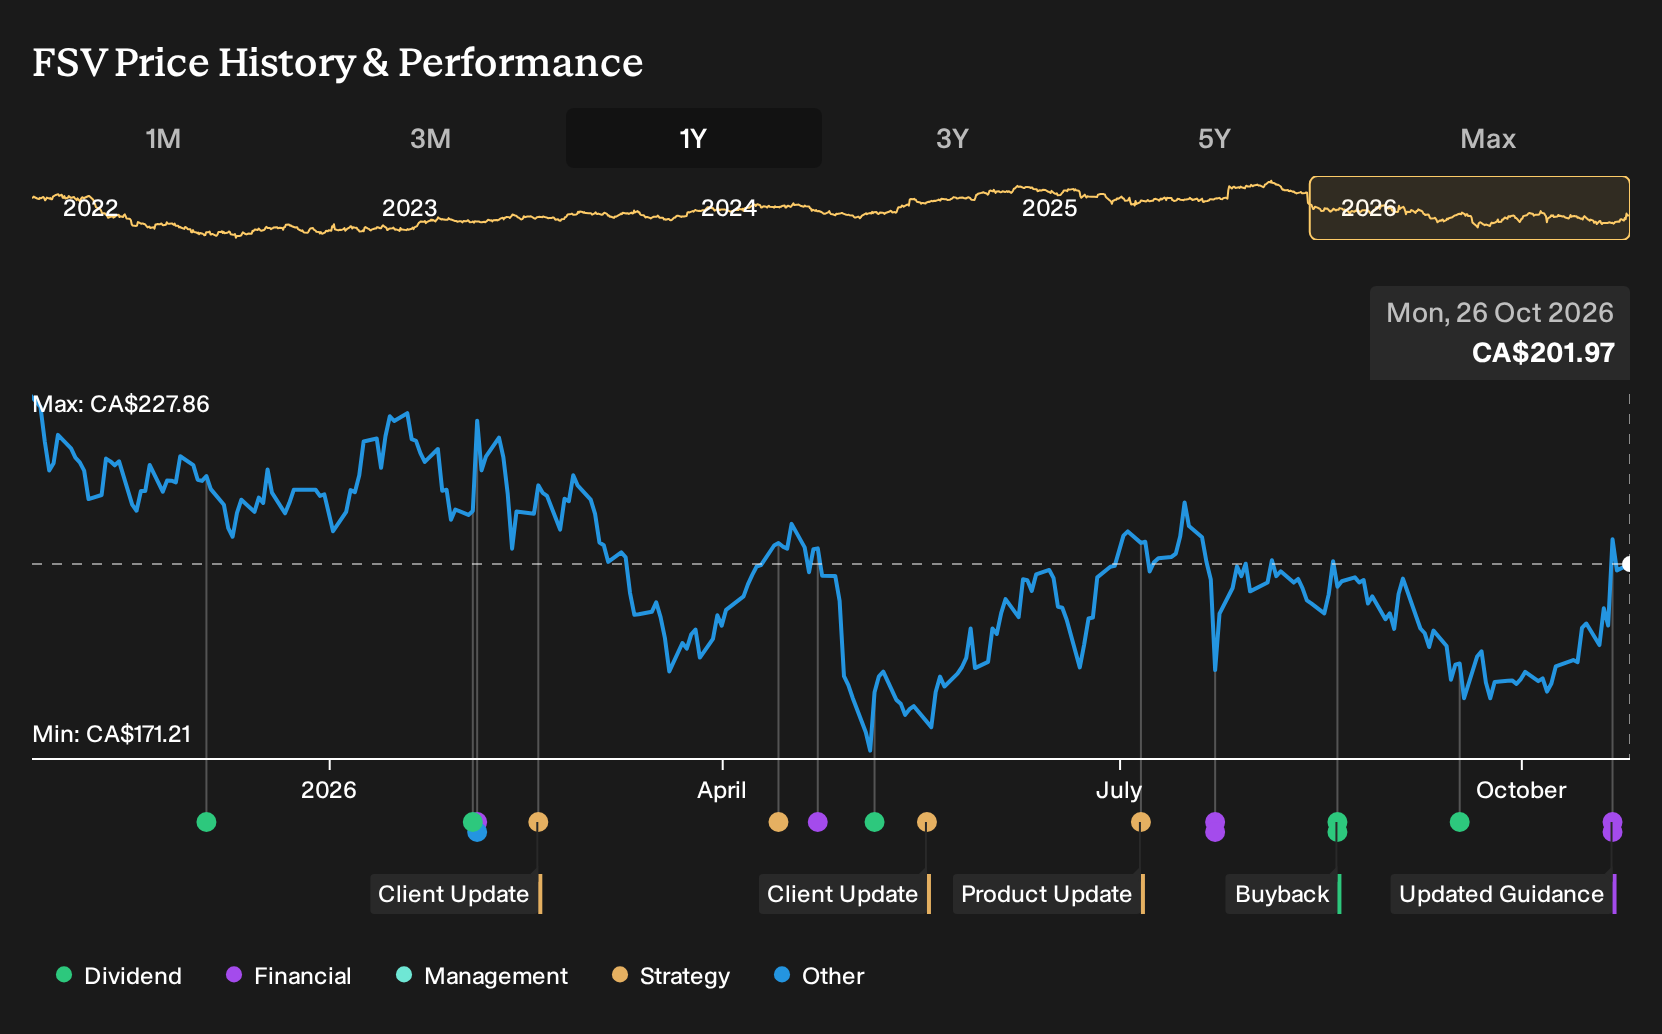
- FirstService reported third quarter 2026 results with sales of US$1,531.7 million versus US$1,447.57 million a year earlier, while net income was US$42.91 million compared with US$57.17 million, and it guided fourth quarter revenue to be flat overall with a low single digit organic decline.
- The mix of higher sales, lower quarterly earnings and guidance for flat near term revenue puts the focus squarely on how efficiently FirstService converts its large property services footprint into consistent profitability.
- We will now look at how FirstService's lower quarterly earnings and flat revenue guidance could reshape its broader investment narrative.
FirstService Investment Narrative Recap
To own FirstService, you need to believe this is a durable essential services platform that can turn a wide property footprint into steadily compounding earnings. The latest quarter showed higher sales but softer profit and a guide for flat near term revenue, which keeps attention on execution rather than growth stories.
The key short term swing factor is how efficiently restoration projects, Residential contracts and Century Fire work flow through the cost base while Roofing and Home Services stay under pressure. The main risk remains a sluggish housing and construction backdrop that keeps organic demand muted. The new guidance does not fundamentally change that setup.
The most relevant update right now is the fourth quarter 2026 outlook. Management expects total revenue to be flat and organic revenue to decline low single digit, which aligns with earlier commentary about soft Roofing activity and cautious spending on larger projects.
For investors, that guidance frames the near term catalyst clearly. Progress on converting large loss restoration jobs, integrating Century Fire tuck ins and holding margins in Residential can still support earnings quality. However, a weaker macro backdrop or further pressure in Roofing would keep that at risk while debt remains a consideration.
What The Flat Near Term Outlook Means Against Peer Expectations
Against the flat near term revenue outlook, FirstService still sits in a peer set that investors often look to for resilient property and services exposure. Screening that group using a solid balance sheet lens keeps the focus on companies that rely less on heavy leverage and more on recurring service income tied to residential and commercial properties.
Within that peer basket, flat guidance for the coming quarter looks different to the multi year expectations analysts have built into many property services stocks that clear a solid balance sheet filter. Those businesses are typically framed as aiming for steady contract driven revenue, modest operating leverage and enough financial flexibility to keep investing through softer demand without stretching credit metrics.
FirstService's current setup, with low organic growth and pressure in Roofing and Home Services, therefore leans more on execution than on top line momentum when compared with these peers. The appeal of a strong balance sheet in this context is that it can help management keep funding tuck in deals, restoration capacity and selective share repurchases even if the near term revenue line is treading water.
When you scan across property and services operators with cleaner balance sheets, the common thread is often a mix of recurring service contracts, diversified end markets and the ability to flex costs when volumes soften. FirstService shares several of those traits through Residential management fees, restoration work and Century Fire service revenue, although the cyclical Roofing exposure adds an extra swing factor that some peers in the screener may not have to the same degree.
For anyone using a solid balance sheet peer group as a reference point, the key question becomes how well FirstService can use its financial position to smooth through a period of softer organic demand. That comparison does not resolve to a simple stronger or weaker verdict. Instead it highlights that balance sheet strength may give the company room to keep investing behind restoration and Century Fire while working through a more challenging patch in Roofing and Home Services.
FirstService's analyst narrative points to US$6.5b in revenue and US$218.2 million in earnings by 2029, built on 5.1% yearly revenue growth and an earnings increase of about US$56.8 million from US$161.4 million today.
Uncover why FirstService's fair value indicates an 18% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster tightly between about US$230 and US$239 per share, which already hints at some disagreement around FirstService even before the latest flat revenue guidance. With Roofing weakness, restoration project timing and new awards in Residential all in play, you should expect opinions to diverge and explore several alternative viewpoints.
Explore another FirstService fair value estimate, including one that suggests up to 18% potential upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your FirstService research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for FirstService. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate FirstService's overall financial health at a glance.
Looking For More Investment Ideas Beyond FirstService?
If the FirstService story has you thinking about portfolio balance, this can be a good time to widen your opportunity set with other stocks that share the specific qualities you care about.
- For investors hunting for value with quality filters, consider scanning a focused set of 3 high quality undervalued stocks that combine stronger fundamentals with more modest expectations reflected in the price.
- If capital resilience matters most to you, consider building a watchlist around a 8 resilient stocks with low risk scores that screens for sturdier balance sheets and more consistent financial profiles.
- When you want fresher ideas beyond the usual large caps, consider broadening your research with a 9 high quality undiscovered gems that highlights under-followed businesses with solid underlying numbers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com