
What Nordea Bank Abp (HLSE:NDA FI)'s Earnings Update Means For Shareholders
- Nordea Bank Abp reported third quarter 2026 net interest income of €1,799 million and net income of €1,181 million, with nine month net income of €3,513 million and basic EPS of €1.03 from continuing operations.
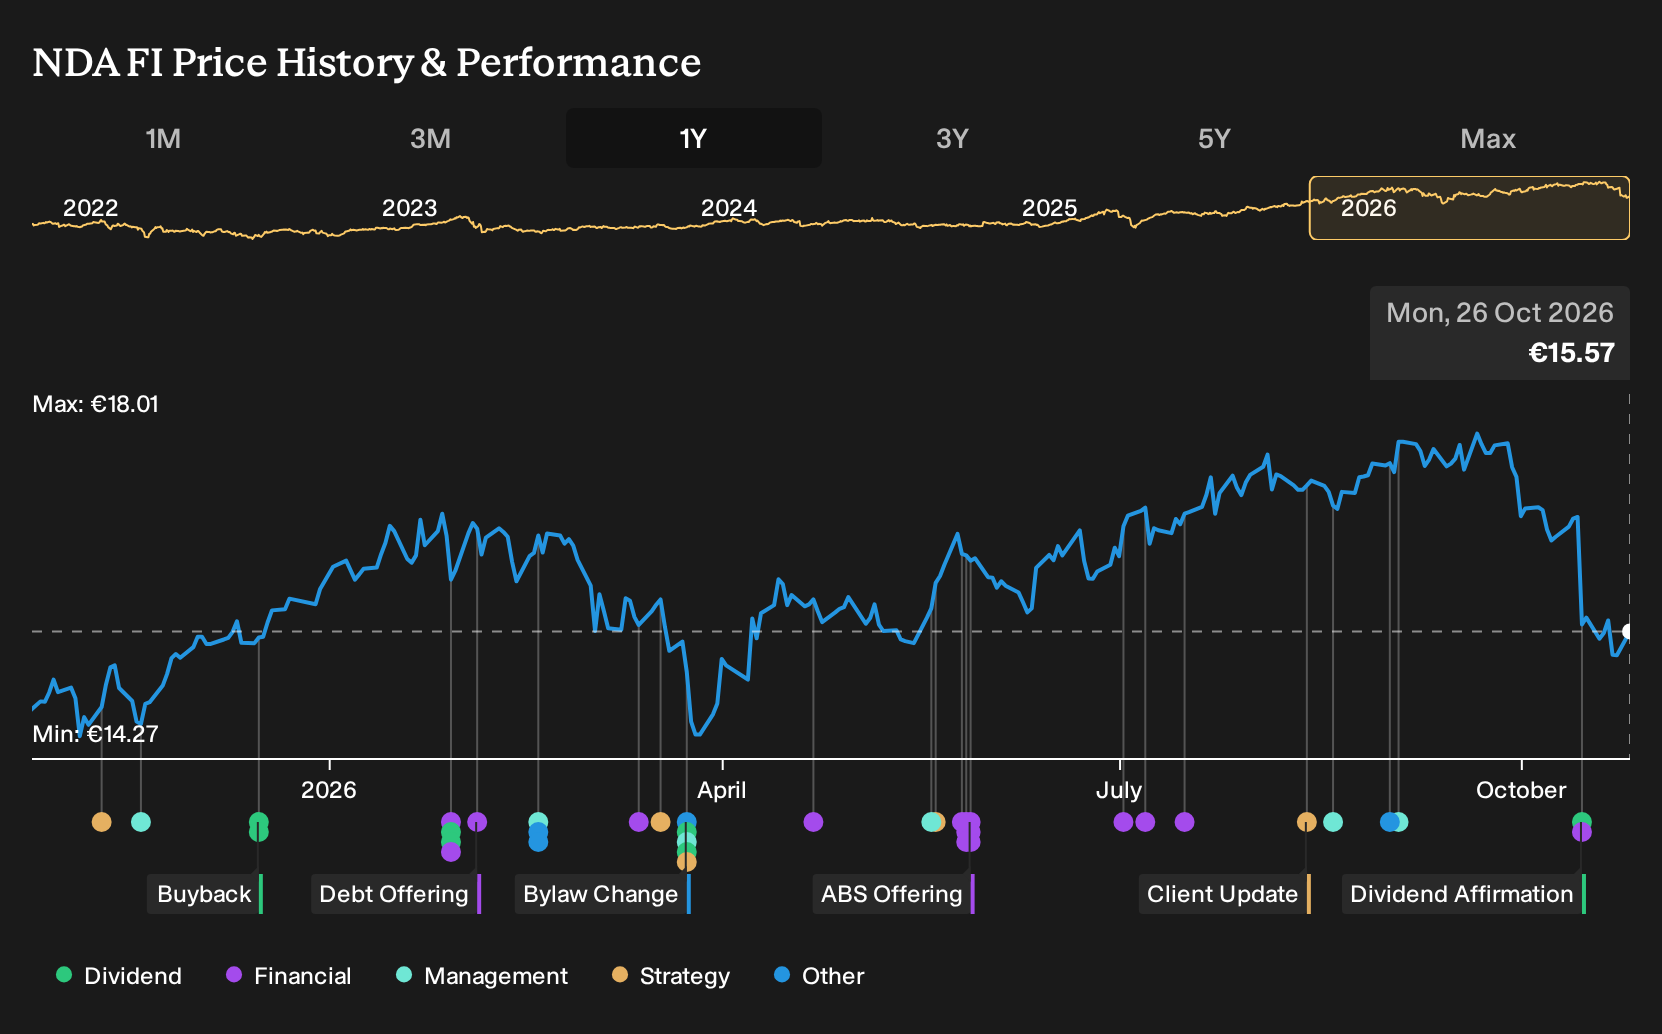
- The bank reaffirmed its dividend policy targeting a 60 to 70% payout of yearly profit and repeated that share buy backs remain an option for distributing surplus capital.
- We will now look at how Nordea Bank Abp’s investment narrative could be influenced by reaffirmed dividend payouts alongside recent earnings.
Scan how Nordea Bank Abp’s reaffirmed payout policy compares with other income-focused opportunities by reviewing our curated 224 dividend fortresses built around firms targeting robust cash returns to shareholders.
Nordea Bank Abp Investment Narrative Recap
To own Nordea Bank Abp, you need to believe the bank can keep turning a broad Nordic franchise, disciplined costs and stable credit losses into solid earnings, even as net interest income comes under pressure. The latest quarter shows revenue and profit that are slightly softer than a year ago, so the near term swing factor remains how pricing and deposit behavior affect margins.
The biggest operational risk right now sits in a mix of weaker net interest income, competitive lending markets and potential regulatory capital demands that could squeeze returns or payouts. The reaffirmed 60 to 70% dividend policy does not materially change that near term risk and reward equation, but it does clarify management’s intended balance between reinvestment and cash returns.
The most relevant update for you is Nordea Bank Abp’s reiterated dividend framework. Management is sticking with a 60 to 70% payout of yearly profit while keeping share buy backs on the table for excess capital. That message comes alongside nine month net income of €3,513 million and basic EPS of €1.03 from continuing operations.
This is directly tied to the main catalysts and concerns. Earnings are forecast to grow, but not significantly, and there are flagged questions about dividend coverage and a relatively low bad loan allowance of 62%. A stable payout ratio can support investor confidence in income, but if policy rates stay lower or regulatory buffers rise, the tension between maintaining that dividend, funding growth and preserving a strong CET1 ratio becomes the key thing to watch.
Nordea Bank Abp’s current narrative points to revenues of €13.4 billion and earnings of €5.4 billion by 2029, based on analysts’ expectations of 4.9% yearly revenue growth and an earnings increase of about €0.7 billion from the €4.7 billion reported today.
Uncover why Nordea Bank Abp's fair value indicates a 20% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span roughly €18.63 to €29.93, so retail views on Nordea Bank Abp already stretch from deep discount to richer pricing. You also need to weigh that against risks around weaker net interest income and higher capital demands, which could reshape how comfortably those community assumptions hold up.
Explore 2 other Nordea Bank Abp fair value estimates, including one that suggests up to 92% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Nordea Bank Abp research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Nordea Bank Abp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nordea Bank Abp's overall financial health at a glance.
Looking For More Investment Ideas Beyond Nordea Bank Abp?
Once you have a view on Nordea Bank Abp, it can help to cross check that income and valuation profile against other potential opportunities using the Simply Wall St Screener.
- If you want a broader value hunting ground, scan a curated 195 high quality undervalued stocks that filter for companies combining stronger fundamentals with more modest pricing.
- If capital preservation sits higher on your list, focus on a 223 resilient stocks with low risk scores that concentrates on businesses with sturdier balance sheets and lower overall risk scores.
- If you prefer sturdier finances, benchmark Nordea Bank Abp against a list of solid balance sheet and fundamentals (207 results) to find other companies with resilient capital structures and healthier fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com