
Will Raised Earnings Guidance Change First Industrial Realty Trust Stock Narrative
- First Industrial Realty Trust reported third quarter 2026 sales of US$197.12 million with net income of US$58.55 million, and for the first nine months of 2026 recorded US$586.88 million in sales and US$278.75 million in net income.
- Management raised 2026 net income guidance to a range of US$2.51 to US$2.55 per share for common stockholders and unitholders, noting that current performance is contributing to a more confident full year earnings outlook.
- The next step is to assess how this higher 2026 earnings guidance influences First Industrial Realty Trust's investment narrative around development returns and rent uplift.
First Industrial Realty Trust Investment Narrative Recap
To own First Industrial Realty Trust, you have to be comfortable with a story that leans on embedded rent uplift, lease roll ups and gradual improvement in occupancy across its logistics portfolio. The latest quarter shows higher sales but lower quarterly earnings per share compared with a year ago, which keeps the focus on how consistently the REIT can translate leasing spreads into earnings.
In the short term, the raised 2026 net income guidance puts a spotlight on execution around occupancy, rent collection and development lease up. The biggest operational risk is that occupancy does not move toward the guided range or that costs tied to activism or land inflation erode margins, which would blunt the benefit from rent mark to market.
The most relevant update here is the higher 2026 net income guidance of US$2.51 to US$2.55 per share for common stockholders and unitholders. That range sits alongside year to date basic EPS from continuing operations of US$2.10 for the first nine months. Investors can now track how the final quarter needs to perform to land inside that band.
For anyone following catalysts, that guidance effectively becomes a scorecard for how well First Industrial Realty Trust converts its rent spreads and development program into bottom line results while managing risks such as land cost pressure and occupancy execution. If actual earnings track close to the top or bottom of that interval, it will feed directly into how investors judge the durability of the current operating playbook.
First Industrial Realty Trust's analyst narrative points to forecast revenue of US$960.5 million and earnings of US$288.8 million by 2029. This profile assumes revenue growth of 7.4% per year and an earnings decrease of about US$68.6 million from current earnings of US$357.4 million.
Uncover how First Industrial Realty Trust's fair value indicates a 26% potential upside to its current price that may not last much longer.
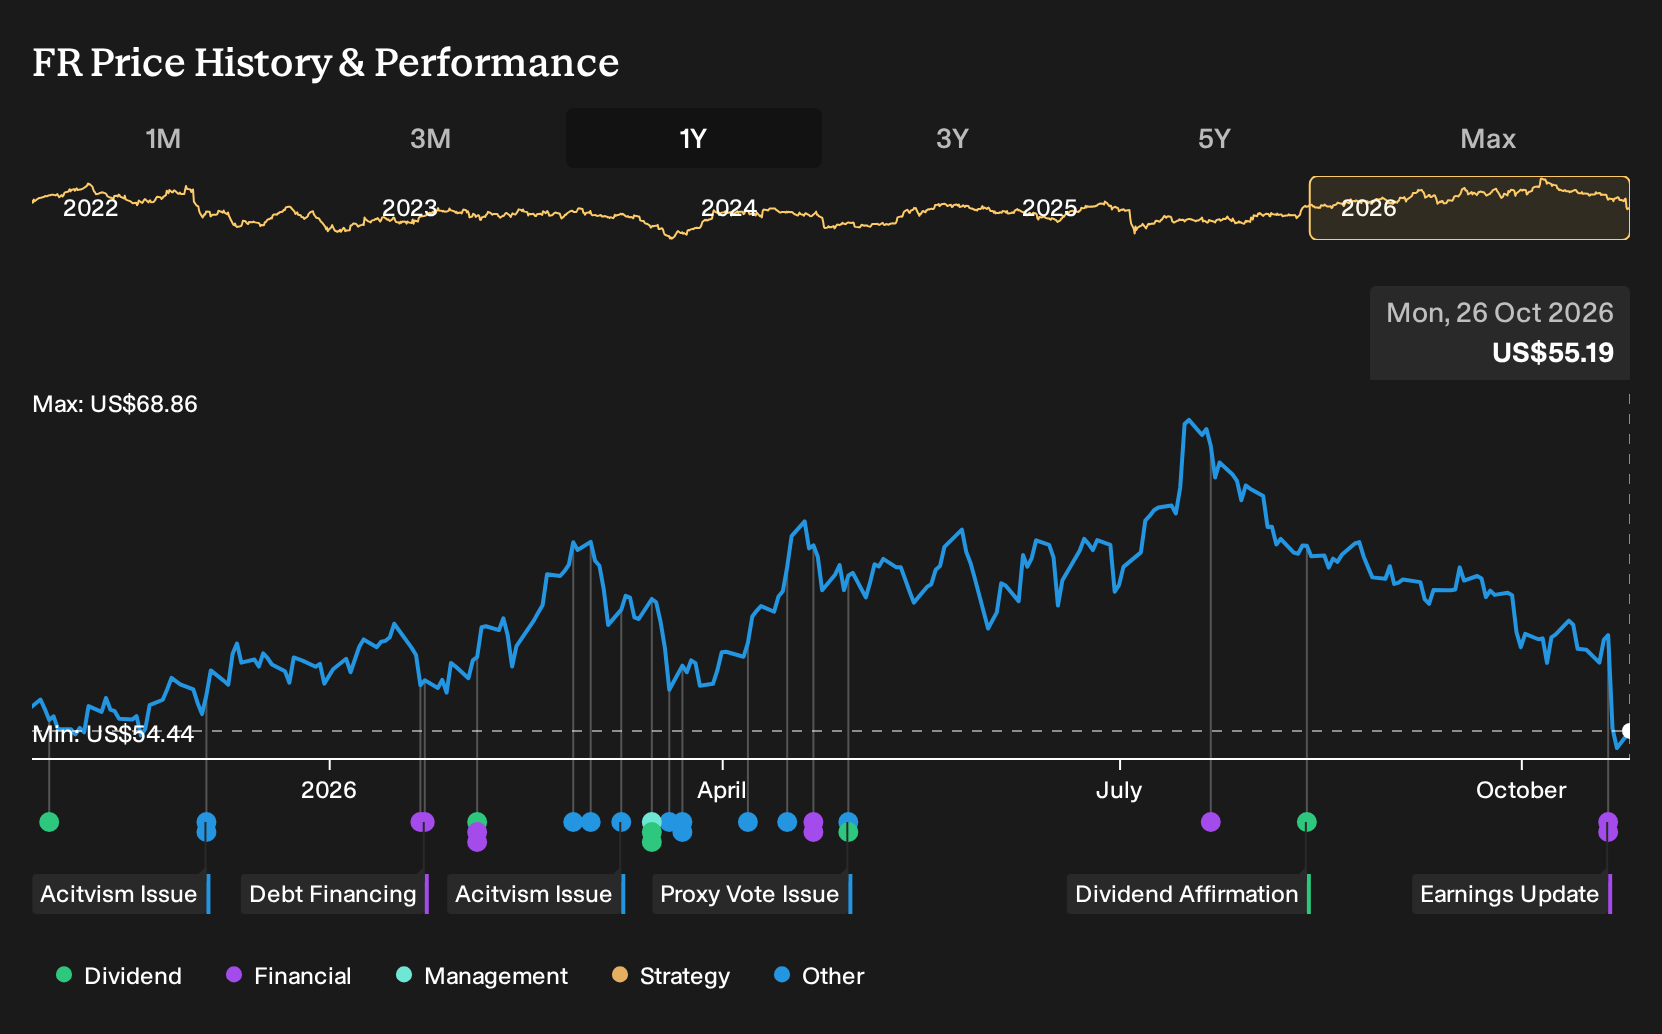
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between US$47.88 and US$69.38 per share, which illustrates the range of retail views on First Industrial Realty Trust. Those opinions do not yet reflect the raised 2026 earnings guidance or occupancy and cost risks, so you may want to explore several alternative viewpoints before deciding how this story fits your portfolio.
Explore 2 other First Industrial Realty Trust fair value estimates, including one that indicates up to 13% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your First Industrial Realty Trust research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for First Industrial Realty Trust. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate First Industrial Realty Trust's overall financial health at a glance.
Looking for more investment ideas beyond First Industrial Realty Trust?
Once the First Industrial Realty Trust story is on your radar, it can help to widen the lens and compare it with other opportunities that match your income goals, risk tolerance and time horizon. The Simply Wall St Screener is built for exactly that kind of side by side check.
- If you prefer income resilience over excitement, scan for sturdier payers by reviewing 5 dividend fortresses that meet a higher yield bar while still clearing fundamental quality checks.
- When capital preservation is your first filter, narrow your search to companies with steadier profiles by running through our 30 resilient stocks with low risk scores and see which ones fit your comfort zone.
- If you enjoy finding opportunities that are not yet heavily crowded, cast a wider net over potential future winners by browsing the 21 high quality undiscovered gems that combine solid financials with lighter market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com