
Asian Undervalued Small Caps With Insider Action To Watch In October 2026
As the Asian markets navigate a landscape marked by AI investment concerns and rising oil prices, small-cap stocks have emerged as notable performers, reflecting a broader rotation in market leadership. With the Russell 2000 Index advancing significantly amid this shift, investors are increasingly attentive to small-cap opportunities where insider actions may signal potential value. In such a dynamic environment, identifying stocks with strong fundamentals and strategic insider activities can be crucial for investors seeking to capitalize on emerging trends.
Top 10 Undervalued Small Caps With Insider Buying In Asia
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Security Bank | 4.0x | 0.9x | 21.91% | ★★★★★★ |
| Q Technology (Group) | 3.2x | 0.2x | 48.13% | ★★★★★☆ |
| Charter Hall Long WALE REIT | 8.8x | 12.5x | 38.19% | ★★★★★☆ |
| China Aircraft Leasing Group Holdings | 6.8x | 0.9x | 40.03% | ★★★★★☆ |
| Centurion | 15.7x | 3.0x | 20.53% | ★★★★☆☆ |
| Australian Finance Group | 8.0x | 0.3x | 12.67% | ★★★★☆☆ |
| Clover | 15.6x | 1.7x | 49.06% | ★★★☆☆☆ |
| Citicore Energy REIT | 12.8x | 9.7x | 29.22% | ★★★☆☆☆ |
| FINEOS Corporation Holdings | 99.5x | 2.9x | 49.46% | ★★★☆☆☆ |
| Jumbo Group | 22.7x | 0.8x | 49.23% | ★★★☆☆☆ |
Let's take a closer look at a couple of our picks from the screened companies.
HealthCo Healthcare and Wellness REIT (ASX:HCW)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: HealthCo Healthcare and Wellness REIT is a real estate investment trust focusing on healthcare and wellness properties, with a market capitalization of approximately A$1.02 billion.
Operations: HealthCo Healthcare and Wellness REIT generates revenue primarily from its operations, with a notable gross profit margin reaching 77.62% by June 2026. The company's cost of goods sold (COGS) has shown variability, impacting its profitability over time. Operating expenses have remained relatively stable around A$3 million in recent periods, while non-operating expenses have significantly influenced net income results.
PE: -8.1x
HealthCo Healthcare and Wellness REIT, a small player in the Asian market, has recently shown insider confidence with share purchases from August to October 2026. Despite reporting a net loss of A$49.7 million for the year ending June 30, 2026, compared to A$88.8 million previously, earnings are forecasted to grow annually by 64%. The company announced a quarterly dividend of A$0.015 per share and provided guidance for FY2027 distributions funded by operating earnings and cash reserves.
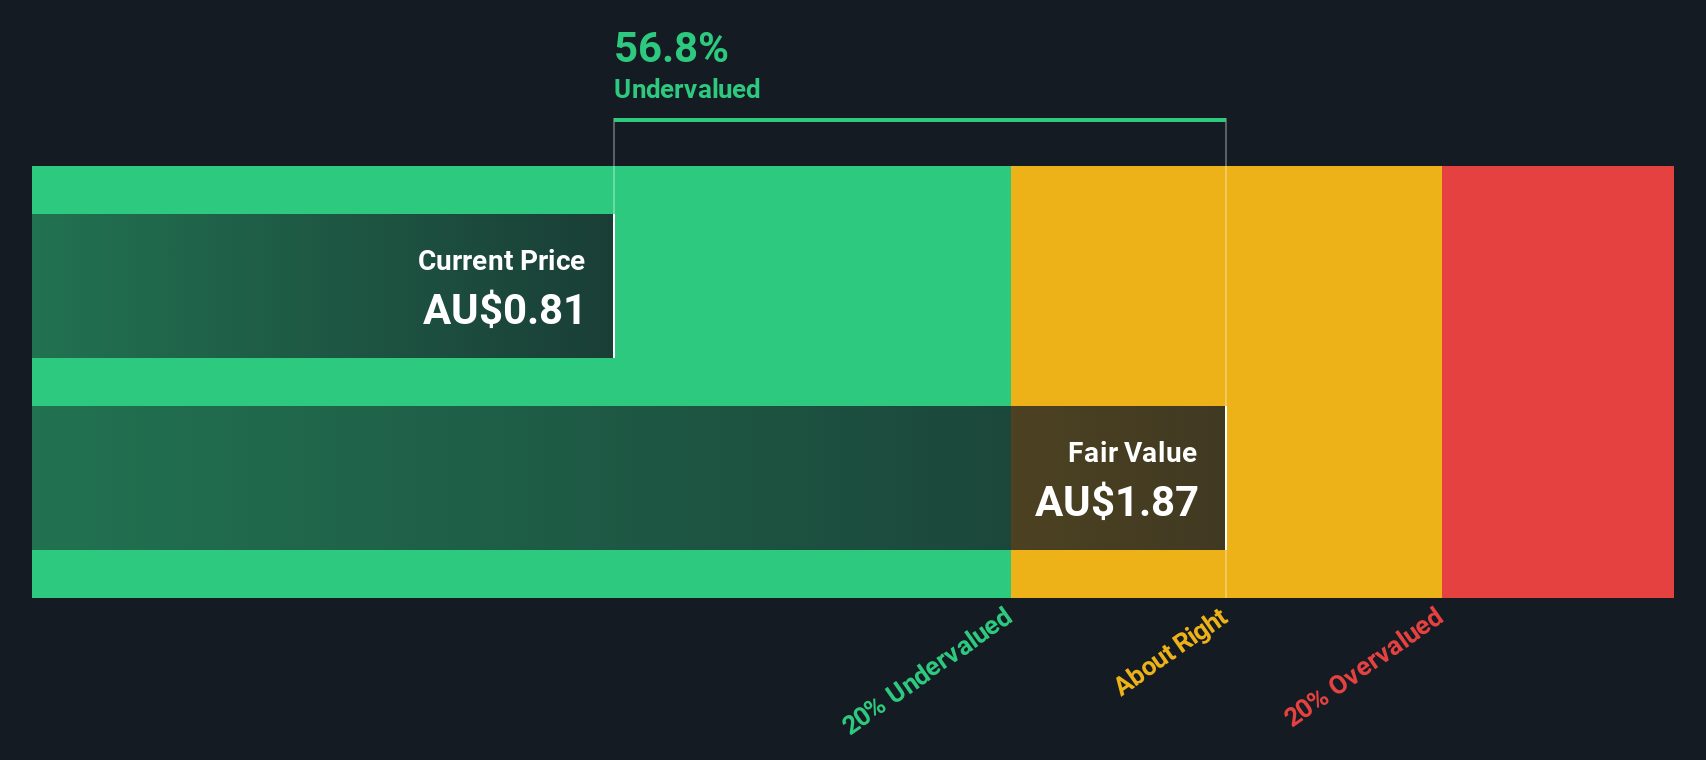
SHAPE Australia (ASX:SHA)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: SHAPE Australia operates in the heavy construction sector with a focus on delivering large-scale infrastructure projects, and it has a market capitalization of approximately A$1.2 billion.
Operations: SHA generates revenue primarily from heavy construction, with the latest reported revenue at A$1.24 billion. The company's cost of goods sold (COGS) was A$1.11 billion, resulting in a gross profit margin of 10.37%. Operating expenses include general and administrative costs, which were A$53.34 million in the most recent period. Net income reached A$31.74 million, translating to a net income margin of 2.56%.
PE: 16.8x
SHAPE Australia, a company with a growing revenue stream, has been gaining traction in the market. Earnings are projected to rise by 10.87% annually. Insider confidence is evident as Peter Massey acquired A$200K worth of shares recently, signaling belief in future prospects. The firm was added to the S&P Global BMI Index and is actively pursuing acquisitions that promise higher margins than their current operations. Despite relying on external borrowing for funding, SHAPE's strategic moves suggest potential for growth and value realization in the coming years.
- Get an in-depth perspective on SHAPE Australia's performance by reading our valuation report here.
Examine SHAPE Australia's past performance report to understand how it has performed in the past.
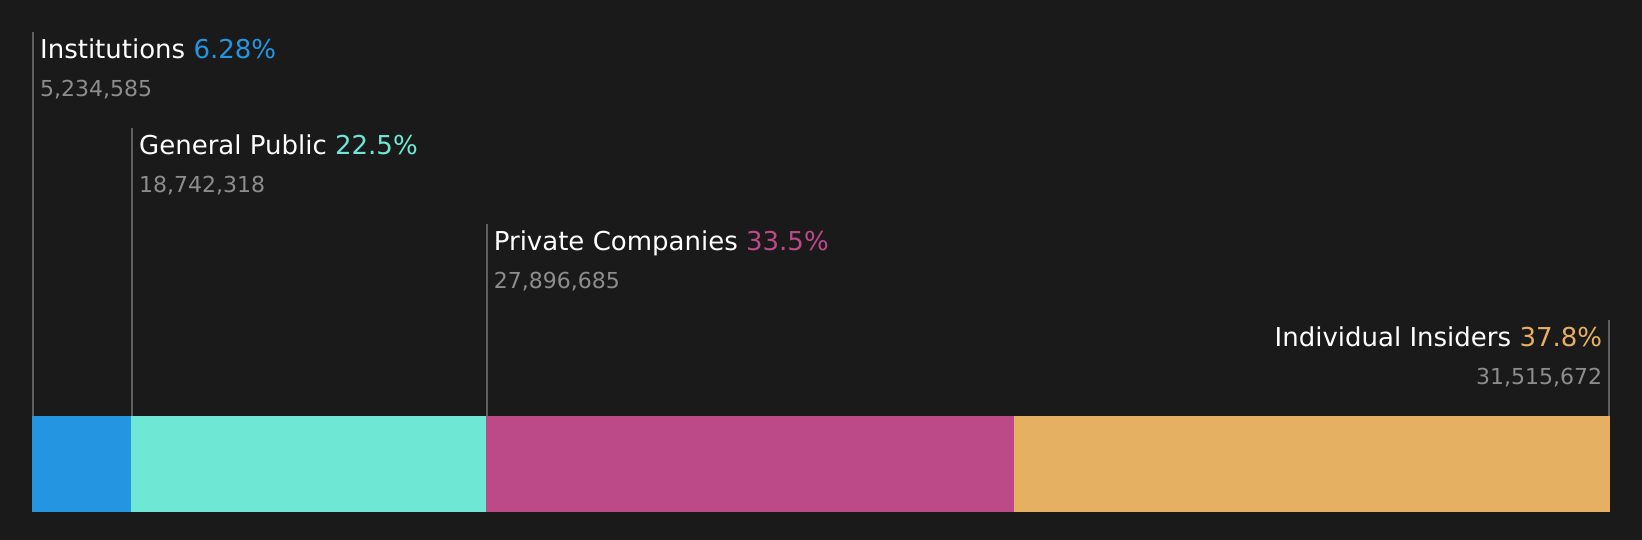
Century Pacific Food (PSE:CNPF)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Century Pacific Food is a leading food and beverage company in the Philippines, engaged in manufacturing and distributing a wide range of canned goods, dairy products, and plant-based alternatives with a market capitalization of approximately ₱97.89 billion.
Operations: CNPF's revenue primarily comes from its operations, with a notable gross profit margin of 24.78% as of June 2026. The company's cost structure is heavily influenced by the cost of goods sold (COGS), which consistently represents a significant portion of total expenses. Operating expenses also play a crucial role, comprising various components such as sales and marketing, and general and administrative costs.
PE: 13.6x
Century Pacific Food, a smaller player in the Asian market, shows signs of being undervalued with its recent financial performance. The company reported second-quarter sales of PHP 22.8 billion, up from PHP 19.8 billion last year, and net income increased to PHP 2 billion from PHP 1.99 billion. Insider confidence is evident with purchases made earlier this year, suggesting trust in future growth potential despite reliance on external borrowing for funding. Earnings are expected to grow at nearly 8% annually, indicating promising prospects in the food industry landscape.
Summing It All Up
- Unlock more gems! Our Undervalued Asian Small Caps With Insider Buying screener has unearthed 61 more companies for you to explore.Click here to unveil our expertly curated list of 64 Undervalued Asian Small Caps With Insider Buying.
- Are these companies part of your investment strategy? Use Simply Wall St to consolidate your holdings into a portfolio and gain insights with our comprehensive analysis tools.
- Simply Wall St is a revolutionary app designed for long-term stock investors, it's free and covers every market in the world.
Searching for a Fresh Perspective?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com