
Cohen & Steers (CNS), What Is Behind The Fresh Attention?
Cohen & Steers (CNS) just paired a fresh earnings update with a new real estate purchase, giving investors two concrete data points on both its asset management results and its REIT activity.
For context, Cohen & Steers’ 1 day share price return fell 1.48% to around US$71. However, the 7 day share price return is up 3.80% and the year to date share price return sits at 11.69%. The 3 year total shareholder return of 52.04% points to longer term holders still being rewarded, despite a weaker 90 day share price return that is down 13.87% and a 5 year total shareholder return that is down 11.91%. This suggests momentum has cooled recently, even as the latest earnings and REIT acquisition give investors fresh information on both fee income and real asset deployment.
Scan 21 high quality undiscovered gems that, like Cohen & Steers, pair solid fundamentals with real asset exposure and may be flying under most investors’ radar.
Cohen & Steers just paired rising fee income with a fully leased shopping center in a growing metro. The business looks robust. The open question is whether that strength is already reflected in today’s US$71 share price.
Most Popular Narrative: 1% Undervalued
Cohen & Steers closed at $71.00, while the most followed narrative pegs fair value at about $71.67, putting the stock almost exactly in line with that model and making the underlying growth story the real focal point.
Strategic expansion into active ETFs and broader product diversification, including the launch of integrated listed and private real estate strategies, is expected to attract new investor segments and improve client retention, supporting future AUM growth and revenue stability.
Ongoing investments in global distribution, including recently completed hires such as a new Head of Japan, a Chief Operating Officer for distribution and additional RIA sales roles, together with growing mandates and pipelines across multiple non US markets, are expected to drive international client inflows and scale, with potential to support operating margin resilience.
See why 4 investors see Cohen & Steers as 1% undervalued.
Result: Fair Value of $71.67 (ABOUT RIGHT)
Still, the Cohen & Steers story can change quickly if institutional clients shift allocations away from real assets or if higher distribution spending squeezes profit margins.
Find out about the key risks to this Cohen & Steers narrative.
Another View: Cohen & Steers Through A Cash Flow Lens
The fair value story shifts when you move from analyst targets to the SWS DCF model. On that framework Cohen & Steers at $71 screens as expensive versus an estimated future cash flow value of $58.17. That gap points to less room for error if sentiment cools or assumptions prove too optimistic. So which yardstick do you trust when the signals conflict?
Look into how the SWS DCF model arrives at its fair value.
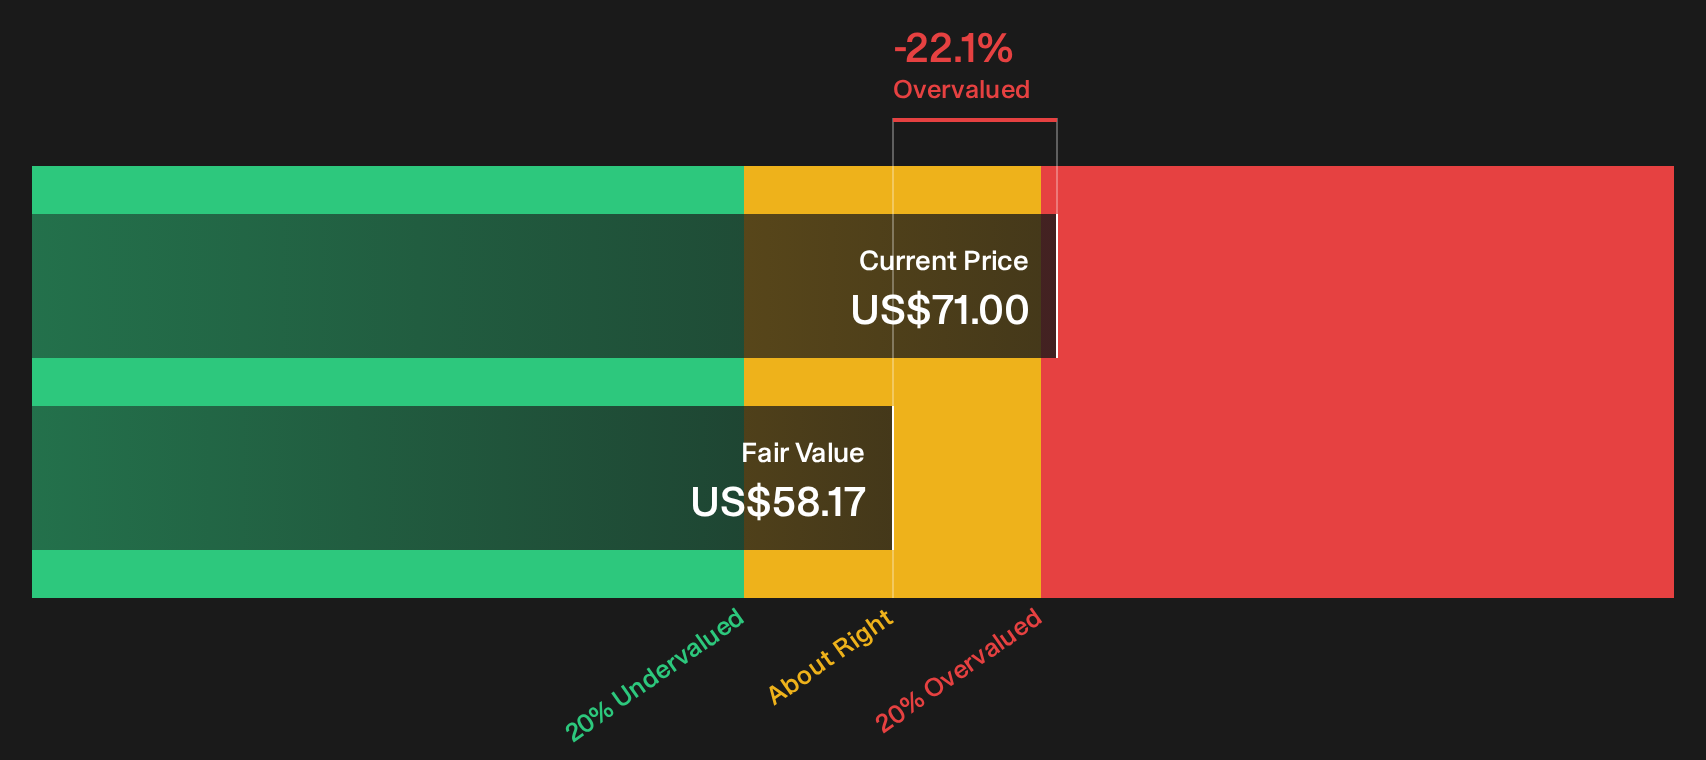
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Cohen & Steers for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Cohen & Steers so far, right? If you want to move quickly and rely on your own judgment, start by weighing the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Cohen & Steers?
If Cohen & Steers raised your interest, do not stop here. The screener can surface other opportunities you might wish you had checked earlier.
- Target dependable income streams by scanning companies screened as 5 dividend fortresses that can help anchor the yield side of your portfolio.
- Hunt for quality at a sensible entry point by reviewing a curated set of 28 high quality undervalued stocks that pair fundamentals with more appealing prices.
- Prioritize capital preservation by focusing on 30 resilient stocks with low risk scores that score well on resilience and may help smooth out portfolio swings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com