
Why Catena Bears Were Right Before The Drop
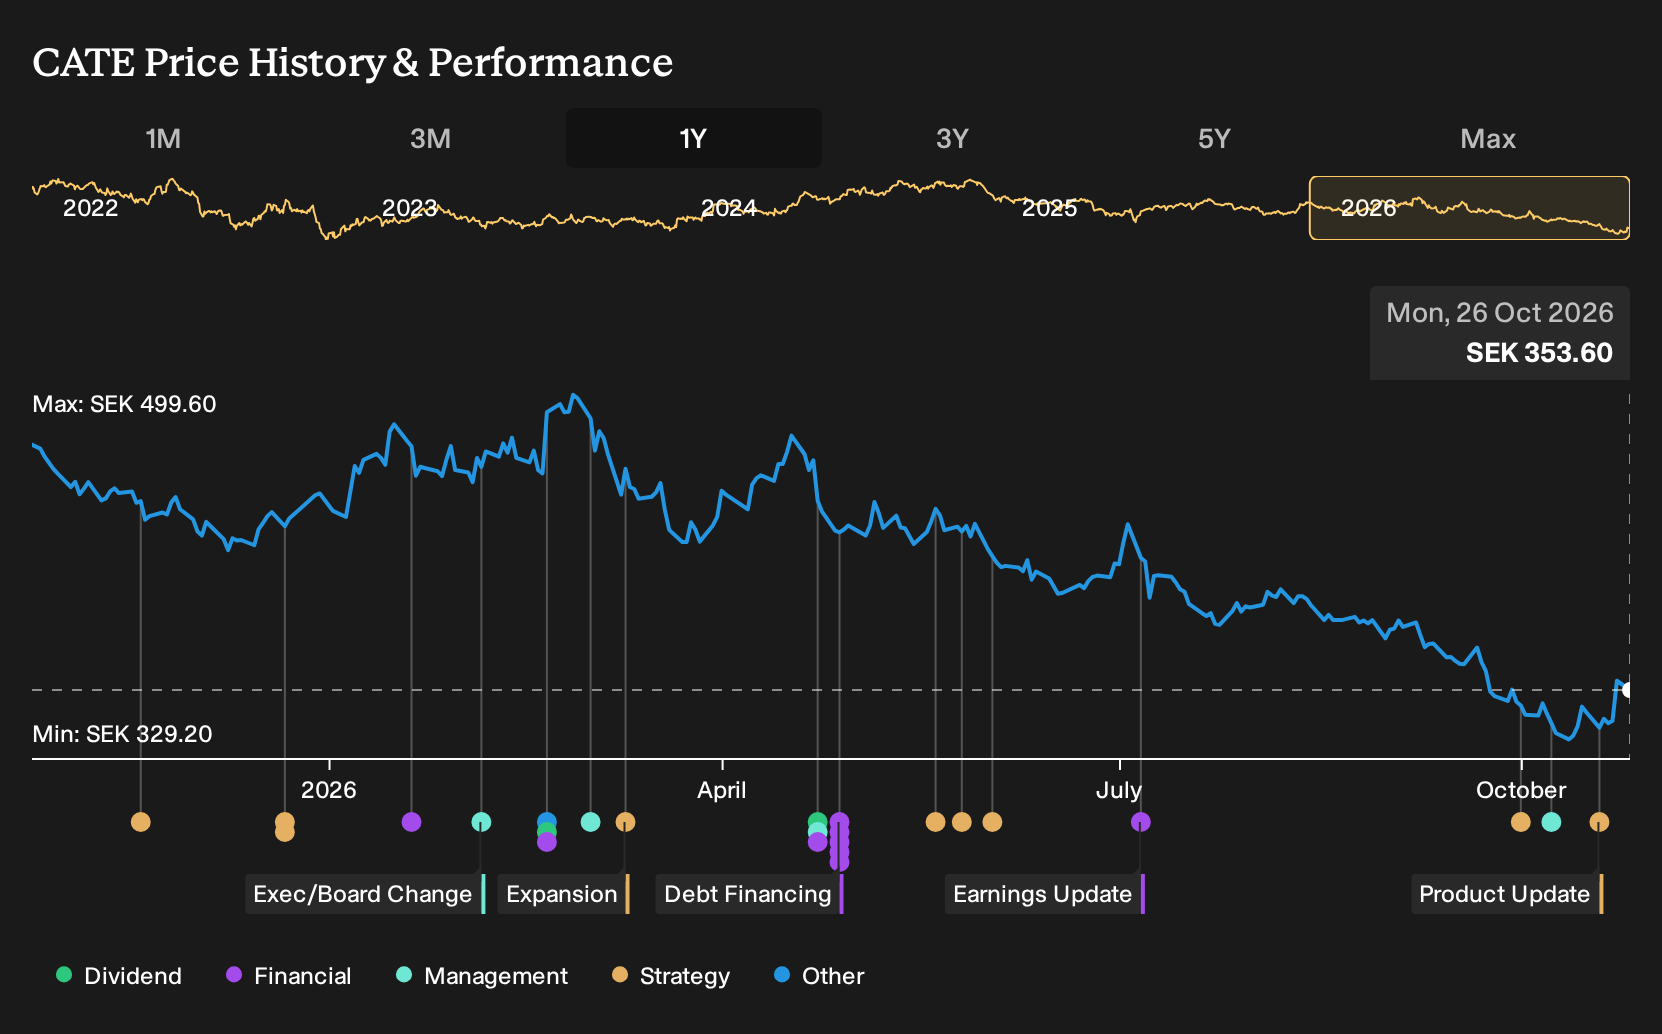
If you had been weighing up Catena in late October 2025, the loudest debate was not about collapse but about how much Danish expansion and Swedish oversupply might reshape future yields. Holding Catena over the past year would have meant a 22.7% loss, including dividends. If that setback followed an informed choice to buy, what exactly did the original case for 10% annual revenue growth and low leverage fail to factor in about vacancies, tenant caution, or rising supply?
If the move has made Catena harder to judge, start where the gap is still open and scan 194 high quality undervalued stocks.
The Argument You Would Have Been Weighing Up On Catena
The shares cost SEK476 at the start of the period, so anyone looking at Catena then had to decide whether recent acquisitions and Danish projects justified paying up for a logistics landlord facing rising vacancies in parts of Sweden.
The bullish story pointed to a Fair Value of SEK508, a level that reflected an assumption of about 10.3% annual revenue growth and a 7% yield on roughly 90,000 square meters of new developments supported by low leverage.
The cautious view anchored on a Fair Value of SEK405, built on concerns about Swedish logistics oversupply, a 9% national vacancy rate trending higher, and softer tenant demand that left rental growth stuck around 2% and margins under pressure.
What The Results Changed For Catena
Catena reported Q2 2026 revenue of SEK 806 million and net income of SEK 712 million, with net margin rising to 88.3% from 38.2%. That strength, together with 17% rental income growth and a higher property management profit, supported the case built on rental expansion and low leverage, even as occupancy dipped to 94.6%.
The useful takeaway is how much the original thesis depended on rent growth and vacancy assumptions. When you study another landlord, compare that story with reported rental income, occupancy rates, and loan to value before relying on any growth narrative.
What You Would Be Paying For In Catena Today
With Catena now at SEK354 after a 22.7% loss over the past year, the selected Narrative’s Fair Value sits above the current price and is based on a case built around Nordic expansion and relatively low leverage.
You would be considering whether continued rental income growth from acquisitions and new projects can support that view over time.
"Strategic acquisitions and new projects are driving revenue growth through increased rental income and expanded portfolio capacity. Low leverage and market expansion strategically position Catena for future growth in revenue and earnings."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
How Could You Get There Earlier?
The next headline does not have to be where your research begins. Go straight to the companies and see whether a contrarian opportunity could be taking shape.
- Company 1 - 18% below our estimate - sells automated test and power systems for AI server and 5G infrastructure spending.
- Company 2 - 23% below our estimate - adds sales staff to win maintenance contracts and deepen modernization focused customer relationships.
- Company 3 - 44% below our estimate - shifts oncology software toward recurring support contracts as AI planning tools gain broader use.
Those are three of them. See every one of the 207 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com