
How Investors Are Reacting To Fanuc (TSE:6954) Strong Earnings Report
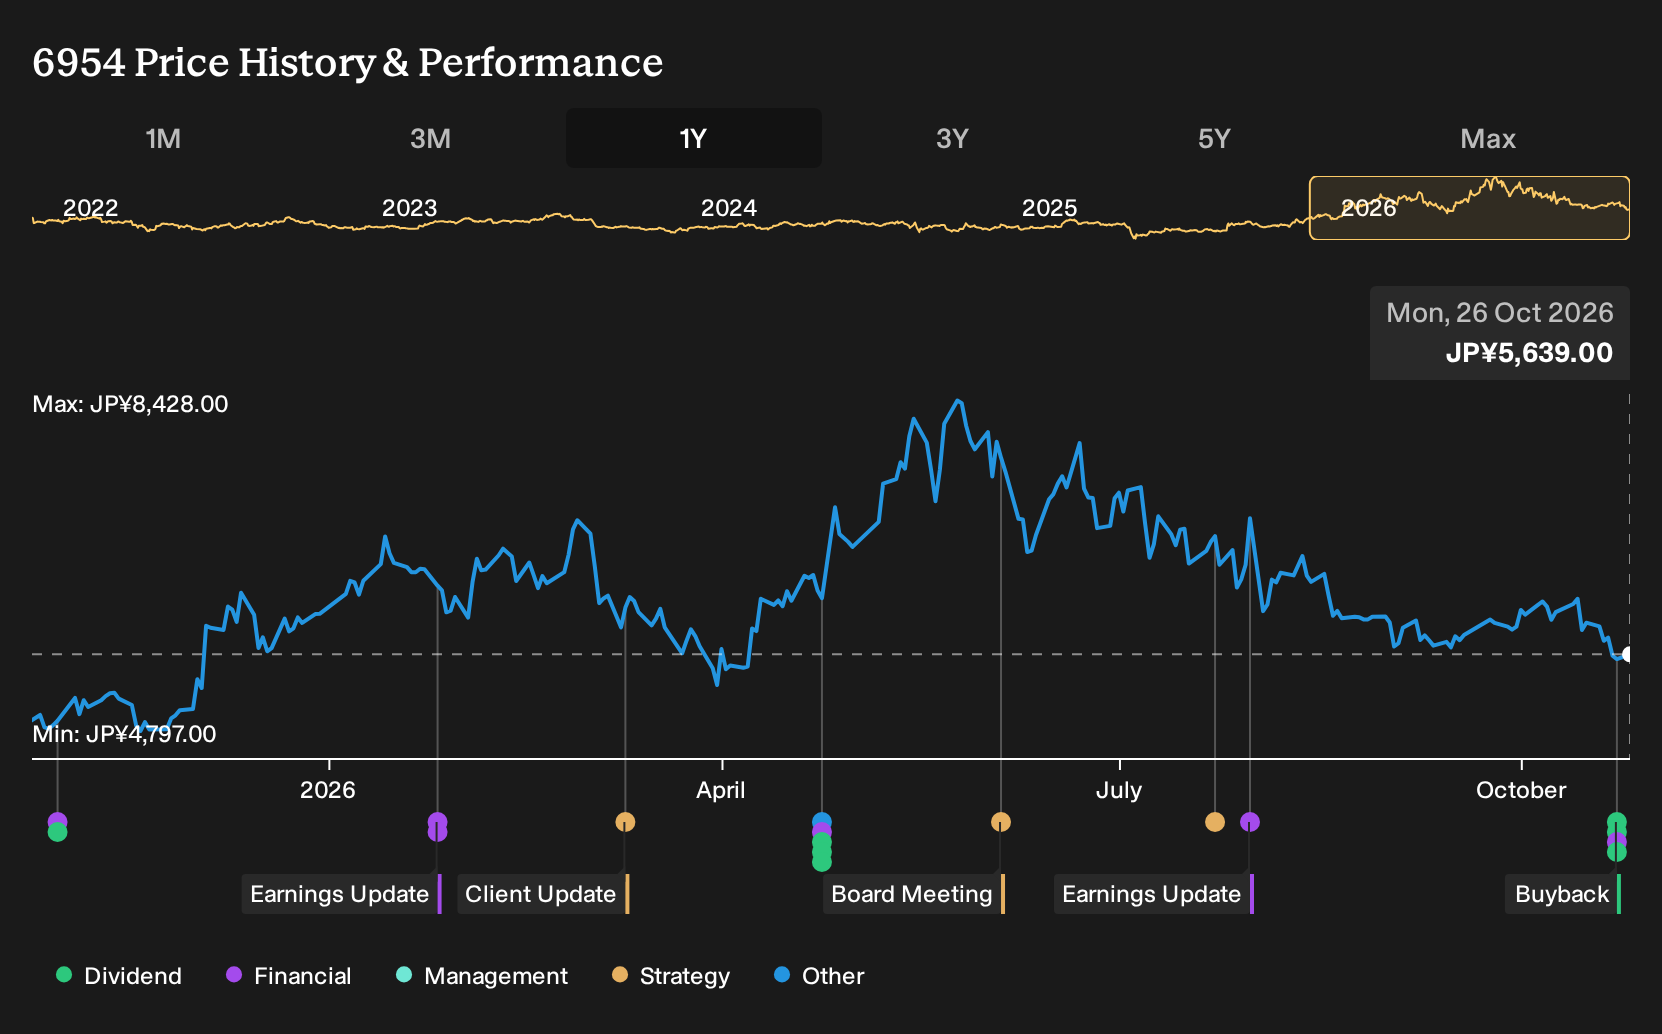
- Fanuc Corporation announced on 23 October 2026 a share repurchase program of 10,000,000 shares, Q2 2027 earnings guidance, and a higher second quarter dividend of ¥72.54 per share compared with ¥51.33 a year earlier.
- The combination of planned buybacks equal to 1.08% of outstanding shares, raised quarterly payouts, and detailed full year profit targets reflects management’s focus on capital returns and balance sheet flexibility in a changing operating backdrop.
- The next focus is how Fanuc’s investment narrative is shaped by the new buyback plan and richer dividend stream.
Scan how Fanuc’s capital return shift compares with other robotics plays by reviewing our hand picked list of 94 robotics and automation stocks in the automation space.
What Is Fanuc's Investment Narrative?
To own Fanuc, you need to buy into a simple idea. High quality automation hardware, sold into global factories, can keep earning solid returns over time if execution stays tight and capital spending is disciplined. The latest guidance for ¥1,013,700 million in net sales and ¥240,700 million in operating income underlines that management is running the business with clear volume and profit targets, not just financial engineering. The announced buyback and richer dividend signal confidence in cash generation and a willingness to recycle surplus funds back to you as a shareholder.
In the short term, the key swing factors remain order momentum for robots and CNC systems, pricing power against global rivals, and how capex cycles at customers evolve. The ¥50,000 million repurchase, equal to 1.08% of shares, does not change those operational drivers, but it can support per share metrics if demand softens. At the same time, an increased dividend leans into an income angle even as the track record has been described as unstable, and that mix of higher payouts with a P/E above peer averages creates a different kind of pressure if earnings growth undershoots.
Yet there is a less comfortable angle to this Fanuc story once you look closely at ...
There's only one way to know the right time to buy, sell or hold Fanuc. Head to Simply Wall St's company report for the latest analysis of Fanuc's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly ¥4,500 to ¥7,220, which already shows how far opinions on Fanuc can stretch. Those views do not yet reflect the latest buyback and dividend guidance. Updated reactions to capital returns and earnings targets could push future community estimates even further apart, so explore several viewpoints before deciding how you frame the story.
Explore another Fanuc fair value estimate, including one that suggests up to 28% potential upside from the current price.
The Verdict Is Yours
Do not just follow the ticker; dig into the data and build a conviction that is truly your own.
- A great starting point for your Fanuc research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Fanuc. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fanuc's overall financial health at a glance.
Looking For More Investment Ideas Beyond Fanuc?
If the Fanuc story has sharpened your thinking about capital returns and quality, it can help to widen the lens and see how other businesses stack up on income, value, and balance sheet strength using the Simply Wall St Screener.
- If you want income resilience rather than just headline yield, scan a curated set of 29 dividend fortresses that focus on payout strength and consistency.
- For value driven investors hunting for quality at a reasonable price, start with a targeted group of 16 high quality undervalued stocks that combine solid fundamentals with attractive valuations.
- When capital preservation matters as much as upside, narrow your watchlist to a focused 22 resilient stocks with low risk scores that screens for resilient balance sheets and lower overall risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com