
Anterix (ATEX) Could Be 13% Undervalued As Spectrum Monetization Still Looms
Anterix (ATEX) has drawn fresh attention after a recent move in the share price, with the stock closing at US$74.90 on 24 October 2026. That price now anchors the latest discussion around its spectrum focused business.
That latest move comes after a powerful run for Anterix, with the share price up 236.93% year to date and contributing to a 267.52% total shareholder return over the past year, even as the 90 day share price return has fallen 18.03%. This hints that momentum may be cooling and that investors are reassessing both growth potential and risk.
Scan beyond Anterix and see how other spectrum and infrastructure focused companies are priced right now by reviewing our hand picked 42 power grid technology and infrastructure stocks in one place.
Anterix now trades far above where it started the year, yet well below published analyst targets. Has most of the easy upside already played out, or does the current valuation still leave meaningful headroom?
Most Popular Narrative: 13% Undervalued
The most followed narrative for Anterix pegs fair value at $86.00, which sits above the latest $74.90 close. This frames the recent pullback as a potential valuation gap rather than a completed story.
Although utilities are showing interest in private broadband networks as they modernize grids, Anterix still has roughly 85% of its spectrum yet to be monetized. Any delay in converting that interest into contracts could slow the realization of expected spectrum value and defer cash inflows and earnings.
See why 0 investors see Anterix as 13% undervalued.
Result: Fair Value of $86.00 (UNDERVALUED)
Still, Anterix faces real tripwires if utilities slow 900 MHz contract signings, or if spectrum clearing and FCC licensing progress more slowly than investors expect.
Find out about the key risks to this Anterix narrative.
Another View on Anterix Using Earnings Multiples
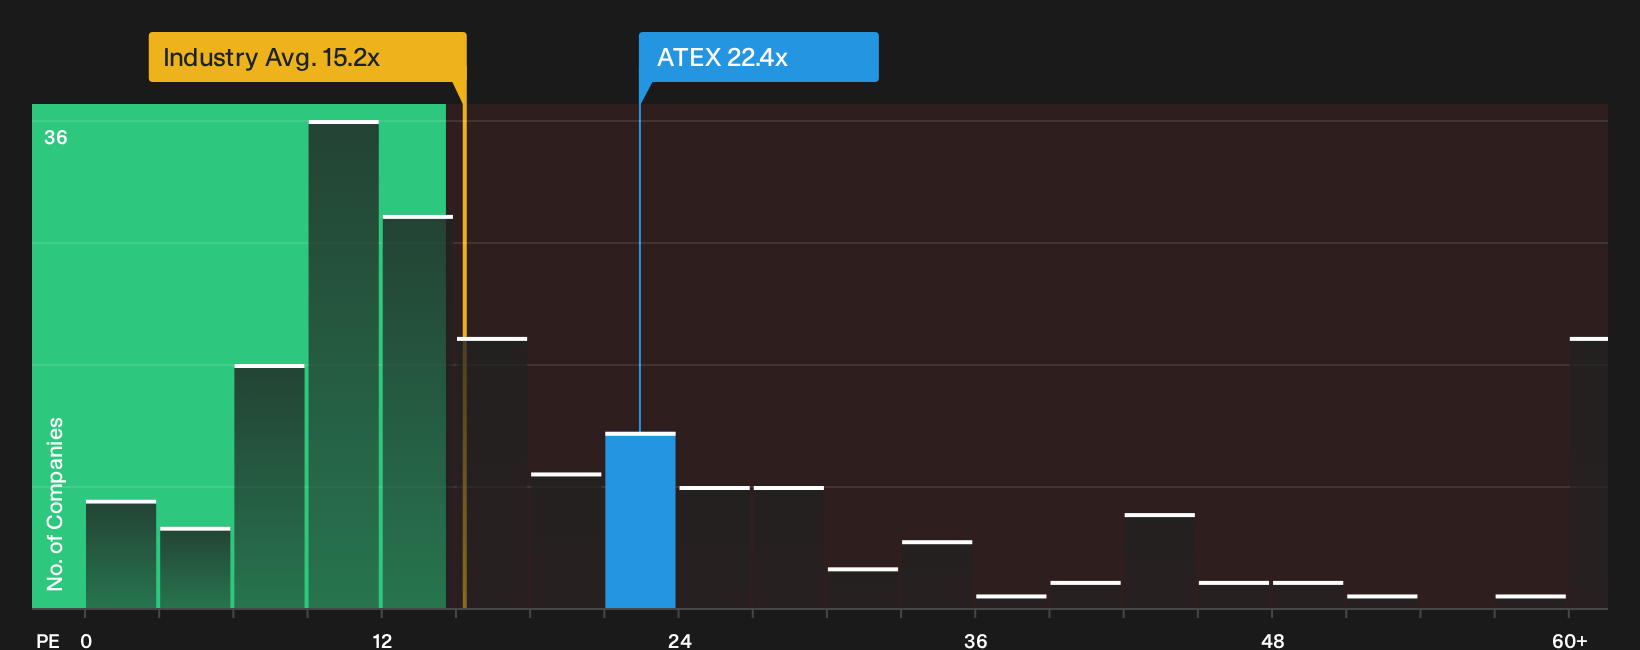
That $86.00 fair value lens tells one story. A different one comes from the P/E ratio. Anterix trades at 22.4x earnings, which is higher than the global Telecom industry at 15.2x and far above the fair ratio estimate of 3.3x. This wide gap points to meaningful valuation risk if sentiment cools.
To see how this earnings based view stacks up against other valuation checks, and how stretched pricing could affect your margin of safety, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Anterix is clearly mixed, with sharp gains sitting beside valuation questions and execution risks. If you want to move beyond headlines and price charts, you can weigh the key concerns and potential upsides yourself through the 1 key reward and 3 important warning signs.
Looking for more investment ideas beyond Anterix?
If Anterix has your attention but you want a broader watchlist, use the Simply Wall St screener to surface fresh, data driven opportunities before others spot them.
- Target potential mispricing by scanning a 28 high quality undervalued stocks that may offer stronger fundamentals than the headlines suggest.
- Protect your capital first by reviewing a 30 resilient stocks with low risk scores that screens for resilient businesses with steadier risk profiles.
- Spot tomorrow’s potential leaders early by checking a 21 high quality undiscovered gems that the wider market may not be watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com