
Builders FirstSource (BLDR) Nears Earnings Under Pressure, Is It Still 23% Undervalued?
Builders FirstSource (BLDR) heads into its third quarter 2026 earnings release on October 29, with investors focused on expected pressure on profitability and net sales as housing affordability and interest rates weigh on residential construction.
Over the past year, Builders FirstSource has been a tough ride for shareholders, with the share price down 45.67% year to date and the 1-year total shareholder return declining 53.85%. A recent 7-day share price gain of 7.37% hints at short-term momentum trying to rebuild after a 22.84% drop over 90 days.
Spot shifts in housing-exposed construction plays like Builders FirstSource and compare them with a hand-picked list of solid balance sheet and fundamentals (24 results) that may handle prolonged rate pressure more resiliently.The question now is whether Builders FirstSource’s sharp pullback, followed by only a recent bounce, means most of the easy upside is already gone, or if the current valuation still leaves meaningful room ahead.
Most Popular Narrative: 23% Undervalued
Builders FirstSource closed at $56.85, while the most followed narrative pegs fair value at $73.36. This estimate uses a 10.76% discount rate to pull future cash flows back into today’s dollars. That gap sits alongside a business story built around higher margin products, digital tools and cost control rather than just a housing volume rebound.
Builders FirstSource is still investing heavily in digital transformation and value-added solutions such as digital tools, ERP integration and prefabricated components. This positions the company to improve operating efficiency and customer stickiness as housing activity recovers, supporting future revenue and net margins.
See why 27 investors see Builders FirstSource as 23% undervalued.
Result: Fair Value of $73.36 (UNDERVALUED)
Still, the narrative around Builders FirstSource can break if housing demand stays weak for longer, or if competitive pricing pressure keeps squeezing margins and earnings expectations.
Find out about the key risks to this Builders FirstSource narrative.
Another View: Builders FirstSource Through The P/E Lens
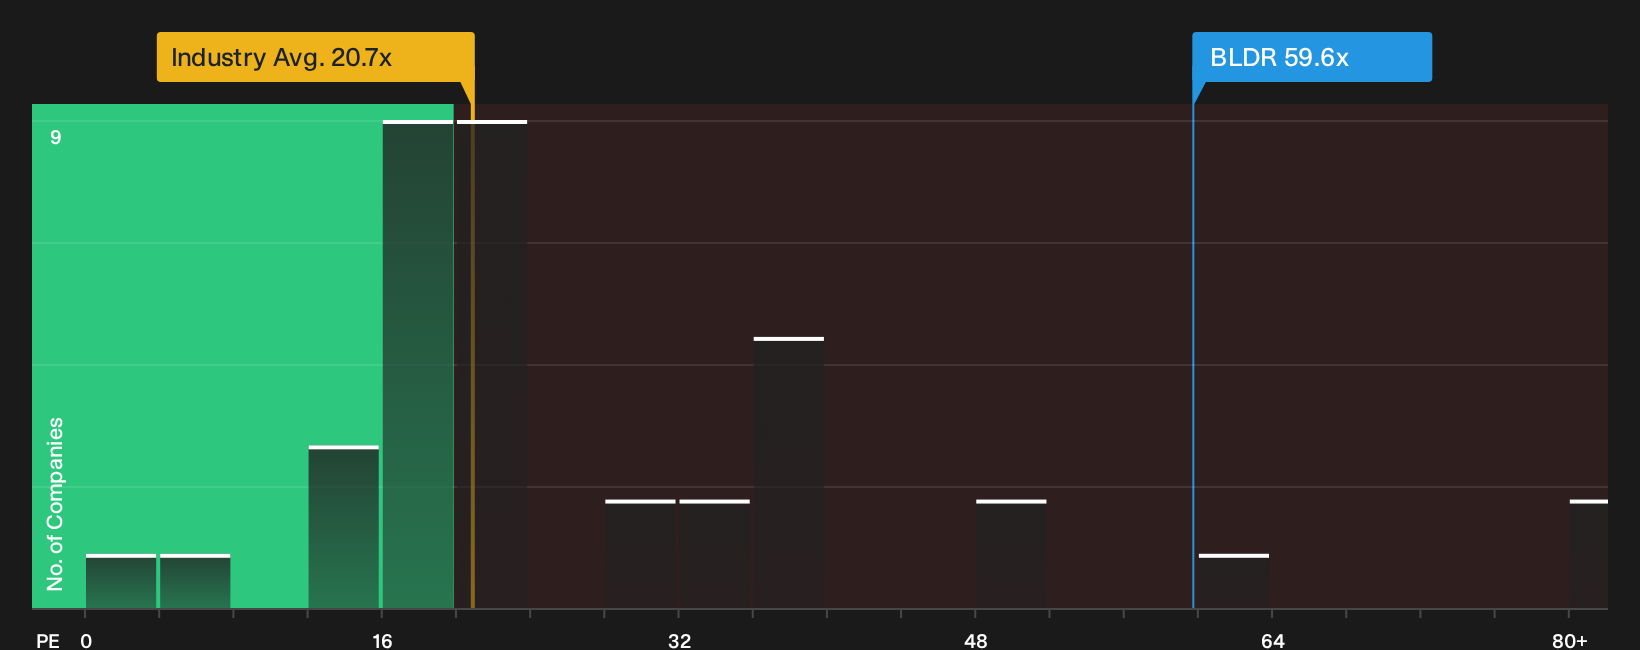
There is a catch to the Builders FirstSource undervaluation story built on future cash flows. On a simple P/E yardstick of 59.6x, the stock trades far richer than the US Building industry at 20.7x, and even above its own fair ratio of 52.9x, which points to real valuation risk if sentiment cools.
For investors comparing these signals, the question is whether the SWS fair ratio or the discounted cash flow view should carry more weight when price and fundamentals drift apart.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Builders FirstSource is clearly mixed, with concerns and bright spots pulling in opposite directions. If you want to move quickly, test the numbers yourself. To see both sides laid out in one place, weigh up the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Builders FirstSource?
If Builders FirstSource has your attention, do not stop here. Fresh opportunities often appear where pricing, quality and balance sheet strength line up before headlines catch on.
- Target potential mispricings by scanning a 28 high quality undervalued stocks that filters for businesses combining solid fundamentals with attractive valuations.
- Build a steadier income stream by reviewing a 5 dividend fortresses that highlights companies aiming to sustain higher-yield payouts.
- Prioritise resilience by working through a 30 resilient stocks with low risk scores focused on financially robust businesses with lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com