
What Astellas Pharma Holders Bought Into
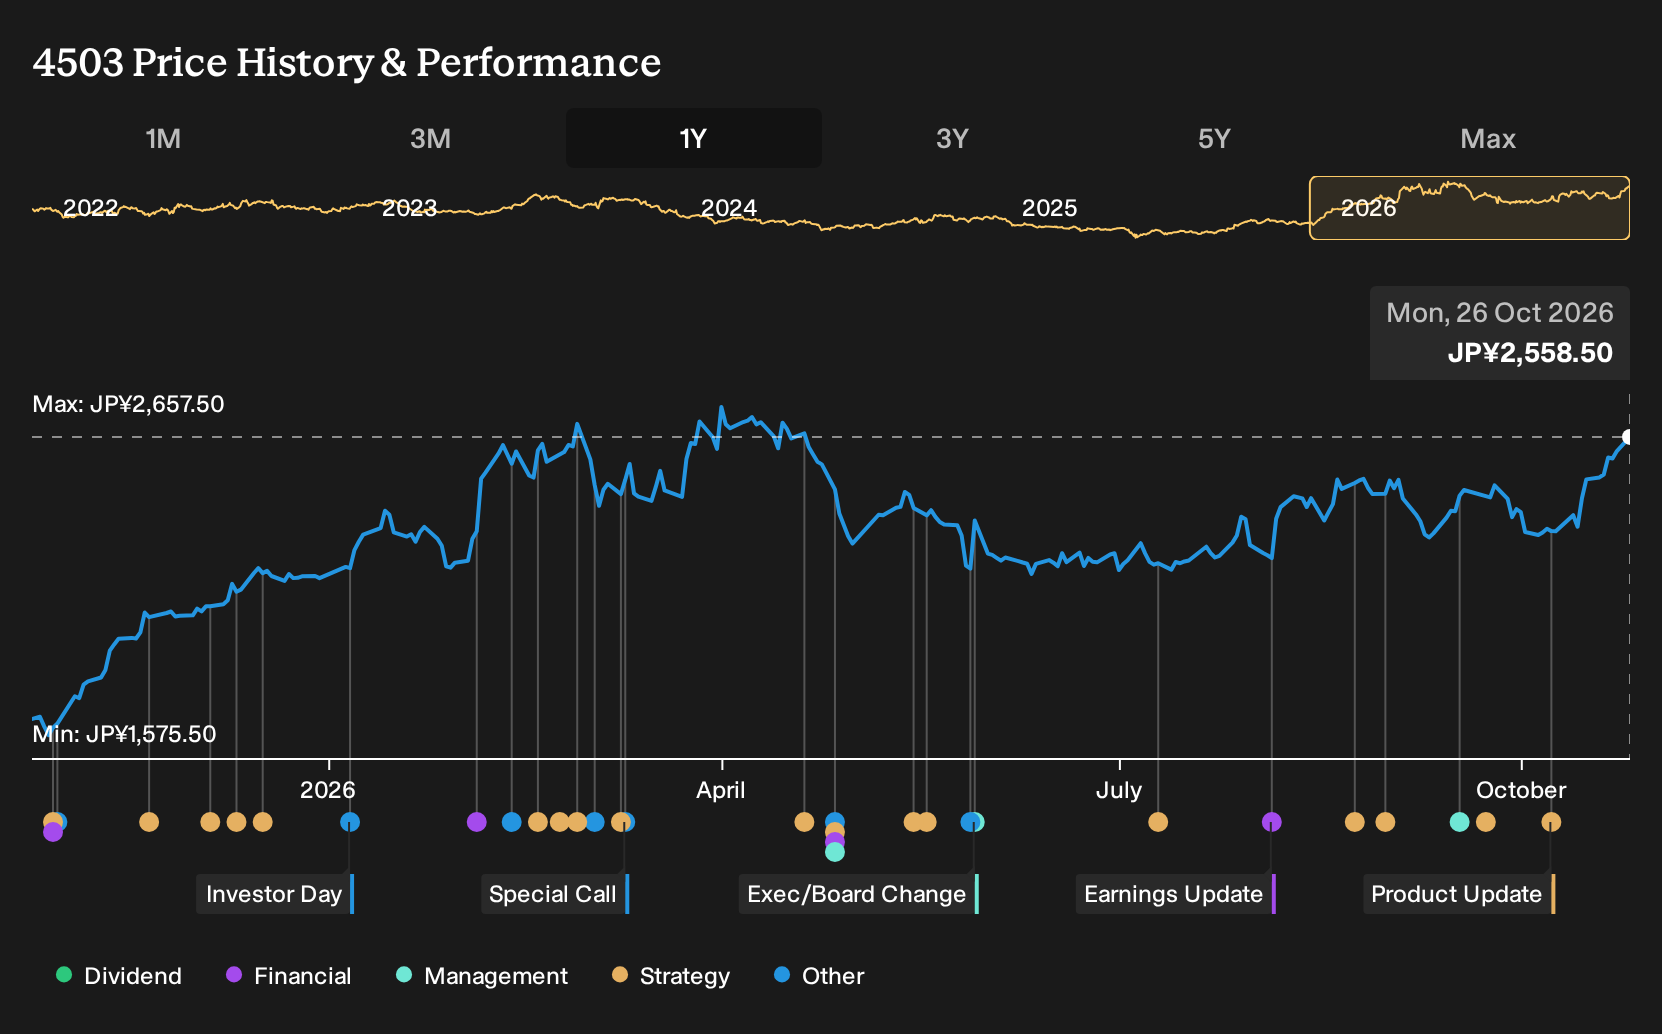
If you only glanced at the headlines on drug price reforms and looming patent losses, Astellas Pharma might have looked like a minefield in late 2025. Investors who held Astellas Pharma over the past year are up 61.5%, including dividends. That sits alongside analyst models that baked in revenue shrinkage and rising margin pressure. If you were weighing those clashing views a year ago, what should have mattered most in your decision?
Astellas Pharma has already moved. Pinpoint other ways to investigate the theme among 10 healthcare AI stocks.
The Argument You Would Have Been Weighing On Astellas Pharma
The shares cost ¥1,628 at the start of the period, and anyone looking at Astellas Pharma had to choose between two very different stories.
The bullish narrative pointed to oncology and rare diseases as global growth engines, with a Fair Value of ¥1,725, the price those assumptions implied. Supporters leaned on ideas like revenue shrinking only 1.6% a year while profit margin reached 9.9% and a future P/E of 19.3x.
The bearish camp focused on patent expirations and pricing reforms, tying its Fair Value to ¥1,300. That view stressed pressure from generic competition after XTANDI and mirabegron lose exclusivity and the risk that R&D setbacks fail to replace expiring products.
What The Results Changed For The Astellas Pharma Debate
The most concrete update was Astellas Pharma’s Q1 2027 report. Revenue reached ¥640,914m and net income came in at ¥141,828m, with net margin recorded at 22.1% compared with 13.5% a year earlier. That level of profitability backed the optimistic story about margins improving while still leaving the long term patent and pricing worries unresolved. The evidence cut both ways.
The key assumption this episode tested was margin resilience. For any other drug maker in a similar bind, you would track whether net margin is moving toward the scenario baked into the thesis and compare that figure, not the share price, with what was assumed at the decision date.
What Astellas Pharma’s Price Already Bakes In
Astellas Pharma now trades at ¥2,558, after a 61.5% gain over the past year. The selected Narrative argues that its Fair Value sits below today’s level, because the current quote already embeds ambitious expectations for life after XTANDI.
You would be asking what has to keep working for that price to hold up. The Narrative highlights a buyer assumption that higher margin brands and late stage assets scale smoothly enough to offset XTANDI pressure, while cost savings and pricing choices still support the planned margin structure.
"Although Astellas Pharma outlines a shift from XTANDI toward higher margin brands, the expected drop of about ¥50b in XTANDI revenue from pricing pressure and emerging patent expiries could leave a larger gap than these products fill, which would weigh on total revenue and earnings."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Which Company Could Surprise You Next?
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 23% below our estimate - expands its sales force to win more elevator maintenance contracts.
- Company 2 - 35% below our estimate - uses AI driven hiring tools and sponsored listings to deepen job ad monetization.
- Company 3 - 50% below our estimate - shifts staff incentives toward ARR growth from consolidated security platform subscriptions.
That is three of the list. See all 23 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com