
3 Canadian Growth Stocks With Earnings Growth Up To 35%
European natural gas prices hitting a four year high have pushed energy costs back into the spotlight for Canadian households and businesses. Investors are hunting for home grown growth stories where insiders have real skin in the game rather than relying on expensive external funding. This article looks at three fast growing Canadian stocks with high insider ownership from our screener that aim to align management with shareholders.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where management is aligned with shareholders through high insider ownership. However, if you want the strongest names, these 9 high growth high conviction stocks are the top of the list.
Aritzia (TSX:ATZ)
Overview: Aritzia is a Vancouver based womenswear retailer that designs and sells its own premium casual and activewear brands through boutiques and digital channels, aligning tightly with a fast growth, omni channel fashion focus.
Operations: Aritzia generates about CA$4.3b in apparel revenue, with roughly CA$1.6b from Canada and CA$2.8b from the United States, reflecting its growing cross border footprint.
Market Cap: CA$17.6b
Aritzia matters for this high growth, insider aligned screener because its premium womenswear labels lean heavily on rapid store rollout and expanding online reach. Together, these factors shape how quickly earnings can scale from here.
"Aritzia's ongoing U.S. boutique rollout, with new locations reportedly paying back in under one year and management indicating room to expand from roughly 76 to 82 to at least 180 to 200 boutiques, points to a continued store-led uplift to net revenue."
What happens to Aritzia’s growth profile if one unseen pressure quietly shifts how much profit each new boutique actually keeps?
That quiet shift is exactly what runs through the full narrative for Aritzia, where boutique payback, insider ownership and margin pressure all collide in one story that appears to be accelerating.

Cascades (TSX:CAS)
Overview: Cascades is a Kingsey Falls based producer of packaging and tissue products, with its e commerce and protective packaging aimed at high growth online retail and logistics demand alongside a broader tissue and recycling operation.
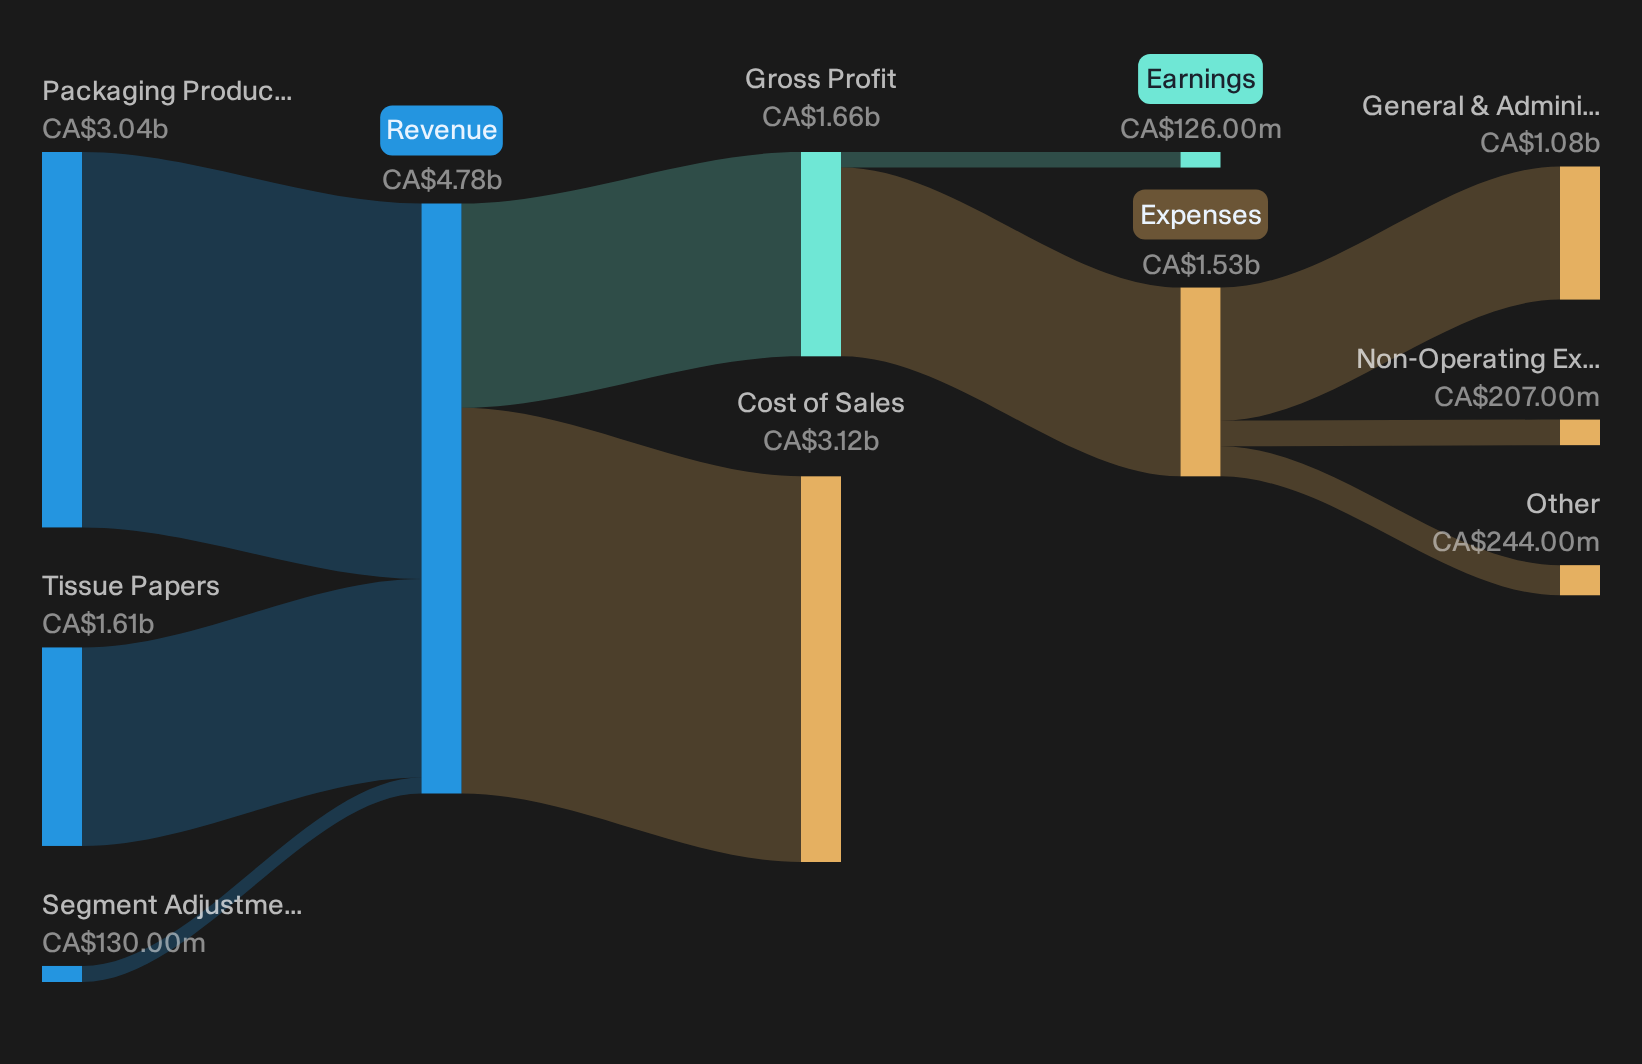
Operations: Cascades generates about CA$3.0b from Packaging Products and CA$1.6b from Tissue Papers, with revenue split roughly evenly between Canada and the United States.
Market Cap: CA$1.7b
Cascades provides direct exposure to higher demand for e commerce friendly boxes and protective packaging, supported by management and analyst optimism that this part of the portfolio can carry more of the growth story.
"Continued ramp up at the Bear Island mill toward Greenpac level efficiencies, combined with targeted reductions in chemical and material usage, should lift Packaging segment productivity and support structurally higher EBITDA margins."
The key uncertainty for Cascades is what happens if one assumed shift in cost efficiency and pricing power does not fully materialize.
If that shift is what you are weighing up, read the full narrative for Cascades to see how Cascades’ cost work, pricing power and insider alignment all intersect.
Cardinal Energy (TSX:CJ)
Overview: Cardinal Energy is a Calgary based producer that acquires, develops, and optimizes oil and natural gas assets across Western Canada.
Operations: Cardinal Energy generates about CA$550 million in revenue from oil and gas exploration and production activities entirely within Canada.
Market Cap: CA$2.4b
Cardinal Energy fits this fast growing, insider focused screen because its business centers on upstream oil and natural gas production, where operational execution directly influences its growth profile.
"Low debt, with room to issue more to cover dividend or existing growth project if needed by YE 2025 as a low fiscal risk position. Allows for strategic M&A if a downturn occurs for pulling ahead of competition."
What happens to Cardinal Energy’s growth story if one assumed support for that expansion pipeline quietly weakens just as new barrels arrive?
If that shift is your concern, the full narrative for Cardinal Energy shows where Cardinal Energy’s low debt, payout plans and expansion ambitions could quietly accelerate or stall.

Curious To Explore Stronger Alternatives?
Fresh ideas move first. By the time a breakout is flying, the ideal entry can be gone. Scan under the radar for now, act now.
- Spot cash rich balance sheets before momentum headlines hit by running the list of solid balance sheet and fundamentals (7 results) while it still focuses on companies most investors have not caught yet.
- Track income focused opportunities with hefty yields that could steady a portfolio as prices swing by using the curated 3 dividend fortresses before demand crowds them.
- Ride structural demand for critical metals by reviewing the hand picked 16 top copper producer stocks while interest is still building rather than chasing after prices start jumping.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com