
CGN Power (SEHK:1816) Could Be 14% Undervalued After Its Operating Update
CGN Power operating update draws fresh investor attention
CGN Power (SEHK:1816) has released operating figures for January to September 2026, reporting total nuclear power generation of about 189,697.73 GWh and on-grid output of roughly 176,748.88 GWh.
Recent trading reflects that operational backdrop. The share price is now HK$3.31, with a 30-day share price return of 12.58% and a 90-day gain of 14.93%. Total shareholder return sits at 7.32% over one year and 94.50% across three years, suggesting momentum that has built over time rather than appearing overnight.
Scan 16 nuclear energy infrastructure stocks to find other utilities that, like CGN Power, are already reporting substantial power generation and attracting renewed interest from investors focused on nuclear infrastructure.
CGN Power now trades at a discount to both analyst targets and one intrinsic value estimate after a strong run. Is that a genuine margin of safety, or is the market pricing in real risks?
Price-to-earnings of 14.3x for CGN Power: Is it justified?
CGN Power looks expensive on headline metrics, with a P/E of 14.3x compared with both its immediate peer group and the broader Asian renewable energy sector.
The P/E ratio compares the current share price with earnings per share, so a higher figure often signals that the market is willing to pay more for each unit of profit. For a nuclear operator like CGN Power, that can reflect expectations around long asset lives and relatively predictable output, rather than rapid expansion.
Here, the valuation premium is clear. The stock trades above the Asian renewable energy industry average P/E of 13.7x, and well above the peer average of 9.7x. Relative to an estimated fair P/E of 11.4x, the current multiple also appears higher, which indicates a level the market could eventually move toward if sentiment or earnings do not keep pace.
Explore the SWS fair ratio for CGN Power.
Result: Price-to-earnings of 14.3x (OVERVALUED)
Still, CGN Power faces real pressure points, including sector-specific safety and regulatory scrutiny, along with concentrated revenue exposure to China, which could reshape investor sentiment.
Find out about the key risks to this CGN Power narrative.
Another view on CGN Power valuation
The earlier P/E discussion presents CGN Power as expensive, yet the SWS DCF model suggests the opposite. On that cash flow view, the stock at HK$3.31 is about 14.1% below an estimated value of HK$3.85. This raises the question of whether sentiment is too cautious or those cash flow assumptions are generous.
Look into how the SWS DCF model arrives at its fair value.
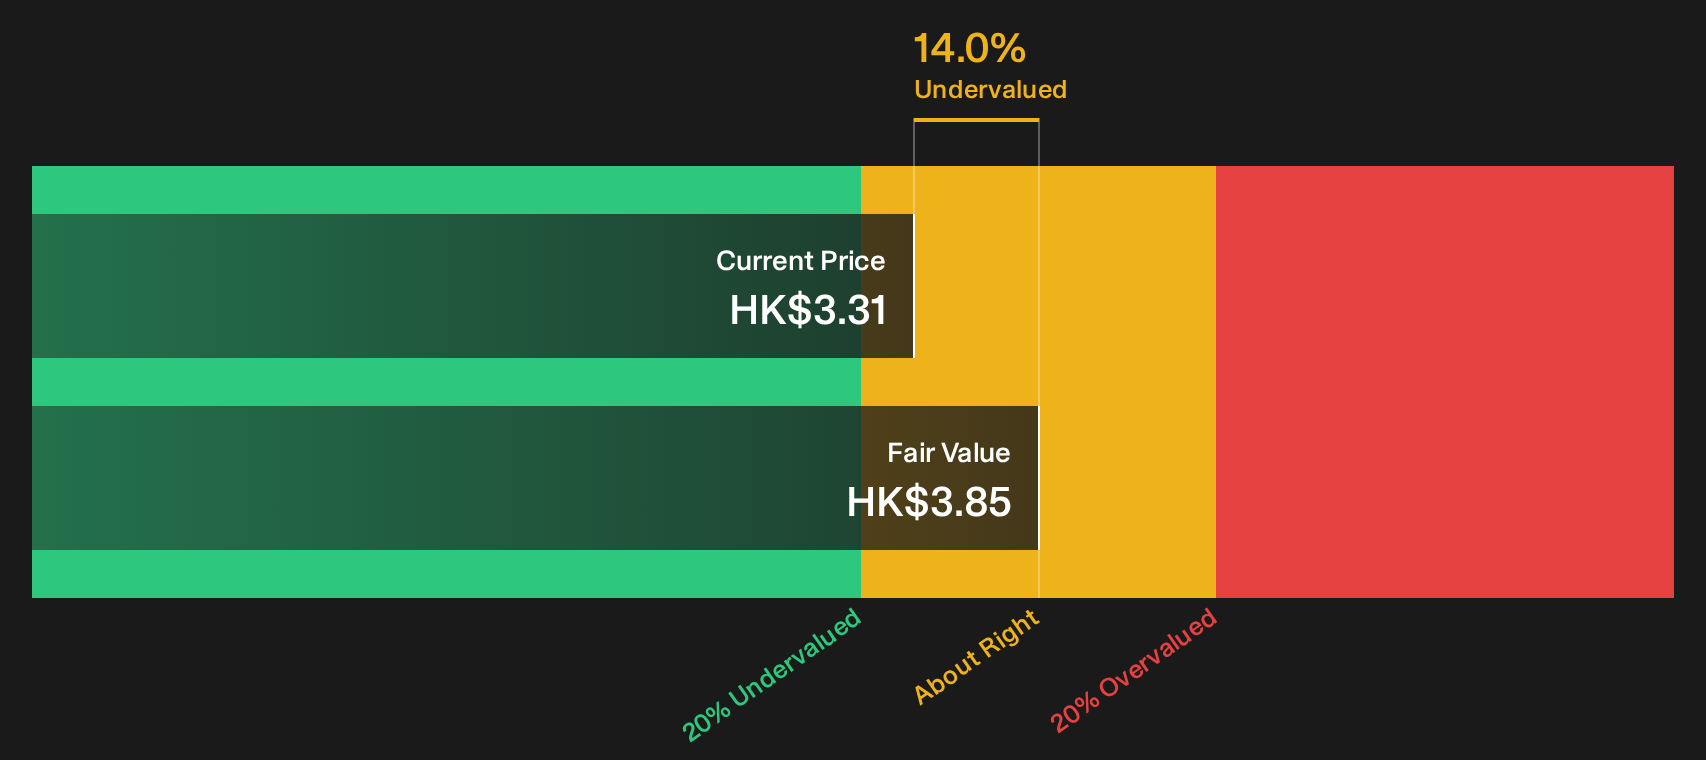
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out CGN Power for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 196 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around CGN Power's valuation can feel confusing. If this update has raised more questions than answers, act promptly and base your own view on the underlying data, including the balance of 3 key rewards and 1 important warning sign.
Looking for more CGN Power style investment ideas?
Do not stop with a single nuclear utility when the wider market is full of other potential opportunities that could sharpen your watchlist and broaden your conviction.
- Target resilient balance sheets by reviewing the list of solid balance sheet and fundamentals (207 results) and see which companies pair financial strength with room for investor interest.
- Hunt for quality at a discount through the 196 high quality undervalued stocks and compare those valuations with what you see in CGN Power today.
- Stack potential income streams by assessing the 225 dividend fortresses and avoid missing stocks that might complement CGN Power in a long term portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com