
What Kajima (TSE:1812)'s Contract Ban Means For Shareholders
- Kajima Corporation disclosed that a guilty verdict for violating Japan's Antimonopoly Act over the Chuo Shinkansen project is now final, leading to a nationwide suspension of new private sector civil engineering contracts for 120 days from November 7, 2026 to March 6, 2027.
- The 4 month business suspension directly targets Kajima's ability to win fresh private civil engineering work. This could reshape project pipelines, resource allocation and near term cost efficiency across the construction portfolio.
- The focus now turns to how Kajima's investment narrative absorbs a 120 day halt on new private civil engineering contracts nationwide.
Stress test your construction exposure by comparing Kajima against a curated group of infrastructure contractors with resilient finances in our list of solid balance sheet and fundamentals (23 results).
What Is Kajima's Investment Narrative?
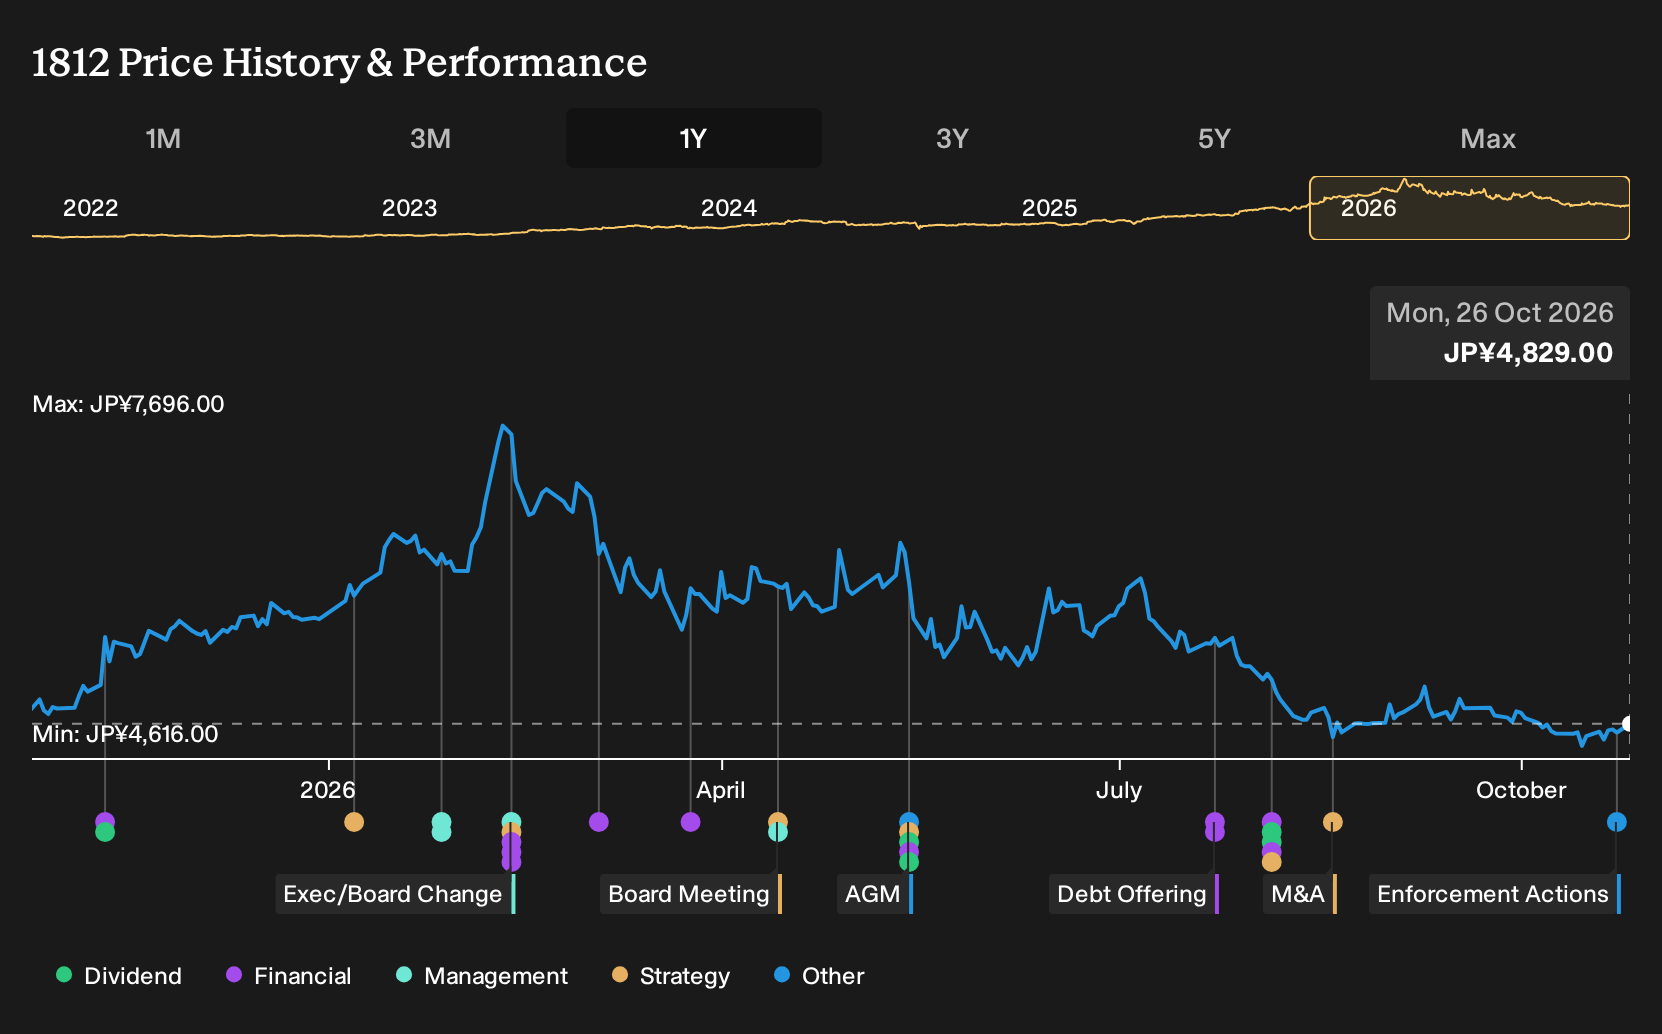
Kajima appeals to investors who want exposure to large, complex infrastructure and building projects where execution quality and technical depth matter more than fast headline growth. Civil engineering, building construction and real estate linked activities together generate well over ¥1b of annual revenue, with earnings that have grown 12.4% per year over five years and 34.7% over the past year. The short term investment case leans on that earnings momentum, high quality profit metrics and a valuation that screens as good value on P/E and discounted cash flow measures, even after a share price that is down almost 20% year to date.
The business suspension changes the near term story. A 120 day halt on new private civil engineering contracts restricts one leg of Kajima's order intake just as investors had been leaning on 6.6% forecast earnings growth and 3.7% expected revenue growth. Ongoing work, public sector demand and overseas operations remain in play, yet the pause may affect project mix, fixed cost absorption and how comfortably free cash flow covers a 3.02% dividend. The stock has already lagged the broader Japanese market over one year, so sentiment was fragile before any regulatory penalty entered the picture.
That said, there is a less visible concern that could matter far more once you look past the 120 day suspension and focus on ...
There's only one way to know the right time to buy, sell or hold Kajima. Head to Simply Wall St's company report for the latest analysis of Kajima's Fair Value.
Exploring Other Perspectives
Across 2 fair value estimates from the Simply Wall St Community, Kajima's projected worth stretches from ¥7,005.56 to ¥22,585.93 per share, a huge gap that signals very different conviction levels. Those views were set before the Antimonopoly Act penalty, so use them as a starting point and compare how your own expectations differ.
Explore another Kajima fair value estimate, including one that suggests it could be worth just ¥7006!
Decide For Yourself
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Kajima research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Kajima. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Kajima's overall financial health at a glance.
Looking For More Ideas Beyond Kajima?
Once you have formed a view on Kajima, it can help to widen the lens and compare it with other companies that match your preferred balance of quality, income and risk. The Simply Wall St Screener lets you do exactly that in a structured way.
- If capital protection comes first for you, start with a universe of sturdier balance sheets and robust fundamentals using our list of solid balance sheet and fundamentals (23 results).
- If value is your main filter, focus on opportunities that combine quality fundamentals with potentially attractive pricing by reviewing our 16 high quality undervalued stocks.
- If reliable income matters most, narrow the field to companies with higher yields and stronger dividend profiles through our 29 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com