
Did Merger Synergy Targets Just Shift JBT Marel's (JBTM) Investment Narrative?
- JBT Marel is working toward merger synergies, with management aiming for about US$150 million of run rate cost savings by the end of 2027, plus footprint optimization benefits by 2028 to support higher net margins and an adjusted EBITDA margin goal of 20%.
- Investors are increasingly focused on whether JBT Marel can translate these planned efficiency gains into more reliable execution after past guidance issues and additional tariff related costs that affect margins.
- We now examine how JBT Marel's investment narrative may be reshaped by execution on merger synergies and margin improvement plans.
Compare JBT Marel's situation with other potential value opportunities and scan a curated 28 high quality undervalued stocks that may also be working through margin and execution reset stories.
JBT Marel Investment Narrative Recap
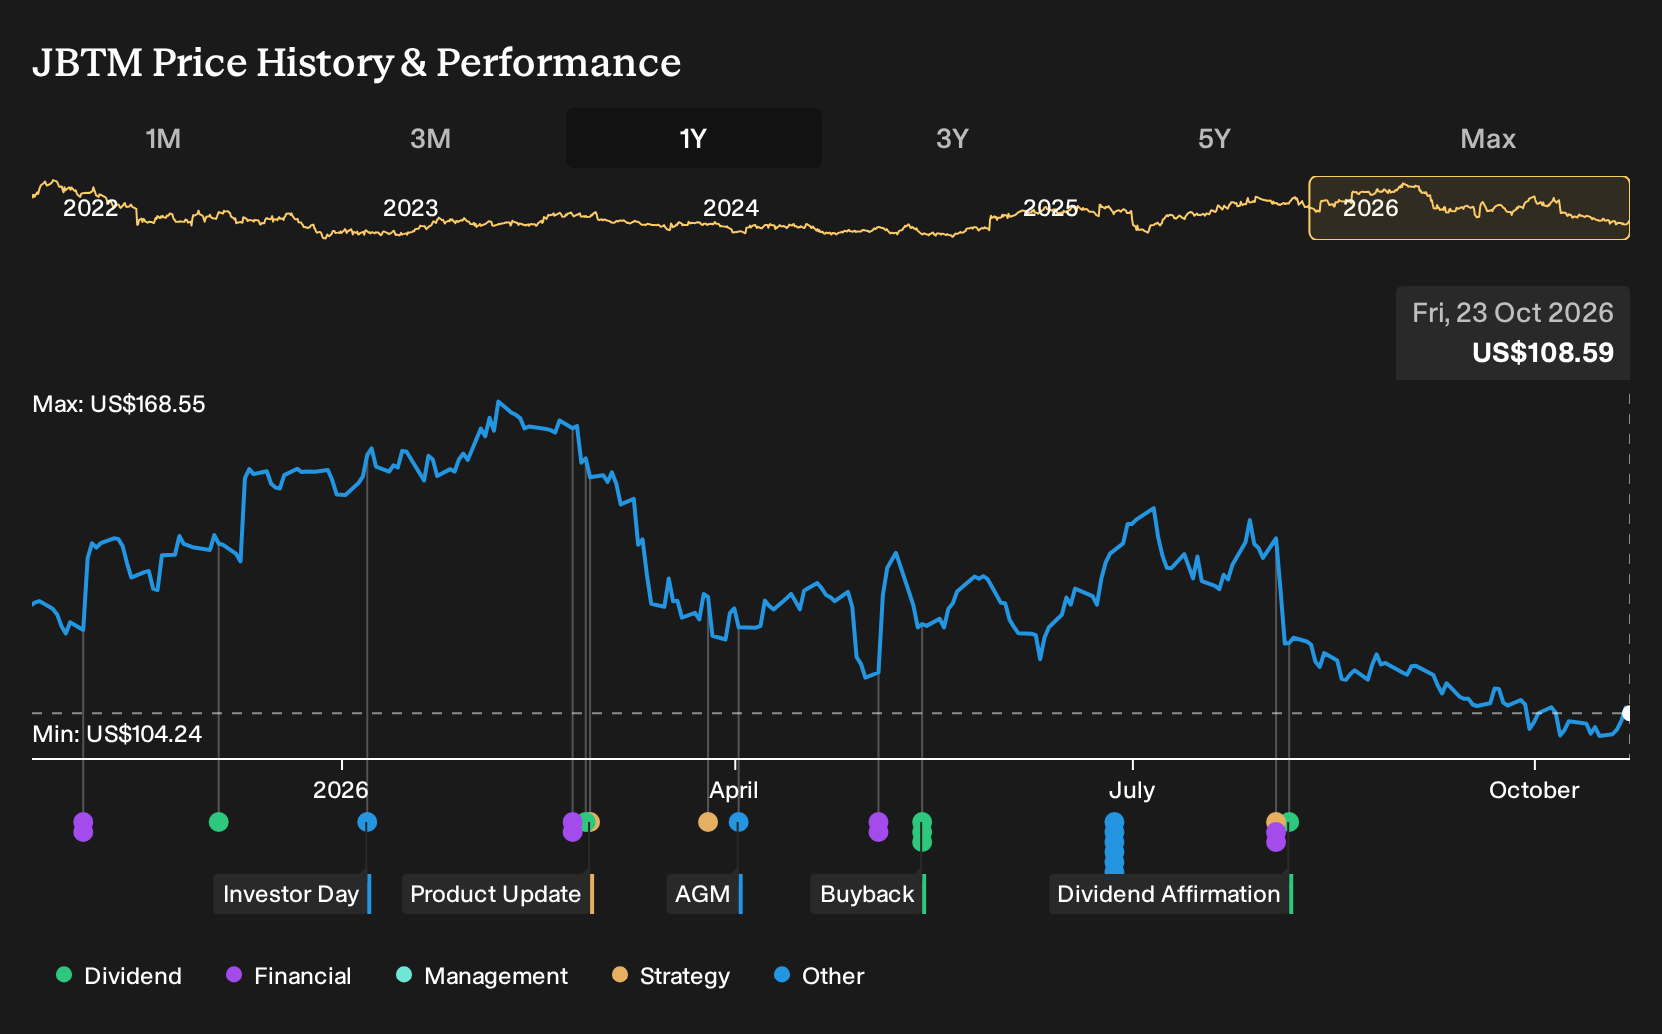
To own JBT Marel, you need to believe that the merger-driven cost program, footprint reshaping, and push into higher margin aftermarket and software can offset tariff headwinds and prior execution stumbles. The sharp share price fall this year and the recent cut in an external target price both keep attention squarely on near term delivery rather than on longer term narratives.
The key short term catalyst is whether management can show clear progress on margins and reliable guidance after past misses and one off items. The biggest risk remains further operational missteps, especially if tariff costs or problem projects again cloud earnings quality and delay the planned margin reset.
The recent revision of an external JBT Marel target price to US$100 sits against this operational backdrop rather than changing it. What matters more for you is whether profit quality, tariff mitigation, and integration synergies track toward the stated 20% adjusted EBITDA margin ambition over the next few years.
With the stock on about 29x earnings, above the US Machinery industry average but below its peer group, the announcement effectively reinforces that the burden of proof lies with execution. Clear evidence on order conversion, cost savings flowing through to net margins, and fewer surprises around one off charges will likely dictate how powerful any future rerating catalyst can be.
Analysts expect JBT Marel to reach about US$4.4b of revenue and US$581.5m of earnings by 2029. This implies forecast revenue expansion of 4.2% per year and an earnings increase of roughly US$388m from current earnings of about US$193.3m.
Uncover why JBT Marel's fair value indicates a 54% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Pessimistic analysts focus on a different risk for JBT Marel. They worry that governance questions around the Prevenio impairment and adjusted earnings treatment could matter more than cost savings. Before this target cut, the most bullish analysts were still assuming US$4.4b of revenue and US$685.6m of earnings by 2029. Those views all pre date the latest news, so treat this as a live debate and explore several angles before leaning toward either camp.
Explore 2 other JBT Marel fair value estimates, including one that suggests as much as 147% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your JBT Marel research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for JBT Marel. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate JBT Marel's overall financial health at a glance.
Looking for more investment ideas beyond JBT Marel?
If the JBT Marel story has you thinking about where else margin repair, balance sheet strength, or income potential might matter, it can help to widen the lens and compare it with other listed businesses using a structured stock screener.
- For investors hunting for resilient businesses where risk controls and fundamentals matter as much as upside potential, start with a curated 30 resilient stocks with low risk scores that keeps a tight focus on financial resilience and lower volatility profiles.
- If balance sheet strength is your non negotiable and you want companies with room to absorb shocks or fund growth internally, filter for candidates using the list of solid balance sheet and fundamentals (24 results) and see which stocks meet that bar today.
- For readers looking to pair income with discipline around payout quality, use the dividend focused 5 dividend fortresses to zero in on higher yielding companies that clear a set of financial health checks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com