
CLP Holdings (SEHK:2) Refreshes Leadership As Renewables Focus Puts Valuation In View
CLP Holdings (SEHK:2) has reshaped its leadership with the appointment of Philip Lawrence Kadoorie as Vice Chairman and the creation of a Renewables Business Committee, which will sharpen board-level attention on clean energy and future expansion.
Recent moves at CLP Holdings come after a year where the share price return has gained 10.16% year to date to HK$77.0. The longer track record looks stronger, with a 1 year total shareholder return of 22.04% and 3 year total shareholder return of 53.25%. This hints that investors have increasingly been willing to pay up for the business as leadership and dividend decisions, including the recently affirmed HK$0.63 third interim payout, shape perceptions of both growth potential and risk.
Scan how CLP Holdings compares with other power and infrastructure players by jumping into our hand picked 42 power grid technology and infrastructure stocks for potential beneficiaries of long term energy transition themes.
CLP Holdings now pairs refreshed leadership with a reaffirmed HK$0.63 interim dividend and a share price at HK$77. The business appears solid. The open question is whether investors are paying a fair price today.
Price-to-Earnings of 17.9x: Is it justified for CLP Holdings?
CLP Holdings is trading on a P/E of 17.9x, which sits well above several reference points and raises clear questions about how much investors are willing to pay for each dollar of current earnings at the HK$77 share price.
The P/E ratio compares the share price to earnings per share and is a simple way to see how highly the market values a utility's profit stream. For a regulated electricity provider with modest forecast earnings growth of 2.7% per year and revenue growth of 0.9% per year, a rich multiple can mean the market is baking in a lot of confidence that earnings will stay steady and that the dividend will remain attractive.
That confidence comes at a clear premium. CLP Holdings trades on a P/E of 17.9x compared to an Asian electric utilities average of 12.9x and a peer average of 11.5x. It also looks expensive relative to an estimated fair P/E of 9.4x. This is a level the valuation model suggests the market could move toward if investors start to question paying such a high price for low double digit Return on Equity of 9.9% and earnings that are expected to grow but not significantly.
Explore the SWS fair ratio for CLP Holdings.
Result: Price-to-Earnings of 17.9x (OVERVALUED)
Still, any wobble in regulated earnings or a sharp reset in sector valuations could quickly challenge how comfortably CLP Holdings carries a 17.9x P/E.
Find out about the key risks to this CLP Holdings narrative.
Another view on CLP Holdings using cash flows
The SWS DCF model points in the same direction as the rich 17.9x P/E. On this view, CLP Holdings at HK$77 trades above an estimated future cash flow value of HK$73.63, which suggests less of a safety cushion if expectations around earnings or dividends ever soften.
Look into how the SWS DCF model arrives at its fair value.
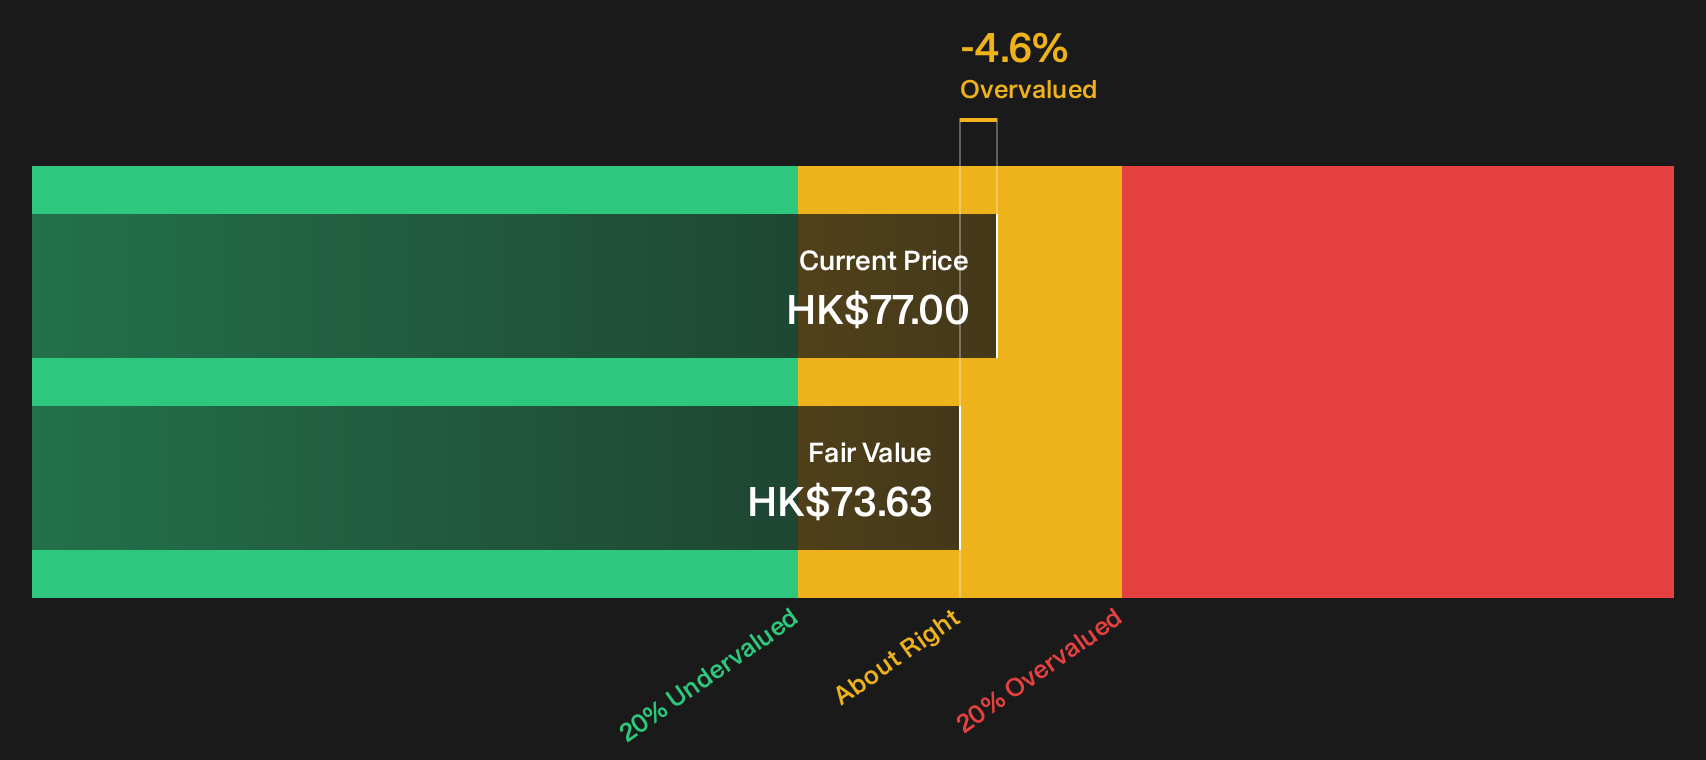
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out CLP Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 194 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the tone so far feels cautious rather than euphoric, that is intentional, and it is worth pressing into the numbers yourself before sentiment shifts. For a sharper view on what could go wrong, review the 2 important warning signs.
Looking for more CLP Holdings sized investment ideas?
Do not stop your research with CLP Holdings alone. Use the Simply Wall Street Screener to spot other opportunities that fit your style before the crowd gets there.
- Target steadier compounding by scanning a 223 resilient stocks with low risk scores that may be more resilient when markets turn choppy.
- Hunt for quality at a discount by reviewing a 610 high quality undiscovered gems that larger investors might not be watching yet.
- Focus on balance sheet strength by checking a list of solid balance sheet and fundamentals (207 results) that can support reinvestment or income through different market conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com