
3 British Undervalued Stocks With Up To 49% Fair Value Upside
European gas prices have hit a four year high and the UK faces some of the steepest energy costs in Europe this winter. That kind of pressure often pushes investors toward profitable British businesses with strong cash flows and resilient balance sheets that are not priced for perfection. This article walks through three high quality undervalued UK stocks from our screener that fit that brief.
The three stocks below are a small sample from this high quality undervalued group. The full screen surfaced 6 more UK listed businesses with similarly compelling stories that are not covered in this article.
If you want to identify and analyze the rest of these potential breakout candidates with strong cash flows and sturdy balance sheets, head straight into the High Quality Undervalued Stocks screener
Airtel Mobile Commerce (LSE:AMC)
Overview: Airtel Mobile Commerce runs a digital finance platform offering mobile payments, wallets, transfers, loans, savings, insurance and a global virtual card. The business generates scalable, cash-flow driven services that align directly with the High Quality Undervalued Stocks theme.
Operations: Airtel Mobile Commerce reports around $2 million in data processing revenue, currently recorded entirely in the Netherlands.
Market Cap: £4.8b
Airtel Mobile Commerce combines a mobile money engine linked to improving earnings, strong ROE metrics and a valuation that screens as discounted. This matches the brief for high quality cash flows with potential for a breakout re-rating, although much depends on how one unresolved funding pressure ultimately interacts with that earnings power.
That funding overhang is the hinge point, so it is worth scanning the 3 key rewards and 2 important warning signs (1 is major!) to see what might be masking Airtel Mobile Commerce’s potential re-rating.
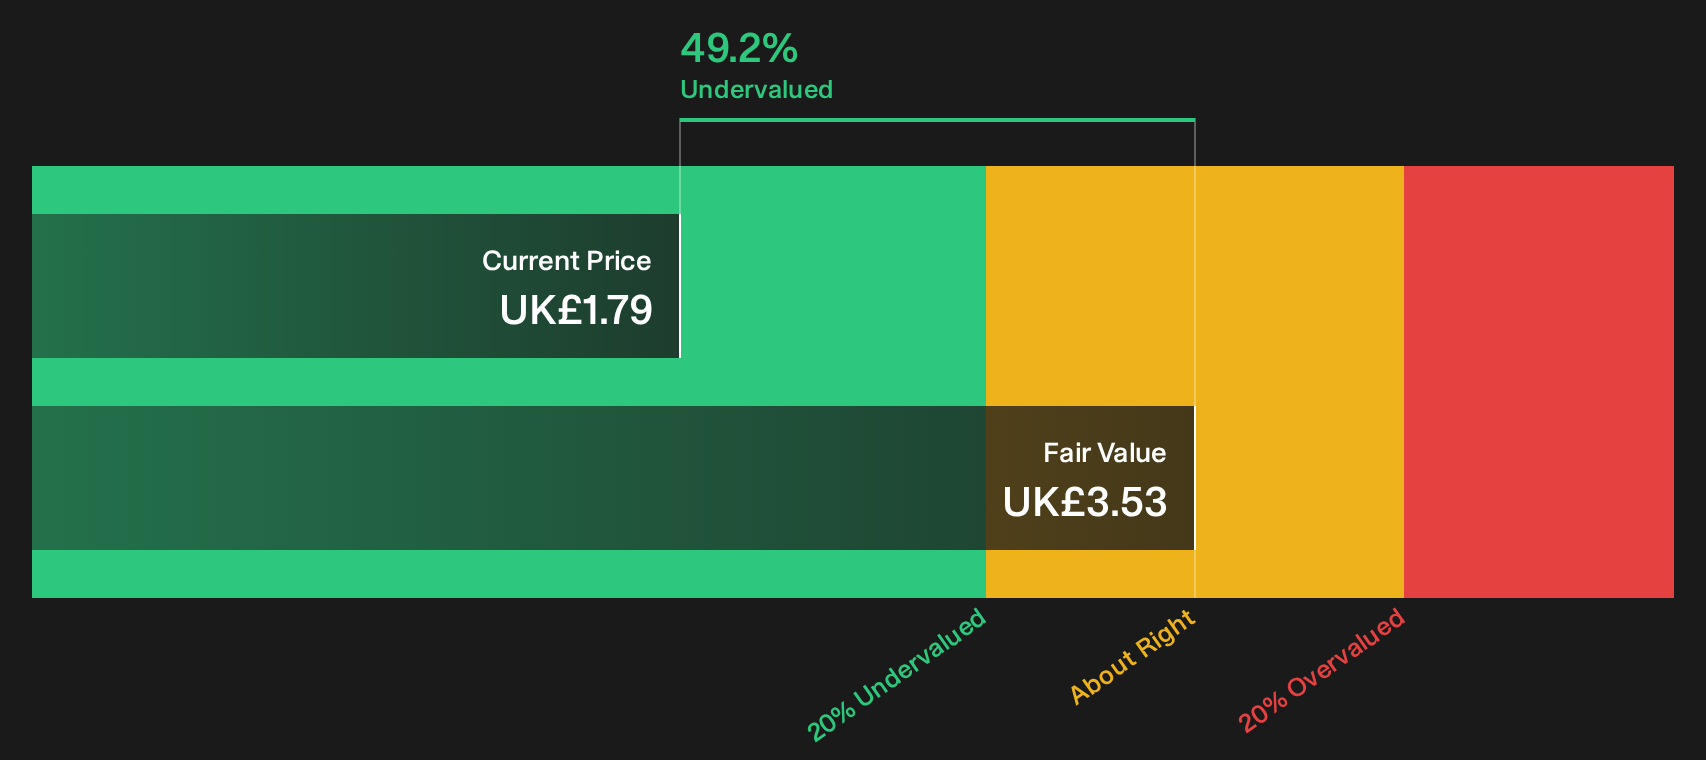
BAE Systems (LSE:BA.)
Overview: BAE Systems supplies defense, aerospace and security equipment and services to government and national security customers across the US, UK and allied markets.
Operations: Revenue leans on Electronic Systems (£7.8b), Air (£7.7b) and Platforms & Services (£5.3b), supported by sizeable UK and US contracts.
Market Cap: £54.6b
BAE Systems fits the High Quality Undervalued Stocks theme through long duration defense programs that generate recurring cash flows and support a solid balance sheet.
"The company's order backlog reached £84b with total backlog plus incumbent program positions of around £260b, which equals about 8x annual sales and indicates multi year support for revenue and earnings."
The key factor for that backlog is how effectively new capacity and digital projects convert heavy demand into sustained margins and cash.
Turning that backlog into lasting value starts with understanding how management plans to balance pricing power, capital intensity and future contracts in the full narrative for BAE Systems, which unpacks where momentum may be building fastest.

Smith & Nephew (LSE:SN.)
Overview: Smith & Nephew makes orthopaedic implants, sports medicine tools and advanced wound care products used in surgeries and long term treatments worldwide.
Operations: Smith & Nephew generates about $2.5b from Orthopaedics, $2.0b from Sports Medicine & ENT, and $1.8b from Advanced Wound Management.
Market Cap: £9.7b
For a High Quality Undervalued Stocks theme built around strong cash flows and balance sheet strength, Smith & Nephew brings an orthopaedics engine that throws off repeat implant and consumable demand, supported by broader medical devices that help smooth earnings through different hospital spending cycles.
"Acceleration in new product innovation, such as expanded robotic-assisted surgery (CORI, CORIOGRAPH), new implants (CATALYSTEM Hip, TRIGEN MAX Tibia Nailing), and significantly increased contributions from recent product launches (75% of H1 growth from products <5 years old), positions the company to capture greater market share and sustain higher long-term revenue growth as global demand for advanced orthopaedic and minimally invasive solutions rises."
What investors really need to watch now is how one quiet shift in how that cash is funded shapes margins over the next leg of growth.
If that funding shift is the real swing factor, read the full narrative for Smith & Nephew to see how accelerating product traction and capital choices could reset the Smith & Nephew story.

Seeking Alternatives Before The Crowd?
Fresh stock ideas move quickly. Breakout stories gain momentum, weaker ones start dropping and the best opportunities often get caught under the radar for now. If you want a real first-mover edge, act now.
- Spot early-turn opportunities in smaller companies before momentum traders notice by scanning the 15 elite penny stocks with strong financials that filter for stronger financial profiles and cleaner balance sheets.
- Ride structural technology trends by reviewing the 55 AI infrastructure stocks that focuses on businesses supplying the hardware backbone and services behind fast-growing AI workloads.
- Secure income candidates that aim to keep paying when conditions get rough by checking the 5 dividend fortresses built around higher yield and sturdier financial footing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com