
ID Logistics Group (ENXTPA:IDL) Reports Higher Revenue, Is The Valuation Too Rich?
Revenue announcement puts ID Logistics Group in focus
ID Logistics Group (ENXTPA:IDL) drew fresh attention after reporting third quarter 2026 revenue of €1,177.9 million and nine month sales of €3,262.5 million, both above the prior year periods.
The fresh trading update lands after a volatile spell for ID Logistics Group, with the stock rising 11.86% on a 1 month share price return but still down 10.04% on a year to date share price basis, while the 3 year total shareholder return of 42.07% points to stronger, longer run momentum.
Scan beyond ID Logistics Group and see how other contract logistics and transport players stack up on revenue trends and balance sheet strength using our curated list of solid balance sheet and fundamentals (207 results).
Bulls point to ID Logistics Group’s recent revenue update and multi year shareholder gains. Bears highlight the year to date share price decline and valuation risks. Which side does the current pricing really support?
Price-to-earnings of 35.4x for ID Logistics Group: Is it justified?
Valuation is where the ID Logistics Group story becomes more demanding, because the stock carries a P/E of 35.4x even as it trades at €363.
The P/E ratio compares what investors are currently willing to pay for each €1 of earnings. For a contract logistics specialist like ID Logistics Group, that benchmark gives a quick sense of how strongly the market is pricing in future profit delivery and the resilience of its model across sectors such as FMCG, e-commerce and healthcare.
IDL is described as expensive relative to several anchors. The current P/E of 35.4x is more than double the estimated fair P/E of 16.2x, and also far above both the peer average of 15.2x and the global logistics industry average of 14.5x. That gap signals that the market is paying a significant premium versus what the SWS fair ratio implies the valuation could move toward if sentiment or expectations normalise.
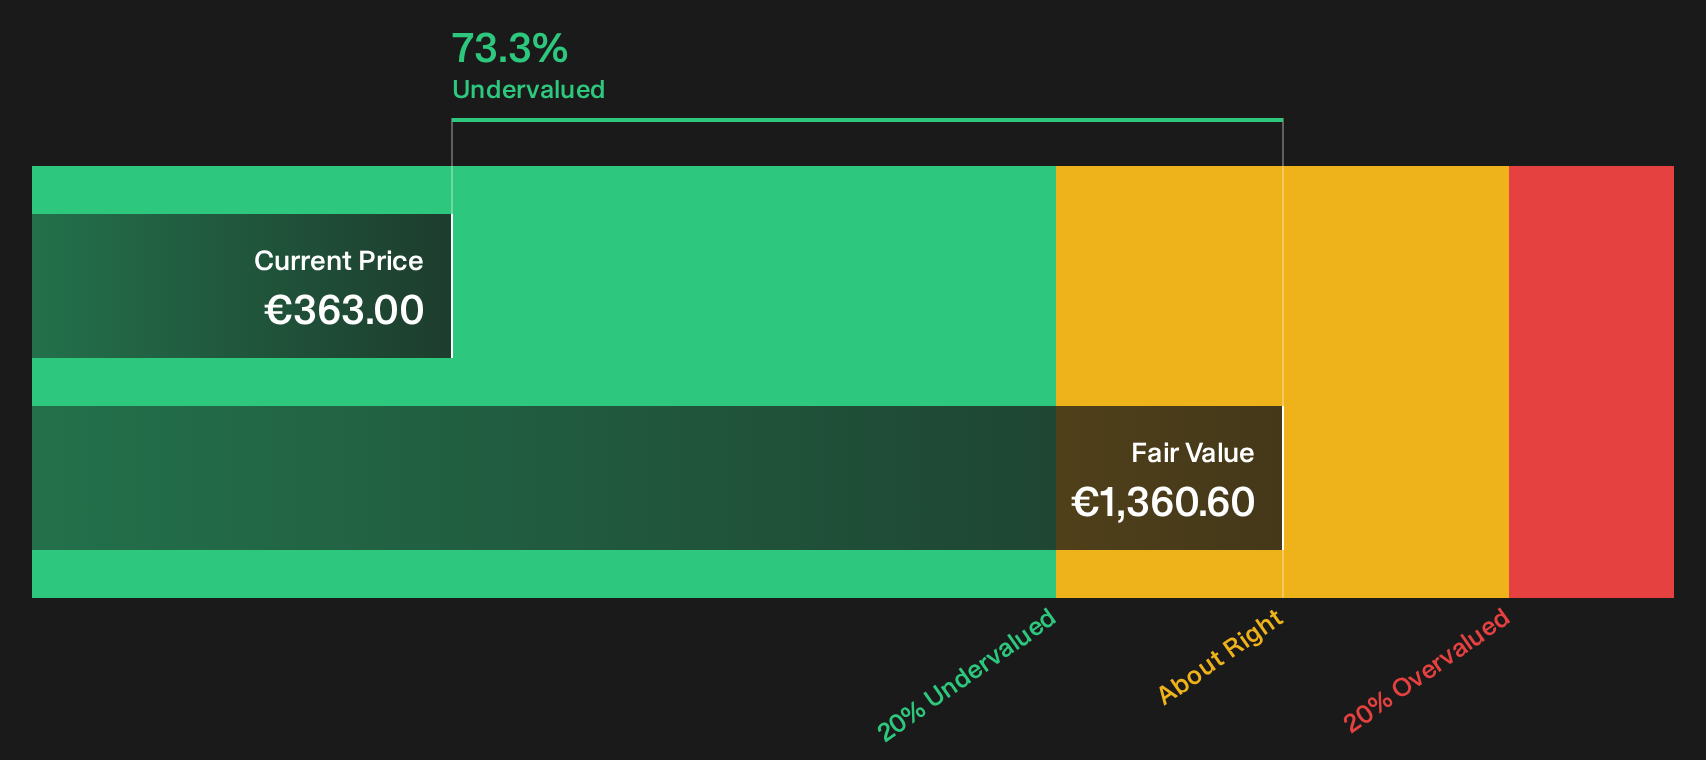
Against that backdrop, the stock is also flagged as trading 73.3% below one estimate of fair value based on future cash flows, which points to a sharp difference between what the P/E suggests and what a discounted cash flow output implies. Combined with expectations for earnings to grow 20.06% per year and revenue to advance 11.1% per year, the current multiple looks like a bet that this growth profile and earnings quality can support a higher valuation than sector norms for an extended period.
Explore the SWS fair ratio for ID Logistics Group.
Result: Price-to-earnings of 35.4x (OVERVALUED)
Still, the rich 35.4x P/E for ID Logistics Group sits against a year to date share price decline, and there is potential for disappointment if growth assumptions or cash flow forecasts are revised down.
Find out about the key risks to this ID Logistics Group narrative.
Another view of ID Logistics Group’s value
The P/E paints ID Logistics Group as expensive, yet the SWS DCF model points the other way. On that cash flow view, the shares at €363 trade around 73.3% below an estimated future value of €1,360.6, which frames the stock as materially undervalued instead.
That wide gap between an apparently stretched 35.4x earnings multiple and a supportive cash flow estimate leaves you with a practical question: Which signal do you trust more when both are staring at the same business?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out ID Logistics Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 194 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on ID Logistics Group is mixed, with rich valuation signals set against cash flow support. It may be useful to review the numbers directly and decide quickly. To see what is driving the current optimism, check the 4 key rewards.
Looking for more investment ideas beyond ID Logistics Group?
If ID Logistics Group has your attention, do not stop here. Fresh ideas can shift your portfolio’s risk, income and growth profile much more than you think.
- Target resilient performers by scanning companies flagged as having lower risk profiles and sturdier fundamentals through the 223 resilient stocks with low risk scores.
- Hunt for stronger value by reviewing the 194 high quality undervalued stocks that combine quality fundamentals with pricing that may not fully reflect their financial position.
- Build more dependable income by checking the 225 dividend fortresses that focus on higher yielding payouts supported by underlying financial metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com