
Will New Community Openings Change Toll Brothers Stock Narrative
- Toll Brothers has recently announced a flurry of new and planned luxury communities across the U.S., spanning price points from the upper $400,000s to around $1 million and above, with offerings from condominiums and townhomes to large single-family estates.
- This broad mix of higher price point projects, many in affluent school districts and amenity-rich master plans, signals a push to deepen Toll Brothers exposure to luxury move-up buyers while expanding its geographic footprint.
- The focus now turns to how Toll Brothers expanding community pipeline, including new luxury projects in markets such as Florida and Washington, could influence the existing investment narrative.
Scan Toll Brothers alongside similar luxury-focused builders and higher price point housing plays using our curated list of solid balance sheet and fundamentals (24 results) for ideas that match this kind of community expansion story.
Toll Brothers Investment Narrative Recap
To own Toll Brothers, you need to believe its luxury focus and community expansion can support steady volumes and pricing across different markets. The near term hinge is execution on opening and selling through new projects without eroding margins. The latest wave of community launches and future openings mainly reinforces that growth path rather than changing it.
The bigger risk remains softer housing demand or pricing that leaves analysts revenue and margin assumptions looking too optimistic. Recent announcements do not materially change that exposure. They do, however, increase the amount of capital and operational effort tied up in higher price point projects that could be slower to turn if conditions weaken.
Among the recent updates, Watchtower at Browns Point in Northeast Tacoma is one of the clearest links to the existing Toll Brothers thesis. It extends the luxury footprint into a high income West Coast market, adds larger floor plans, and fits the focus on affluent move up households and strong school districts that underpins current margin expectations.
This type of community also leans into key catalysts such as expanding community count and using land light structures and joint ventures, such as those seen at LakePointe, to manage capital intensity. The flip side for investors is execution risk on multi year projects with higher absolute price points, which can amplify any slowdown in orders if housing trends soften from here.
Toll Brothers' current analyst framework points to revenues of US$13.7b and earnings of US$1.6b by 2029. That profile lines up with an 8.4% yearly revenue growth rate and an earnings increase of about US$400m from current earnings of US$1.2b.
Uncover why Toll Brothers' fair value indicates a 22% potential upside to its current price that could narrow quickly.
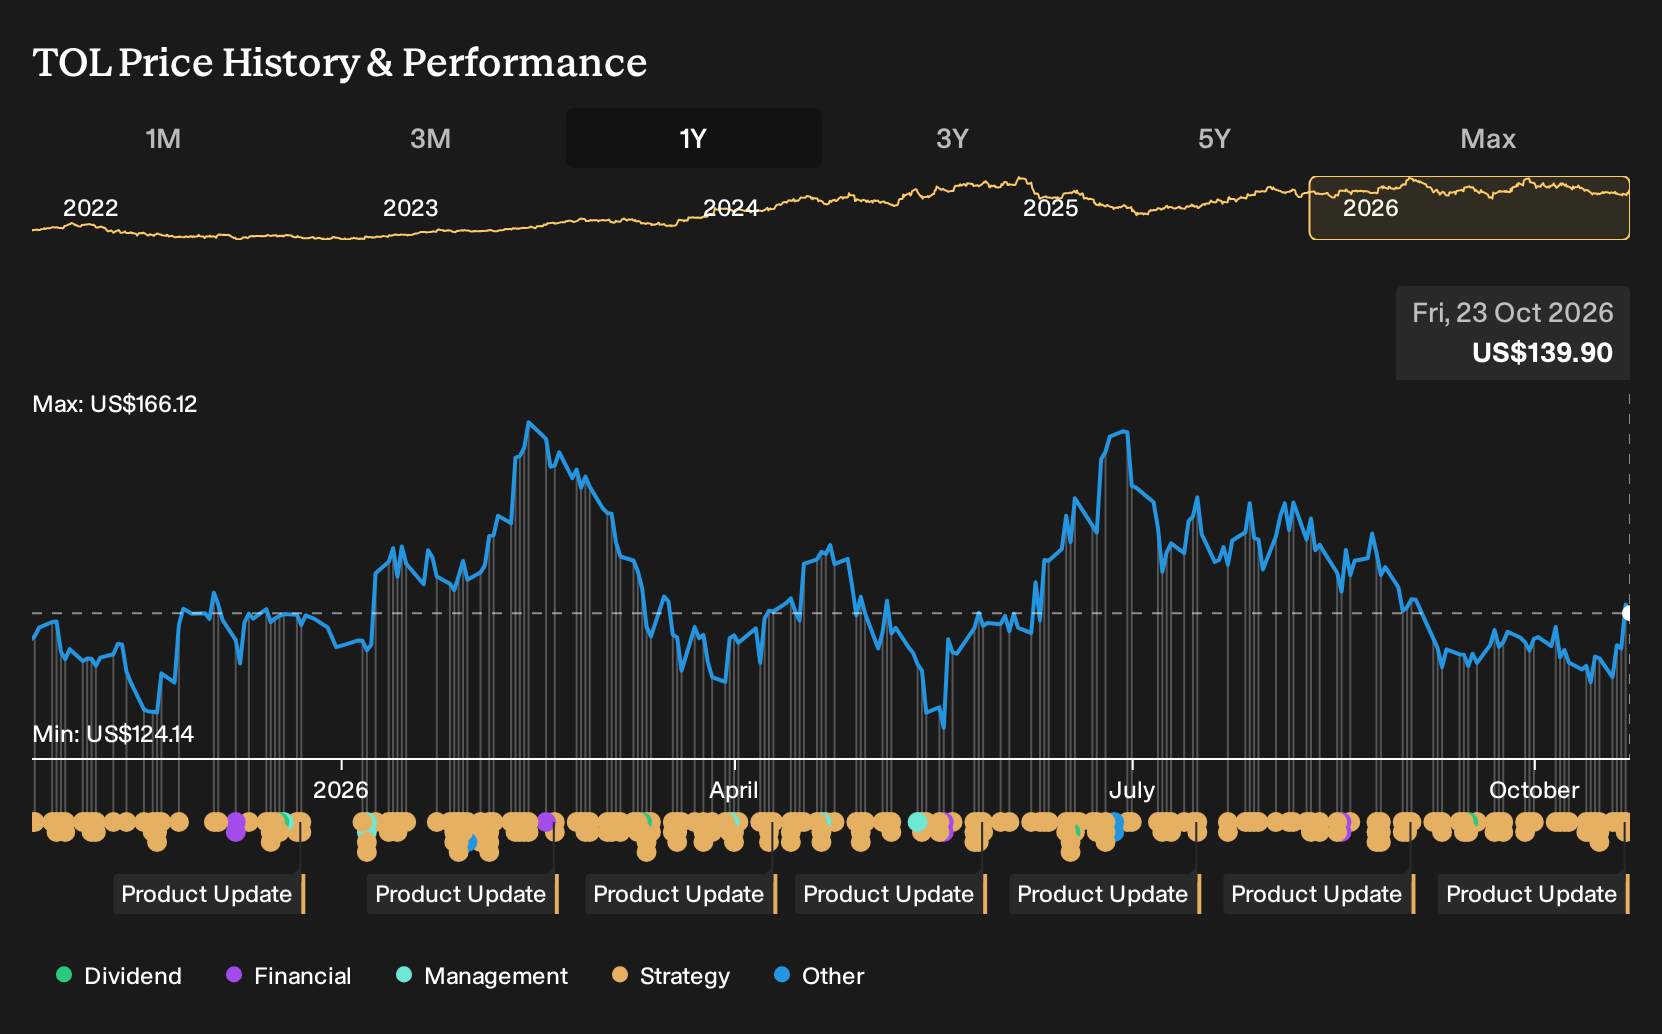
Exploring Other Perspectives
One alternative view leans hard into Toll Brothers expansion risk. The most bullish analysts previously worked off revenue of about US$13.4b and earnings of roughly US$1.6b by 2029, paired with a 13.4x P/E. You can see how dense luxury launches like Station Walk or 280 North might either support that optimism or prompt a rethink.
Explore 5 other Toll Brothers fair value estimates, including one that suggests there may be as much as 80% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Toll Brothers research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Toll Brothers. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Toll Brothers' overall financial health at a glance.
Looking for more Toll Brothers style investment ideas?
If the Toll Brothers story has you thinking about what else might fit a similar profile, it can help to line it up against a broader set of stocks and see how the numbers compare side by side.
The Simply Wall St Screener gives you a structured way to do that, so you can filter for balance sheets, cash flows, dividends, or valuation traits that actually match what you want out of an investment.
- If capital strength is non negotiable for you, start with a list of solid balance sheet and fundamentals (24 results) that emphasizes financial resilience and cleaner balance sheets.
- If value is your priority, scan for companies trading on more modest expectations using our 28 high quality undervalued stocks to spot ideas that align with your return hurdles.
- If you want potential upside without only chasing well known large caps, widen the search with a 21 high quality undiscovered gems that focuses on quality fundamentals away from the usual crowd.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com