
GSK (LSE:GSK) Stock Still Looks Discounted After Its 49% Five Year Run
GSK has ridden a multi year stretch of positive returns and a run of major drug approvals, which raises a straightforward question for you as an investor. Is the current share price at £18.94 adequately backed by the earnings power that these therapies and partnerships can support over time?
- Over the past 5 years, GSK has delivered a 48.8% share price gain, which puts the spotlight firmly on whether that performance lines up with the strength of its underlying earnings.
- Fresh FDA approvals in hepatitis B and rectal cancer, plus new oncology licensing deals and a large scale manufacturing expansion, can reshape how quickly profits grow and how much cash the group needs to reinvest to sustain its pipeline.
- The analysts covering GSK have run their own numbers. See what analysts think GSK's shares could be worth.
The issue now is whether GSK's current valuation is justified by its earnings profile once you line up the share price against what the business is actually generating today.
If you are weighing GSK against other earnings focused opportunities, it can be helpful to compare it to 9 high quality undervalued stocks.
Is GSK a Bargain on Earnings?
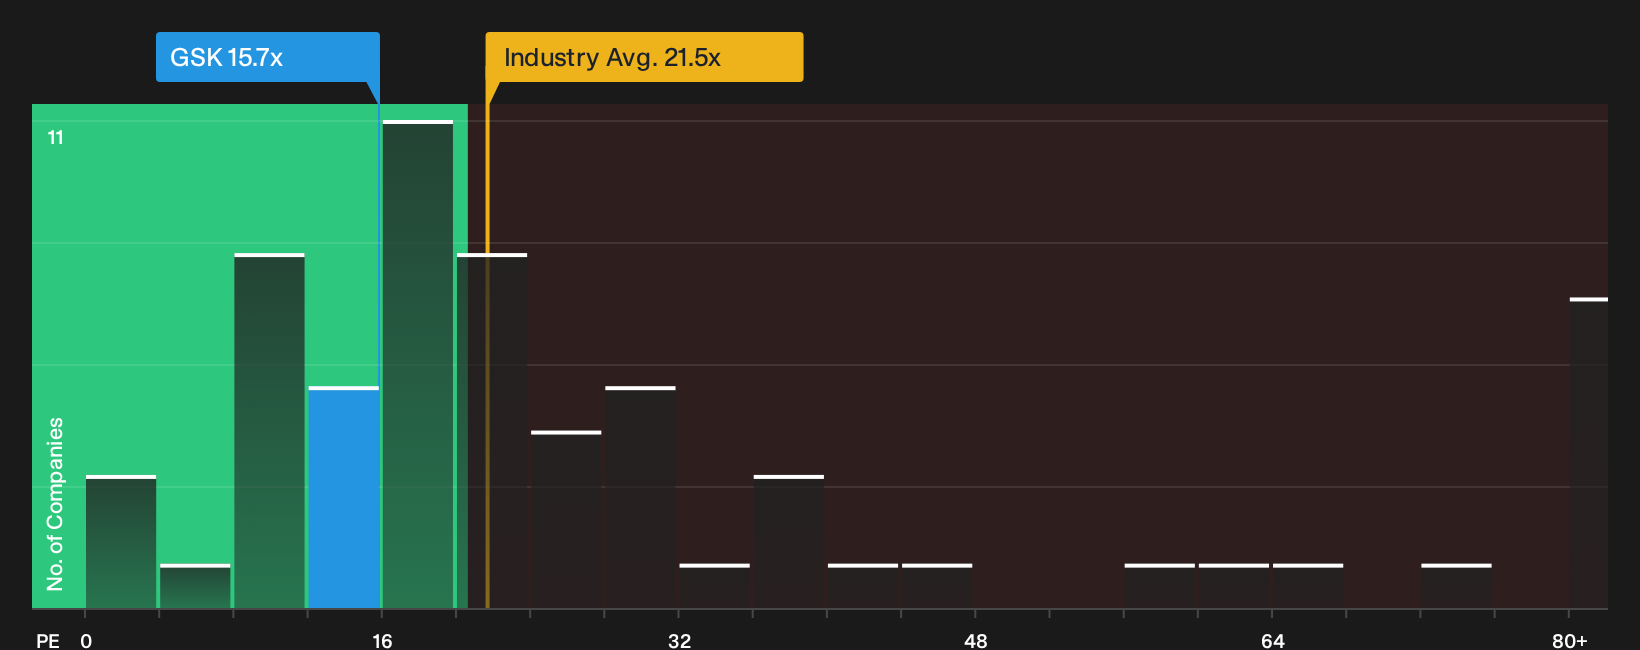
P/E works well for GSK because investors are focused on how its approved therapies convert into bottom line profit. On this lens, GSK trades on a P/E of 15.7x, below the Pharmaceuticals industry average of 20.7x and well under the peer group on roughly 49.7x. The stock also changes hands at a lower level than the tailored fair P/E that takes its size, margins and risk profile into account, which points to GSK looking undervalued on this metric.
Even with the recent lift from FDA approvals for Hibsago and Jemperli, the current earnings multiple still prices GSK at a discount to both its sector and similar large drug makers. That gap suggests the market is placing a cautious label on the pipeline and cash generation story, so you would want to weigh how durable you think the existing franchises and newer therapies are before deciding whether that discount looks justified. Explore the numbers behind GSK's P/E valuation.
The GSK Narrative: What Would Justify Today's Price?
GSK's recent moves on pricing, approvals and partnerships set up a simple next step for you as an investor. Narratives on Simply Wall St's Community page spell out which expectations on future growth, margins and earnings would need to hold for GSK to be worth meaningfully more or less than the current share price. Each one treats fair value as a thesis about how the business might develop that you can watch play out over time.
Bullish and bearish GSK holders are looking at the same pipeline and cost program, yet reach very different conclusions on what the current price reflects.
Bull case: 13% undervalued
"GSK is pushing deeper into long acting HIV injectables, with Cabenuva and Apretude driving a larger share of HIV division growth and backed by data showing Cabenuva superiority to daily oral therapy in high risk and viremic patients…"
Discover why this Narrative puts GSK at 13% undervalued.
Bear case: 30% overvalued
"Although GSK is pushing hard to lift its specialty medicines mix, the 9% decline in General Medicines sales in Q2 and the downgrade to full year guidance indicate structural pressure from aging brands and generic competition that could drag on revenue and dilute the margin uplift expected from higher priced therapies…"
Explore why this Narrative puts GSK at 30% overvalued.
GSK’s valuation still leaves one crucial angle unresolved
Price tags and earnings only tell part of the story for GSK. The people directing capital, setting priorities and rewarding themselves can tilt your risk reward balance far more than any single multiple. See who runs GSK and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com