
What Permanent TSB Group Holders Saw Early
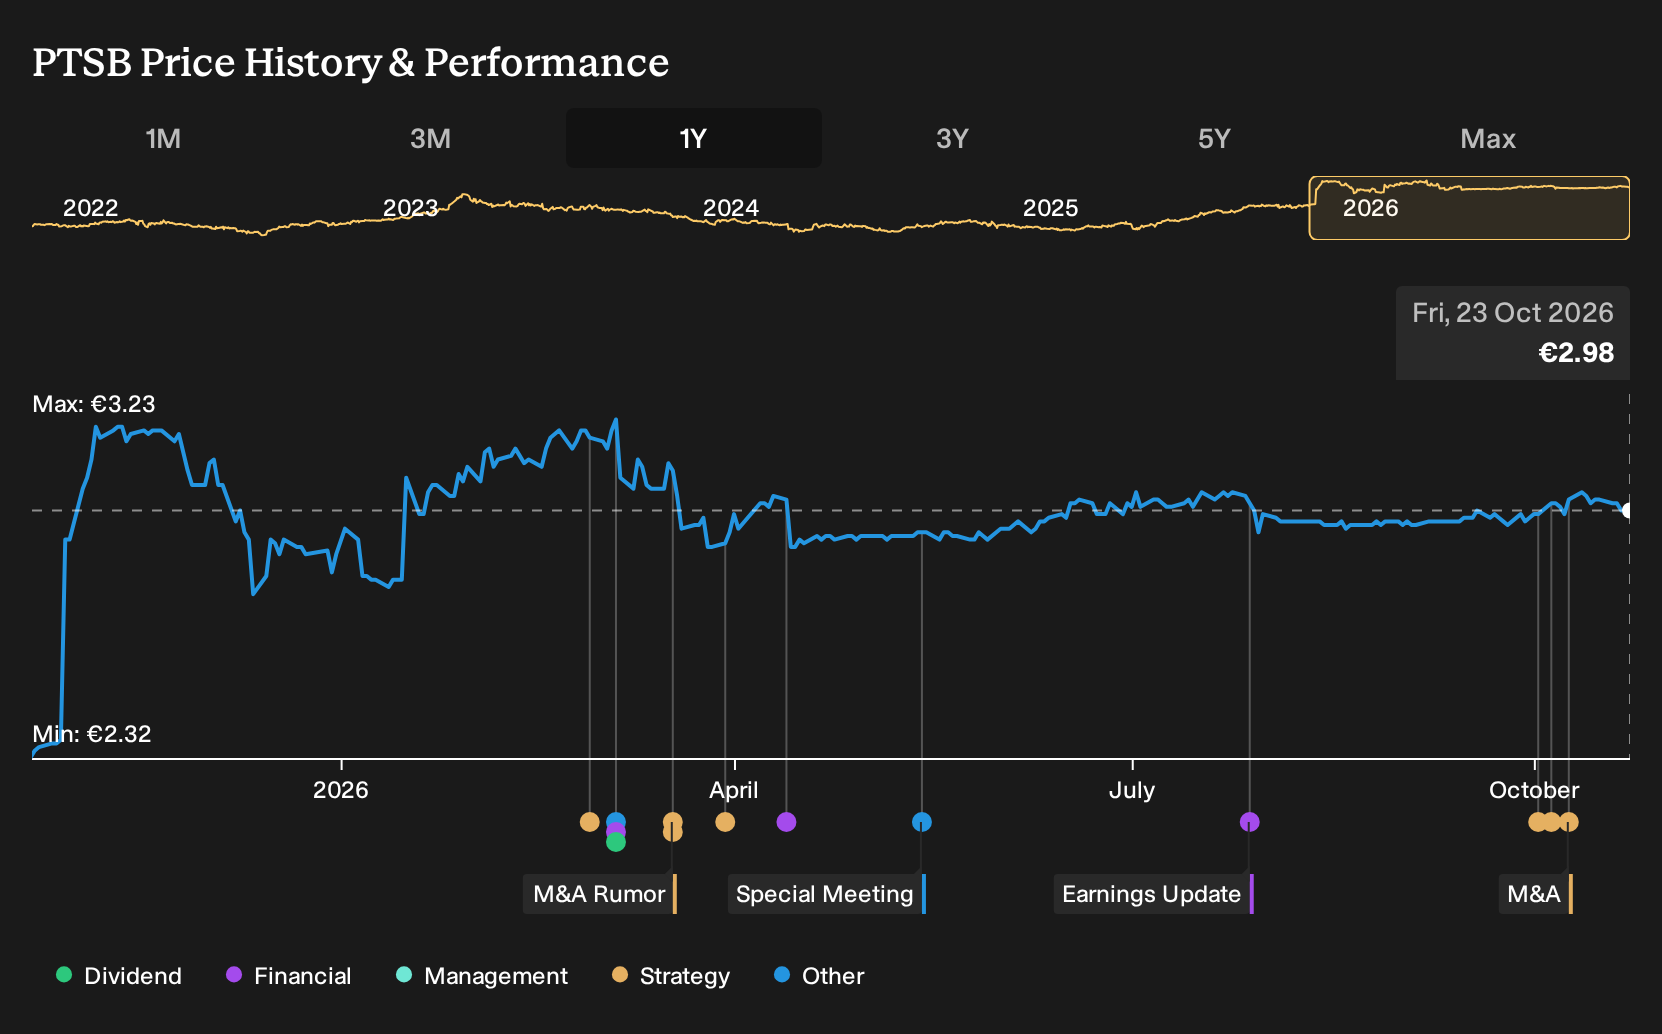
If Permanent TSB Group was on your watchlist rather than in your portfolio, the return may sting. Investors who held Permanent TSB Group over the past year are up 28.1%, including dividends. That kind of move lands just as a cash takeover by BAWAG reshapes the story and merger arbitrage funds crowd the register. The real puzzle is simple. What in the original debate about digital transformation and Irish demographics could have flagged that this mortgage heavy bank might attract a bidder?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
Permanent TSB Group has already moved. See which of 194 high quality undervalued stocks still trade below our estimates.
Two Permanent TSB Stories Investors Had To Weigh
The shares cost €2.32 at the start of the period, and anyone looking at Permanent TSB Group then was really choosing between two very different stories about the same bank.
The bullish narrative pinned a fair value of €3 and leaned on digital transformation and Irish demographics. Supporters focused on assumptions of 6.3% annual revenue growth and profit margins rising from 10.5% to 31.8% by 2028.
The bearish narrative argued for fair value of €1.31 and centered on mortgage overexposure and digital vulnerability. That camp assumed only 3.4% annual revenue growth, with margins reaching 22.3% and persistent pressure from a mortgage-heavy loan book.
What The Evidence Did To The Permanent TSB Group Argument
The clearest new fact is the agreed €1.62b cash offer from BAWAG to acquire Permanent TSB Group, which gave weight to the bullish view that another buyer might value the franchise and Irish footprint highly. At the same time, H1 2026 results showed revenue at €338m and net income at €25m, with net margin at 7.4%. That mix of improving profitability and takeover interest cut both ways for the original debate.
The lesson is simple. When a thesis leans on profitability and capital appeal, you track reported net margin and outside buyers willing to pay cash. Those two signals help you test any future story about rerating potential in another bank long before a formal offer appears.
What Permanent TSB’s Price Already Assumes
Permanent TSB Group now trades at €2.98. The selected Narrative’s Fair Value sits below that level, so in that view buyers today are already paying up for progress on capital efficiency, earnings resilience and the benefits of joining BAWAG.
The key question is what must keep going right for this to hold. A buyer at today’s price would need confidence that capital relief, cost cuts and lending diversification translate into better returns without eroding asset quality.
"Although Permanent TSB Group Holdings has secured approval for new mortgage risk models that cut risk weighted assets and lift capital ratios, the benefit depends on converting that capital into lending at acceptable spreads, and the recent 3 to 4% fall in total operating income as rates eased suggests that redeployment could come with weaker revenue and earnings resilience."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Looking Past Permanent TSB
Permanent TSB has become a merger story. Your next question is where similar debates about digital banking could matter.
Irish borrowers care about simple products and lower fees. So do people in markets where traditional banks still rely on branches and paperwork.
One large digital lender is pushing hard there, using a branch free model, low servicing costs and heavy automation to keep accounts running cheaply.
It relies on customer data to sharpen credit decisions and personalise offers, rather than just cutting headline rates.
If that approach keeps winning users and deposits, the role of a bank in fee heavy markets could start to look very different.
That argument has a Narrative and a number behind it. → See the company one Narrative values 50% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com