
Cactus (WHD) Could Be 12% Undervalued As Growth And Cash Generation Stay In Focus
Cactus stock performance snapshot
Cactus (WHD) has attracted fresh attention after a recent move left the share price at US$63.15, with the stock showing mixed short term returns alongside stronger figures over the past 3 months and year.
The latest move in Cactus reflects a pattern where a 4.59% 1-day share price return sits against softer 30-day performance, while the 90-day share price return of 18.84% and 1-year total shareholder return of 60.13% point to momentum that has been building rather than fading.
Scan beyond Cactus by reviewing hand picked energy hardware and infrastructure peers with strong recent momentum in the 55 AI infrastructure stocks.
Recent gains and a 1-year total return above 60% leave Cactus looking far richer than it did a year ago. Investors may now be asking whether the current price offers enough potential upside to justify the risk buyers are taking.
Most Popular Narrative: 12% Undervalued
Cactus closed at $63.15 while the most followed narrative pegs fair value at $71.56. This frames the recent rally as only part of the move that narrative followers are watching.
The current valuation implies that the market is not fully pricing in the potential earnings contribution from Spoolable Technologies growth, Cactus International synergy targets, and the company’s rising cash generation. This perspective therefore characterizes Cactus as undervalued and maintains a positive outlook on the shares.
See why 9 investors see Cactus as 12% undervalued.
Result: Fair Value of $71.56 (UNDERVALUED)
Still, the Cactus story can be knocked off course if tariff costs stay elevated, or if Cactus International underdelivers on integration and order intake.
Find out about the key risks to this Cactus narrative.
Another view on Cactus valuation
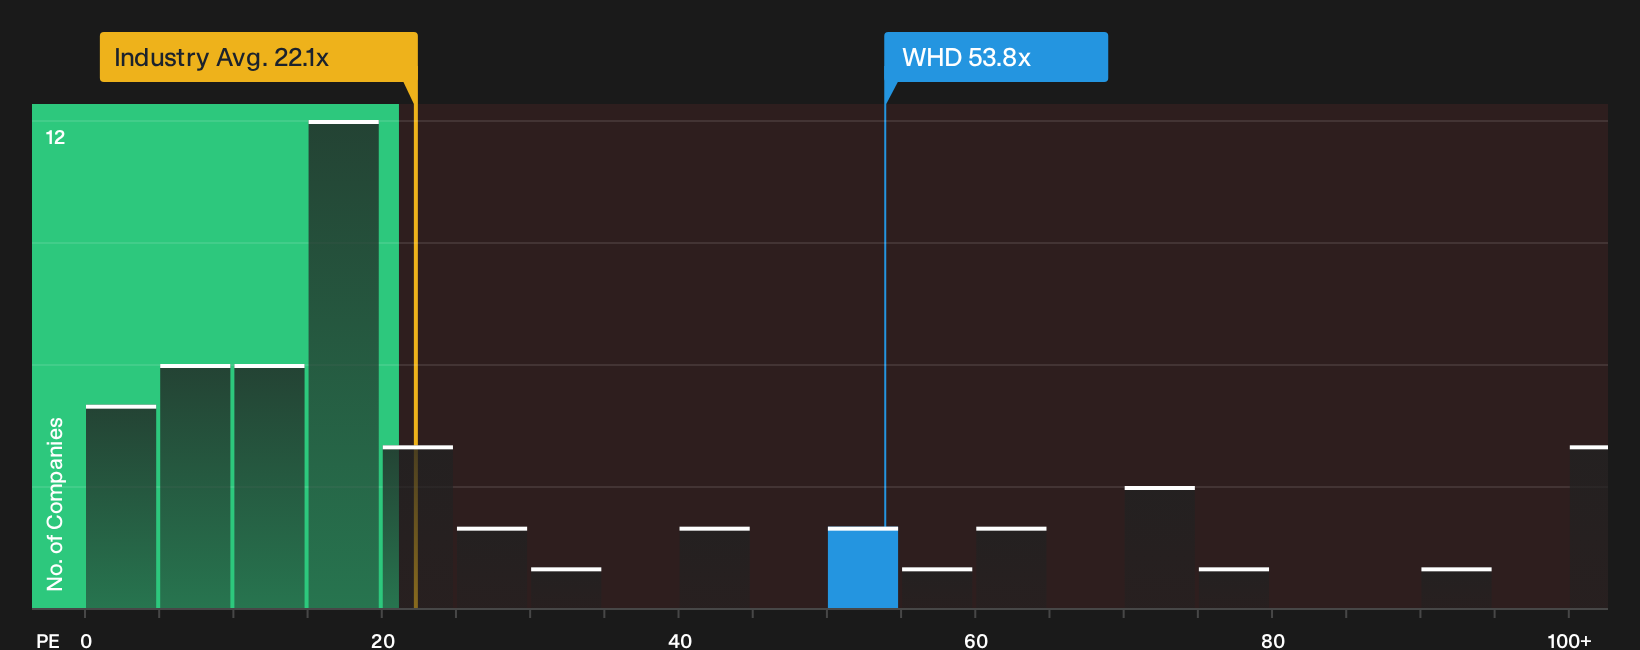
While the narrative and analyst targets frame Cactus as undervalued at a fair value of $71.56, the simple P/E check sends a different message. The shares trade at about 53.8x earnings versus 22.1x for the US Energy Services industry and 17.6x for peers, with a fair ratio of 36.6x suggesting plenty of room for that multiple to compress. If sentiment cools even slightly, how much P/E risk are you really comfortable holding?
To see how this richer multiple stacks up in more detail, including how it compares to peers and the fair ratio the market could move toward, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Cautious about the split views on Cactus yet curious what the numbers really add up to? Move quickly and test the bullish and bearish arguments against your own filters, starting with 2 key rewards and 2 important warning signs.
Looking for more Cactus style investment ideas?
If Cactus has sharpened your focus, do not stop here. Give yourself more options by lining up a few fresh ideas before the next move hits.
- Target steadier potential returns by scanning a 30 resilient stocks with low risk scores that can help balance out more volatile positions in your portfolio.
- Hunt for quality at a discount by reviewing a 28 high quality undervalued stocks that combine strong fundamentals with prices that still look reasonable.
- Build staying power into your holdings by checking a list of solid balance sheet and fundamentals (24 results) that can better handle shocks when conditions change.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com