
Microchip Technology (MCHP) Expands In Data Center And Automotive, Is It Still Undervalued?
Microchip Technology (MCHP) just stacked three product and partnership announcements in space, data center and automotive, giving investors fresh information on where the business is aiming to grow next.
On the screen, Microchip Technology has been treading water in the short term, with the share price down 5.9% over the past month and 2.2% over the last quarter, even as the year-to-date share price return sits at 13.9% and the 1-year total shareholder return of 17.7% points to steadier long-run momentum.
Spot 55 AI infrastructure stocks that, like Microchip Technology, aim to power the next wave of data center, AI acceleration and edge compute build outs.So after a solid 1-year return but a weak recent run, does Microchip Technology still offer enough upside potential to justify the risk at around $74, or has the easy part of the move already passed?
Most Popular Narrative: 32% Undervalued
On the narrative view, Microchip Technology’s fair value of $108.64 sits well above the recent $74.05 close, which puts the focus on whether its AI, data center and aerospace exposure can justify that gap.
Microchip Technology is seeing structural expansion in data center and AI infrastructure exposure, with total data center revenue expected to increase from about US$591 million in 2025 to roughly US$1 billion in 2026 and PCIe Gen6 design wins, including an estimated US$100 million annual program starting in 2027, which together point to a larger contribution to future revenue.
See why 61 investors see Microchip Technology as 32% undervalued.
Result: Fair Value of $108.64 (UNDERVALUED)
Still, elevated inventory write offs alongside ongoing factory underutilization charges, as well as the risk of capacity bottlenecks in foundry and packaging, could quickly challenge that upbeat Microchip Technology narrative.
Find out about the key risks to this Microchip Technology narrative.
Another View: What Microchip Technology’s P/E Is Telling You
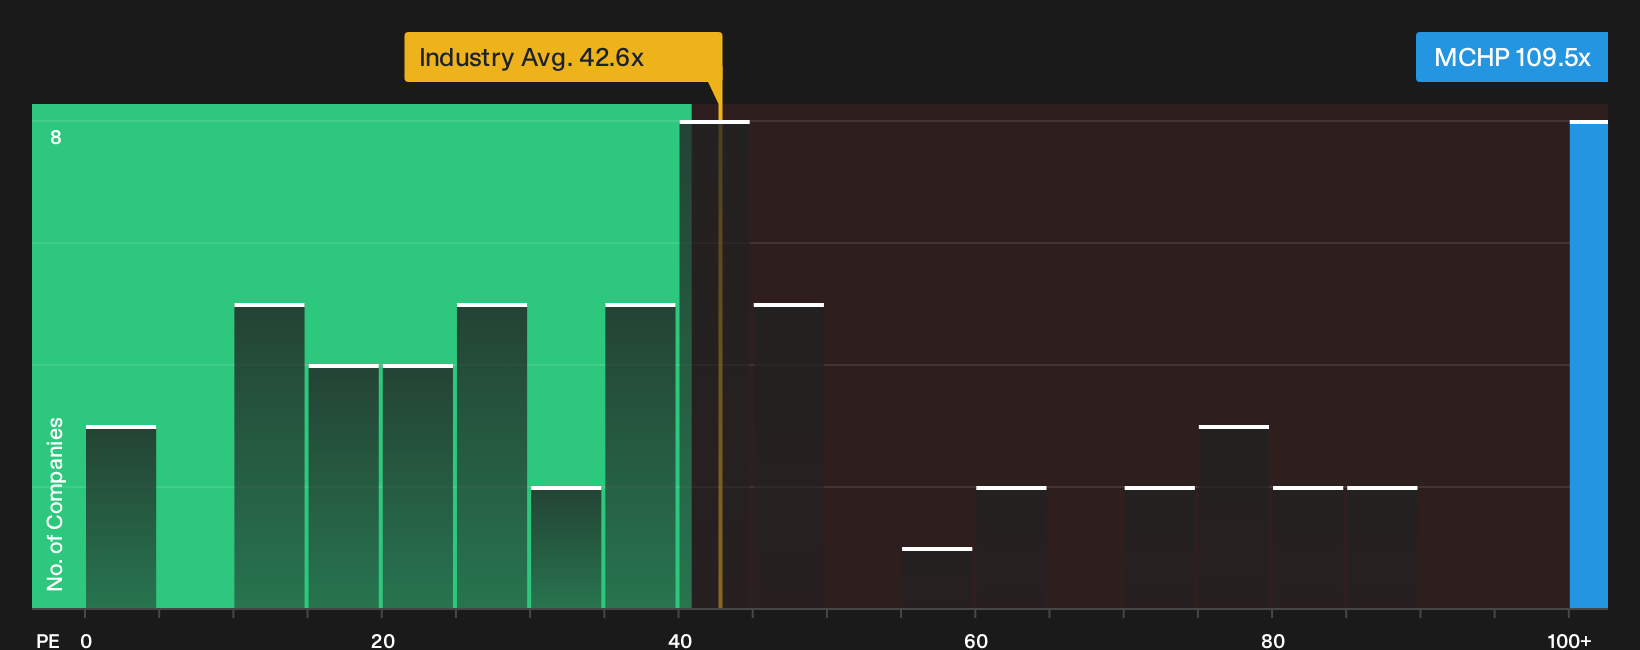
The first narrative presents Microchip Technology as meaningfully undervalued. On simple earnings multiples, the picture looks very different. The stock trades on a P/E of about 109.5x, while the broader US Semiconductor group is around 42.6x and close peers average 54.8x.
The Simply Wall St fair ratio is much lower at 35.3x, which indicates that rich expectations are already built into today’s price and that there is less room for error if the AI and aerospace stories do not fully play out. With such a wide gap between the current P/E and that fair ratio, it may be worth considering how comfortable you are paying up for this growth path versus waiting for the numbers to catch up.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Microchip Technology after these moves and valuation checks. If you want your own answer rather than someone else’s headline, go straight to the balance of 2 key rewards and 2 important warning signs.
Hunting For More Ideas Beyond Microchip Technology?
If Microchip Technology does not quite fit your plan, widen the net and use screeners that surface different types of opportunities before the crowd notices.
- Target potential mispricing by scanning a focused set of 28 high quality undervalued stocks that combine quality fundamentals with discounts to estimated fair value.
- Prioritize resilience over drama by filtering for 30 resilient stocks with low risk scores that aim to keep portfolio swings in check when volatility increases.
- Spot potential future leaders early by sorting through 21 high quality undiscovered gems before broader market attention drives heavier trading interest.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com