
What Early Dollar Tree Buyers Saw
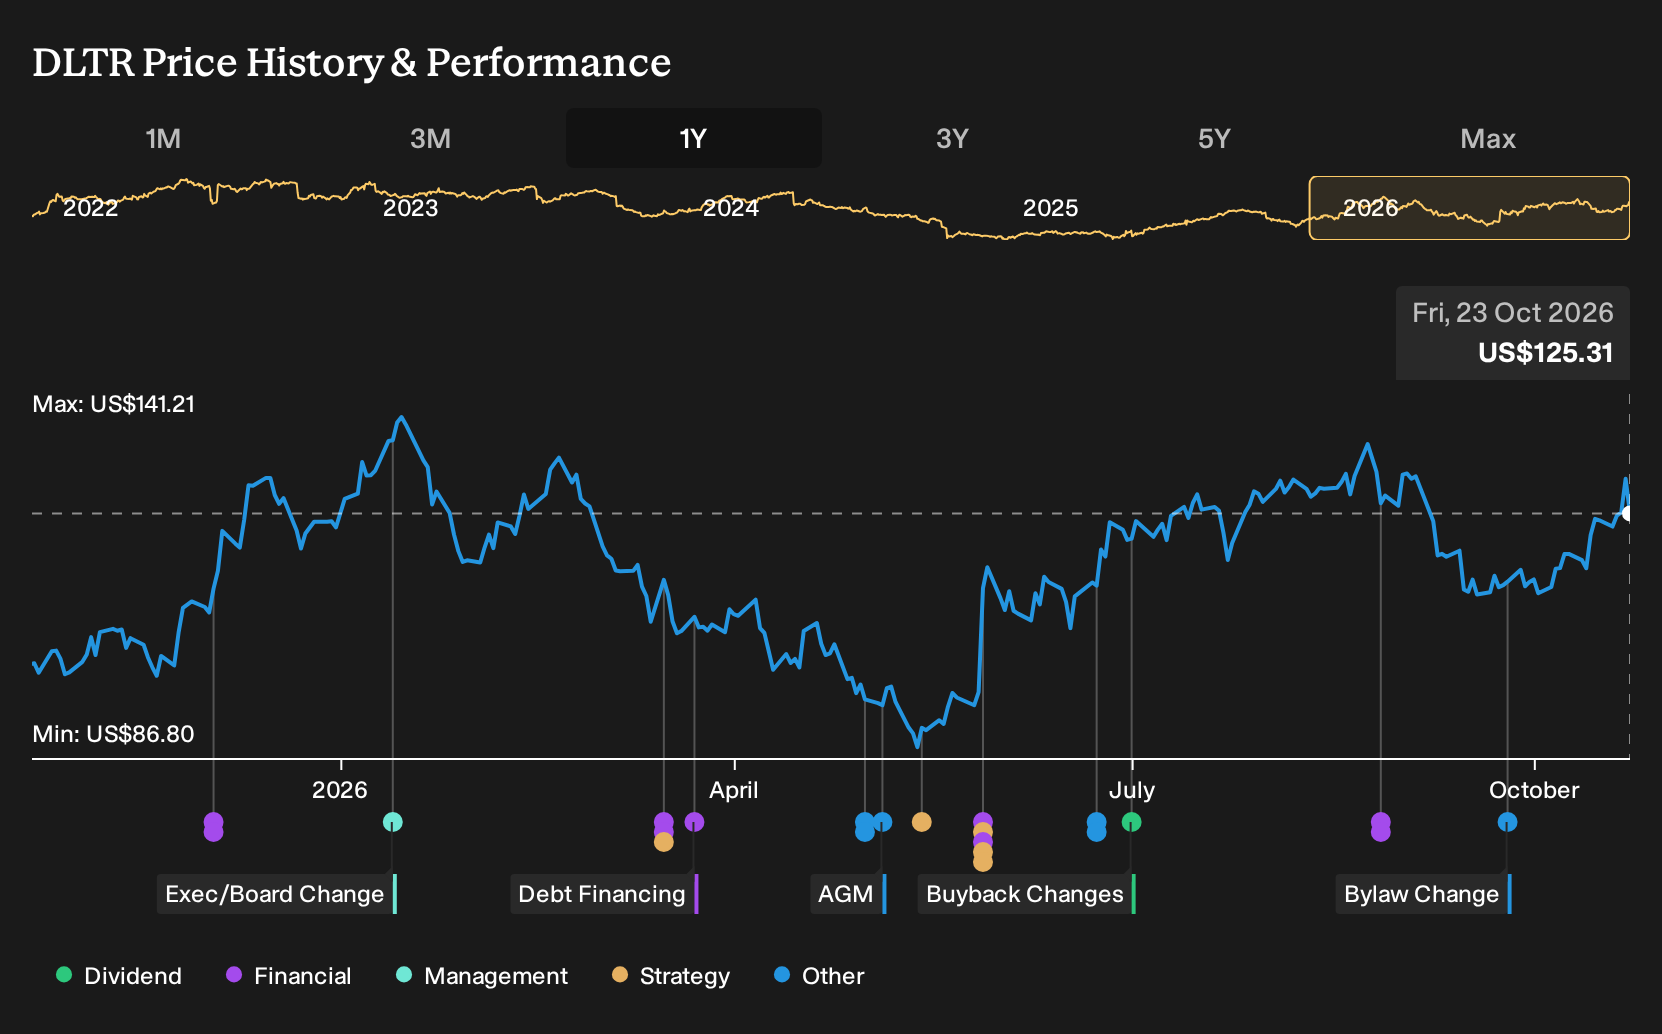
If you had bought Dollar Tree on 23 October 2025, you would now be looking at a very different picture than the split analyst views on your screen that day. For Dollar Tree shareholders, the return over the past year was 22.1%, including dividends. The dilemma then was clear. Should investors trust forecasts that pointed to revenue growth and margin expansion, or lean into warnings about tariffs, labor costs, and Family Dollar transition drag still hanging over the story?
Dollar Tree has already moved. See which of 28 high quality undervalued stocks still trade below our estimates.
The Two Dollar Tree Stories Investors Were Arguing About
The shares cost US$101 at the start of the period, and anyone weighing up Dollar Tree then had to choose between two very different roadmaps.
On the optimistic side, one camp saw a Fair Value of US$112, a price implied by assumptions such as 6.0% annual revenue growth and profit margins reaching 6.2% as multi price assortments, store expansion, and digital partnerships scaled up.
The cautious camp worked off a Fair Value of US$73.17, based on slower 3.2% top line growth, profit margins slipping to 5.8%, and pressure from tariffs, labor costs, and Family Dollar transition spending.
What The Results Changed In The Dollar Tree Debate
Dollar Tree closed the period with Q2 2027 revenue of US$4,891.2 million and net income of US$514.5 million, with net margin rising from 3.4% in Q2 2026 to 10.5%. That profit step up and margin lift leaned toward the optimistic case that assumed better profitability, even as news about tariffs, fuel, and wage pressures kept the cautious script in play. Overall, the evidence cut both ways.
The hinge assumption was margin resilience. When you assess another retailer, track whether net margin and absolute earnings move toward or away from the story management presented, then judge any growth forecast or P/E against that record.
What Dollar Tree's 22% Run Already Prices In
Dollar Tree now trades at US$125, up 22.1% over the past year from US$101. The selected Narrative’s Fair Value sits below the current price, which frames today’s quote as already paying up for solid execution.
That Narrative hangs on rising freight, delivery and supply shocks. A buyer today is effectively assuming Dollar Tree can offset those costs with cleaner stores, better shrink control and multi price merchandising, so the open question is how far those pressures eat into that earnings story.
"Despite progress in shrink reduction and the build out of product protection, elevated fuel prices tied to conflict in the Middle East are expected to keep freight costs higher for the rest of 2026. This can cap the benefit from operational improvements and hold back gross margin and net margin compared with what current guidance and expectations imply."
The price and this Narrative do not agree. → Uncover what this Narrative says Dollar Tree is actually worth
Another Discount Question To Ask
Once you understand Dollar Tree, it is hard not to look sideways. Other retailers are trying to pull spending into fresh corners.
One giant is building out an extra unit focused on amusement, specialty food and digital services. It is chasing shoppers who want more than a quick refill basket.
This arm leans on data tools to fine tune what people see and buy. It pushes beyond aisles into experiences and online platforms.
If that experiment reshapes how households split their budgets, the pressure and opportunity for Dollar Tree could both look different.
That argument has a Narrative and a number behind it. → See the company one Narrative values 29% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com