
Yankuang Energy Group (SEHK:1171) Lifts Profit Guidance On A Valuation That Still Looks Cheap
Yankuang Energy Group (SEHK:1171) has pulled fresh investor attention after issuing new earnings guidance that points to sharply higher net profit for the first three quarters of 2026, despite softer volumes.
The new guidance comes amid a mixed price backdrop for Yankuang Energy Group. The share price is up 6.87% year to date but down about 10% over the past month, and the 5-year total shareholder return of 208.36% reflects strong longer-term compounding.
Scan other coal and energy producers showing similar profit momentum and pricing gaps by checking the hand picked 194 high quality undervalued stocks alongside Yankuang Energy Group.
Yankuang Energy Group now trades about 30% below the average analyst target and at a steep intrinsic discount. Where does a fair appraisal fall between recent price weakness and that wide valuation range?
Price-to-Earnings of 8.3x: Is it justified for Yankuang Energy Group?
On a P/E of 8.3x against a last close of HK$10.42, Yankuang Energy Group screens as inexpensive compared to peers, which points to a market that is pricing in a more cautious profit outlook than the sector average.
The P/E multiple links the current HK$10.42 share price to the earnings that Yankuang Energy Group generates today, and investors often use it as a shorthand for how much they are paying for each unit of profit. For coal and energy producers, where earnings can be influenced by commodity cycles, this ratio can swing sharply as sentiment shifts between strong and weak periods.
Yankuang Energy Group is assessed as trading at good value compared to peers and its industry, with a P/E of 8.3x versus a peer average of 16.5x and an Asian Oil and Gas industry average of 11x. The estimated fair P/E ratio of 9.7x sits above the current level. This suggests the market may, over time, move closer to that fair multiple if earnings and cash flows track expectations and sentiment stabilises.
Explore the SWS fair ratio for Yankuang Energy Group.
Result: Price-to-Earnings of 8.3x (UNDERVALUED)
Still, Yankuang Energy Group faces meaningful risks if coal demand softens faster than expected or if regulatory changes affect its core mining and chemical operations.
Find out about the key risks to this Yankuang Energy Group narrative.
Another View on Yankuang Energy Group’s Value
A different lens comes from the SWS DCF model, which values Yankuang Energy Group at HK$98.19 per share versus the current HK$10.42. That is a very large gap that also labels the stock as undervalued. If both earnings multiples and cash flow point to the stock being cheap, what risk might the market be focusing on?
Look into how the SWS DCF model arrives at its fair value.
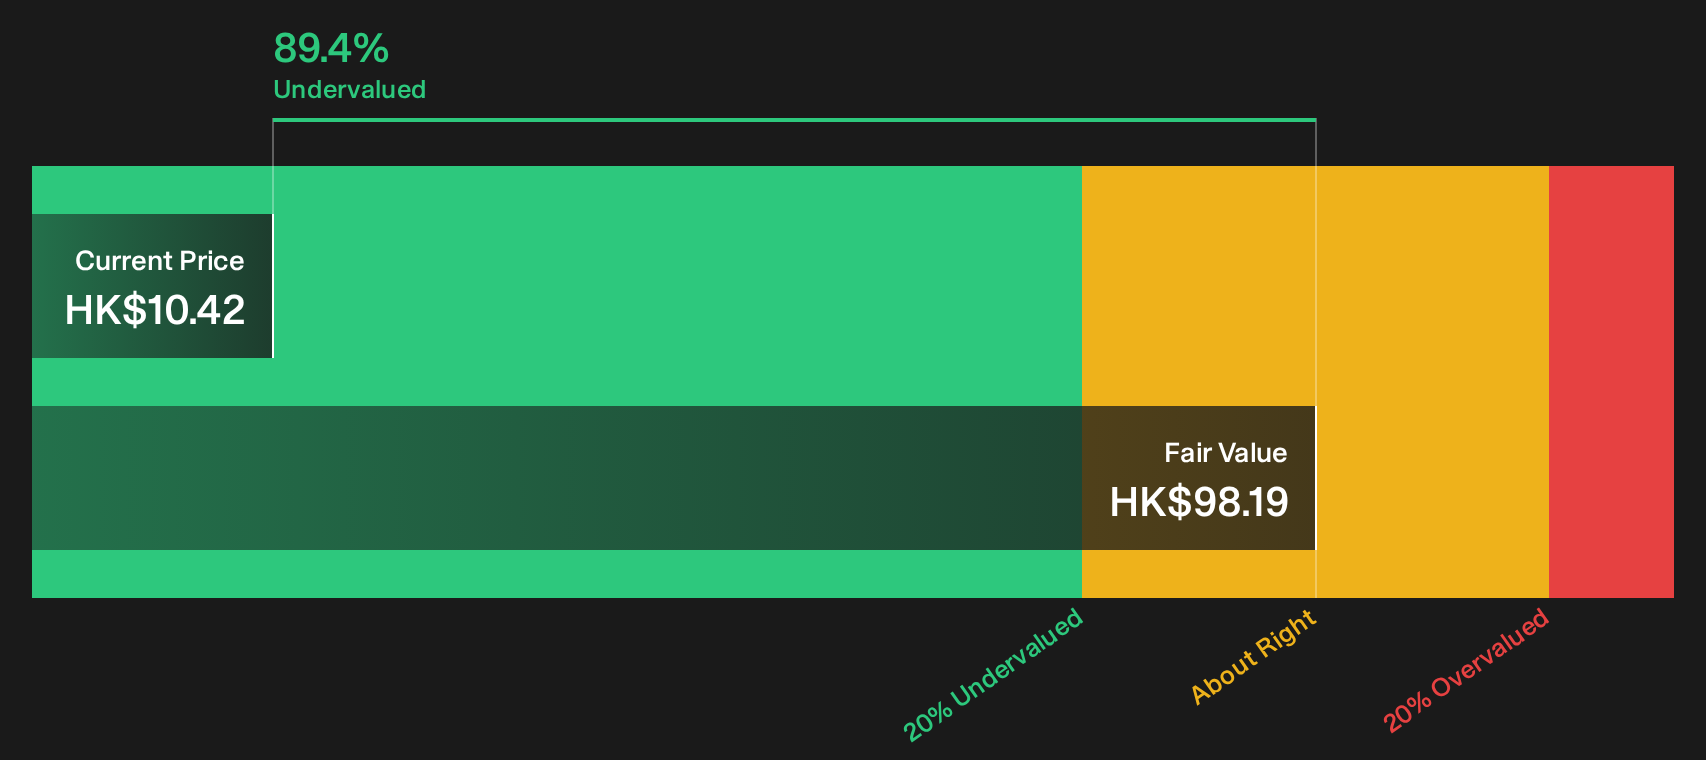
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Yankuang Energy Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 194 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals like this rarely stay unresolved for long. Review the numbers, stress test your own assumptions, and weigh both sides of the story with the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Yankuang Energy Group?
If Yankuang Energy Group is on the watchlist, do not stop there. Broader ideas give more context and help you avoid leaning on a single thesis.
- Target steady potential by scanning companies that combine income with resilience through the 225 dividend fortresses.
- Hunt for mispriced opportunities where quality and valuation line up using the 610 high quality undiscovered gems.
- Prioritise capital protection by filtering for businesses with robust finances via the list of solid balance sheet and fundamentals (207 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com