
Stella International Holdings (SEHK:1836) Revenue Update Keeps Undervalued Narrative In Focus
Revenue update puts fresh attention on Stella International Holdings
Stella International Holdings (SEHK:1836) has drawn fresh attention after reporting unaudited sales for the quarter and nine months to 30 September 2026, with revenue showing low single digit percentage increases.
Against that sales update, Stella International Holdings is trading at HK$12.99 after a recent 1 month share price return of 9.62%, while the share price has fallen 14.76% year to date and the 5 year total shareholder return is 132.31%. This suggests that long term holders have still seen strong compounding even as shorter term momentum has been mixed.
Compare Stella International Holdings with a curated 195 high quality undervalued stocks that pairs modest growth with current share prices implying a discount to estimated fair value.
Stella International Holdings trades below both analyst targets and an estimated intrinsic value, even after the recent rebound. Is that discount compensation for real risks, or has caution gone too far as you weigh valuation next?
Most Popular Narrative: 12% Undervalued
On the most followed view, Stella International Holdings screens as undervalued, with a fair value of HK$14.78 set against the last close at HK$12.99, and that gap rests on execution of its expansion and efficiency plans.
Stella's ongoing expansion of manufacturing capacity, adding up to 25 million pairs across Indonesia and Bangladesh with dedicated facilities for top global brands, positions the company to benefit from increasing demand for premium and branded footwear as rising middle-class incomes and consumer upgrading trends continue globally; this is set to drive revenue growth and improve long-term earnings visibility.
See why 1 investors see Stella International Holdings as 12% undervalued.
Result: Fair Value of HK$14.78 (UNDERVALUED)
Still, the bullish Stella International Holdings story could unravel if higher production costs continue squeezing margins or if any major global brand partner cuts back orders.
Find out about the key risks to this Stella International Holdings narrative.
Another View On Stella International Holdings’ Valuation
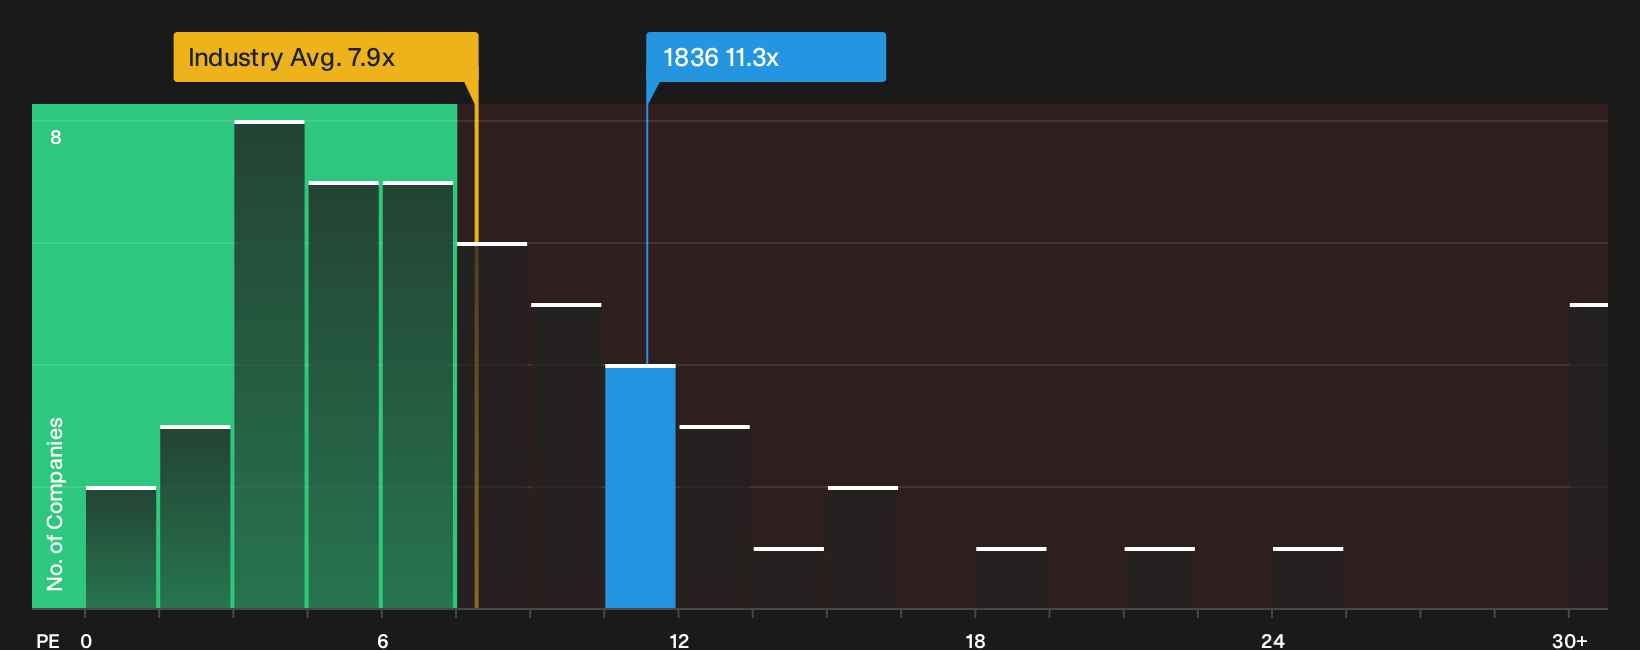
On earnings multiples, Stella International Holdings looks less clear cut. The stock trades on a P/E of 11.3x, above the Hong Kong Luxury industry at 7.9x and also above an estimated fair ratio of 8.1x, yet below the 17.1x peer average. That gap can signal either valuation risk or a pricing opportunity depending on which comparison you trust more.
For a closer look at what those ratios imply for the current share price, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals rarely settle the debate on a stock like Stella International Holdings, so weigh the upside and downside quickly using the 2 key rewards and 1 important warning sign.
Ready for more ideas beyond Stella International Holdings?
If Stella International Holdings has sharpened your focus on valuation and quality, do not stop here. Use targeted screeners to spot other potential opportunities before the crowd.
- Target dependable income by zeroing in on companies with robust payouts and balance sheets through the 225 dividend fortresses.
- Hunt for quality at a discount by scanning a curated 610 high quality undiscovered gems that filters for strong fundamentals and lower market attention.
- Reduce portfolio stress by focusing on resilience with a 223 resilient stocks with low risk scores that highlights businesses carrying lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com