
Glaukos (GKOS) Wins Epioxa J Code As Investors Ask If The Stock Is Fully Valued
Why Glaukos Is Back On Investors’ Radar
Glaukos (GKOS) has been in focus after securing a permanent J-code for its Epioxa therapy, along with record Q1 and Q2 2026 sales and new retinal licensing agreements.
The reimbursement code decision shapes how easily providers can bill for Epioxa, which matters directly for access and volume. In addition, fresh product data and guidance have led investors to reassess what the business might earn over time.
Glaukos has ridden a strong upswing, with the share price at about $178.88 and a year to date share price return of 61.56%, while the 1 year total shareholder return of 136.36% signals momentum that investors are linking to the Epioxa J-code decision and record 2026 sales.
Scan how Glaukos compares to other fast moving healthcare stocks in the 34 healthcare AI stocks that are catching fresh attention on reimbursement wins and new therapies.
Glaukos now trades near record levels after the Epioxa catalyst, so the key question is straightforward: does paying up today make more sense than waiting for sentiment and valuation to cool before stepping in?
Most Popular Narrative: 4% Overvalued
Glaukos closed at $178.88 against a most-followed fair value estimate of $172.00, so the narrative lens frames today’s price as slightly ahead of that modeled worth while hinging heavily on reimbursement and spending trade offs.
Although the company emphasizes high gross margins from iDose TR and Epioxa, the forecast increase in 2026 operating expenses to about US$600 million as it “adds fuel” to commercial investments creates a risk that incremental sales from interventional glaucoma and keratoconus therapies do not fully offset spending. This could limit operating leverage and cash flow improvement even if top line trends look healthy.
See why 2 investors see Glaukos as 4% overvalued.
Result: Fair Value of $172.00 (OVERVALUED)
Still, a faster ramp in iDose TR procedures or stronger than expected Epioxa driven keratoconus volumes could challenge the idea that Glaukos is only modestly overvalued.
Find out about the key risks to this Glaukos narrative.
Another View On Glaukos: DCF Says Undervalued
The earlier narrative framed Glaukos as roughly 4% overvalued relative to a $172.00 fair value. A different lens tells a very different story. The Simply Wall St DCF model estimates future cash flows at $268.77 per share, so at $178.88 the stock appears to be trading at a 33.4% discount instead of a premium. Which yardstick should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
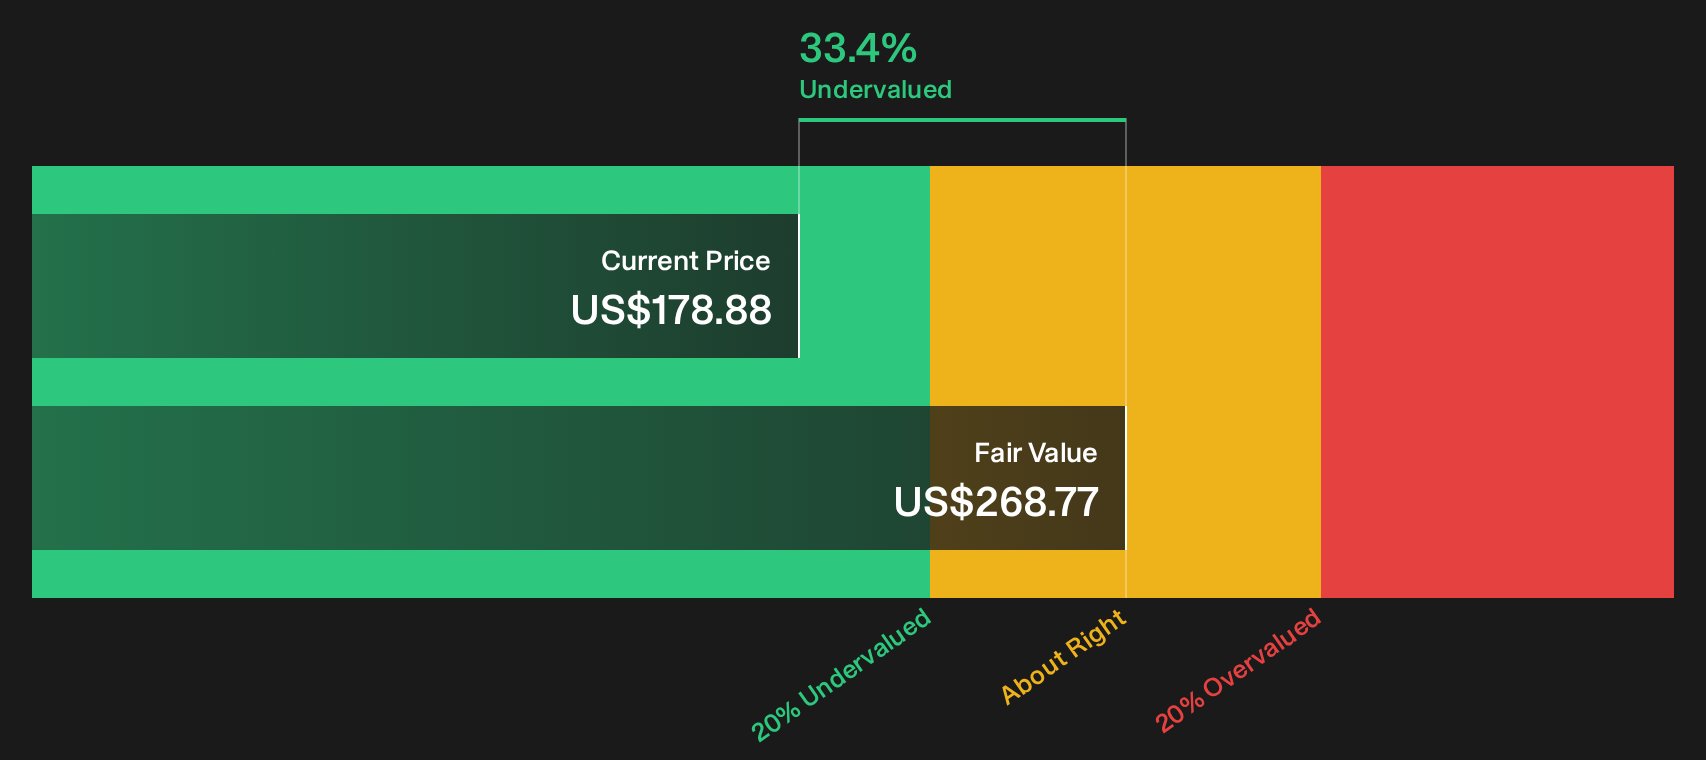
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Glaukos for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Glaukos is split, with some investors focused on upside potential and others zeroing in on pressure points, so move quickly and review the data to decide where you land. To weigh both sides in one place, start with the 2 key rewards and 1 important warning sign.
Looking For More Ideas Beyond Glaukos?
Glaukos may be front of mind today, but your next strong opportunity could be sitting in plain sight if you scan the wider market with a focused set of filters.
- Target potential mispricings by running through a curated 28 high quality undervalued stocks that filters for quality businesses trading below their assessed worth.
- Prioritise resilience and sleep easier at night by checking a 30 resilient stocks with low risk scores built around companies with sturdier balance sheets and lower risk scores.
- Hunt for under-the-radar potential by reviewing a 21 high quality undiscovered gems that highlights strong fundamentals in stocks many investors are still overlooking.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com