
Is Beiersdorf (XTRA:BEI) Fully Valued After Its Tour De France Nivea Sun Deal?
Amaury Sports Organisation’s new multi-year partnership with Nivea Sun puts Beiersdorf (XTRA:BEI) directly into the Tour de France spotlight, tying its skincare products to mass-market cycling audiences across more than 20 European countries.
Recent trading has started to reflect that story. The 1-month share price return of 7.08% and 90-day move of 4.37% point to what some investors may view as improving momentum for Beiersdorf, even though the year-to-date share price is still down 9.37% and the 3-year total shareholder return has declined 29.45%.
Compare Beiersdorf’s Tour de France spotlight with other consumer stocks on the move by scanning our curated list of 195 high quality undervalued stocks for potential opportunities related to strong brands and steady fundamentals.
Beiersdorf’s share price has bounced in the past month, yet the stock still trades at a discount to one fair-value estimate while sitting slightly above analyst targets. Is that gap signalling opportunity or justified caution?
Most Popular Narrative: 3.7% Overvalued
Against the last close at €84.12, the most followed narrative pegs Beiersdorf’s fair value at €81.11, implying a modest premium that hinges on specific brands and margin expectations playing out as hoped.
The main thing that has to go right is that the NIVEA turnaround and heavier marketing spend translate into a sustainable recovery in Consumer sales and margins after the planned 2026 step down.
The current valuation and this narrative’s fairly valued, bullish stance imply the share price already reflects successful Derma expansion, a credible NIVEA recovery and a return to profitable, above‑market growth from 2028.
See why 17 investors see Beiersdorf as 4% overvalued.
Result: Fair Value of €81.11 (OVERVALUED)
Still, the NIVEA reset and the planned 2026 Consumer EBIT margin step down could extend pressure on earnings if additional marketing and digital spending fail to gain traction.
Find out about the key risks to this Beiersdorf narrative.
Another View: Beiersdorf Through The Cash Flow Lens
There is a sharp contrast between the crowd narrative and Simply Wall St’s own DCF work. While community fair value clusters at €81.11 and tags Beiersdorf as 3.7% overvalued, the SWS DCF model points to a future cash flow value of €111.30, which frames the current €84.12 price as discounted. Which reference point do you trust more: the consensus story or the cash flow maths?
Look into how the SWS DCF model arrives at its fair value.
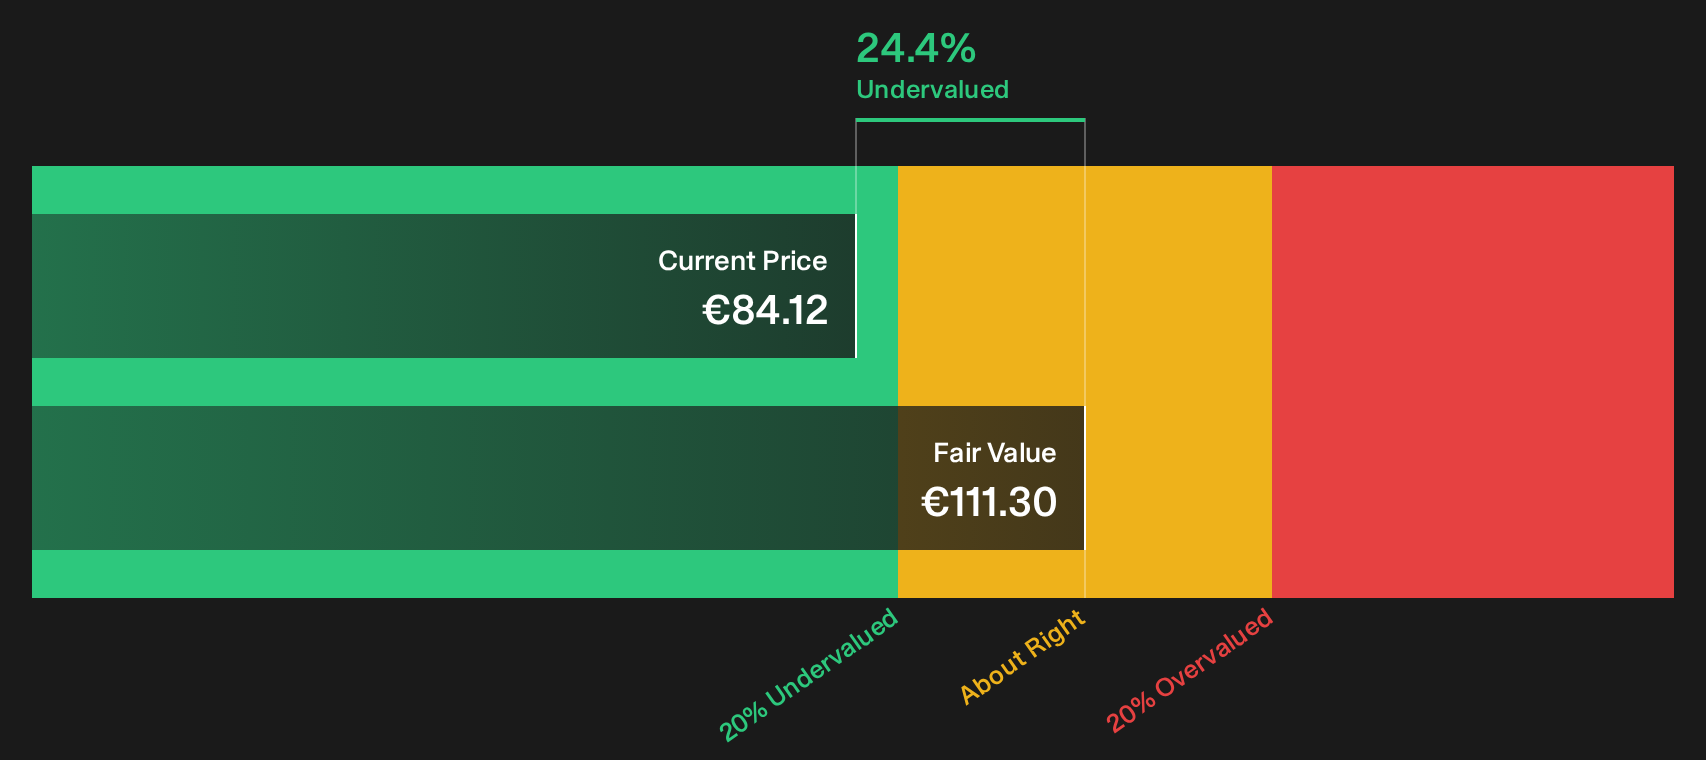
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Beiersdorf for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the Beiersdorf story so far. If you want to move fast and build your own view, start with the positives in its profile and see how they stack up against the 3 key rewards.
Looking for more Beiersdorf investment ideas?
Do not stop at Beiersdorf. Use the Simply Wall St Screener to pressure test your thinking, surface fresh ideas, and keep your watchlist working harder.
- Spot opportunities with strong income potential by scanning a curated set of 225 dividend fortresses that focus on consistent payouts and higher yield thresholds.
- Zero in on financially resilient businesses by reviewing the list of solid balance sheet and fundamentals (207 results) that can support operations through different conditions.
- Get ahead of the crowd by tracking 610 high quality undiscovered gems that pair solid fundamentals with relatively low current visibility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com