
Is Murphy Oil (MUR) Fully Priced Following Offshore Discoveries And New Production?
Murphy Oil (MUR) has put fresh exploration results in the spotlight after reporting successful appraisal at Bubale West offshore Côte d’Ivoire, new discoveries offshore Vietnam, and initial production from the Chinook #8 well.
The recent stream of exploration successes seems to be feeding into sentiment around Murphy Oil. The share price is at US$44.34 and the 30 day share price return is 22.05%, adding to a 36.47% year to date gain. The 1 year total shareholder return of 60.86% and 5 year total shareholder return of 80.69% suggest that momentum has been building over time rather than just on this latest announcement.
Scan for other energy explorers showing similar momentum to Murphy Oil by reviewing our curated list of 21 high quality undiscovered gems before your watchlist fills up with yesterday's stories.
After a 60.86% 1 year total return and strong exploration headlines, Murphy Oil now sits at US$44.34. Does the current price still offer an appealing risk reward, or has most of the upside already been claimed?
Most Popular Narrative: 6% Overvalued
Murphy Oil closed at $44.34, while the most followed narrative pegs fair value around $41.93. The story leans toward a market that is already paying up for execution on big projects rather than waiting on proof.
The main thing that has to go right is that higher capital spending, especially on Bubale appraisal and the Eagle Ford ramp, converts into commercially attractive offshore volumes without eroding the balance sheet or dividend capacity.
The current valuation implies that Murphy Oil is fairly valued, with the market already pricing in meaningful success from its long duration offshore growth projects and sustained free cash flow from onshore assets.
See why 14 investors see Murphy Oil as 6% overvalued.
Result: Fair Value of $41.93 (OVERVALUED)
Still, Murphy Oil’s higher 2026 capex plan, along with the cost and appraisal risk around Bubale and Vietnam, could challenge the current fair value story.
Find out about the key risks to this Murphy Oil narrative.
Another View: SWS DCF Flags Deep Undervaluation
The analyst narrative puts Murphy Oil roughly 6% above its $41.93 fair value, yet the SWS DCF model lands in a very different place. In that framework, MUR at $44.34 appears undervalued relative to an estimated future cash flow value of $127.98. This raises a key question: which signal carries more weight for investors, the earnings multiple or the cash flow analysis?
Look into how the SWS DCF model arrives at its fair value.
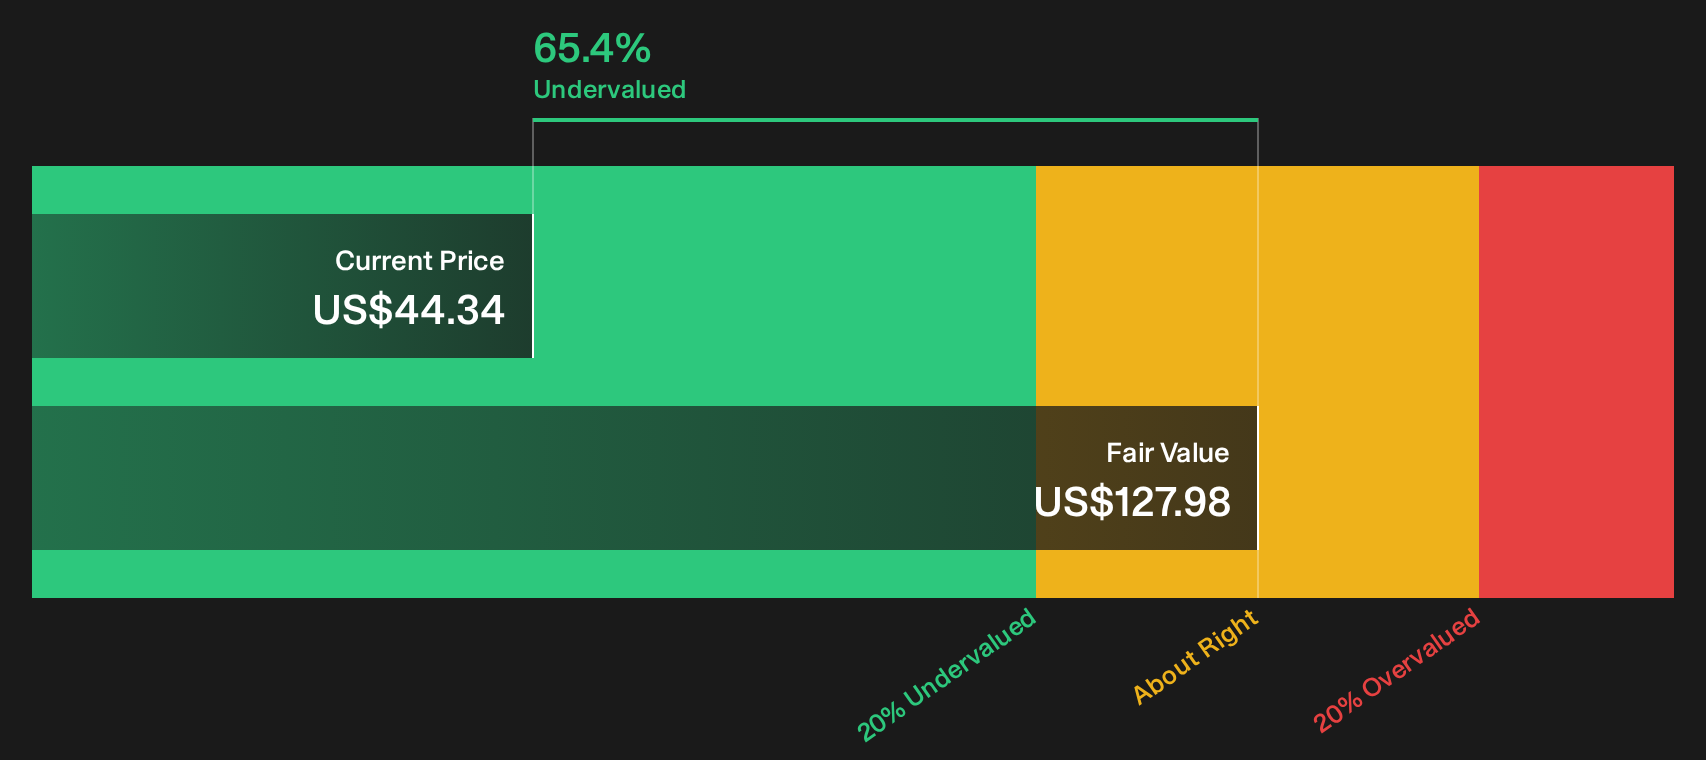
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Murphy Oil for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With sentiment clearly split between rich valuation and deep value, you should move quickly and weigh the evidence yourself. Start by checking the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Murphy Oil?
If Murphy Oil has sharpened your focus, do not stop here. The screener surfaces fresh opportunities that might fit your style before everyone else spots them.
- Target potential mispricing by scanning a curated pool of quality stocks through the 28 high quality undervalued stocks.
- Strengthen your defense with companies that carry resilient balance sheets using the list of solid balance sheet and fundamentals (24 results).
- Dial back risk while staying invested by filtering for lower volatility profiles via the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com