
Did Fleury's 105% Run Pass You By? What The Bulls Got Right
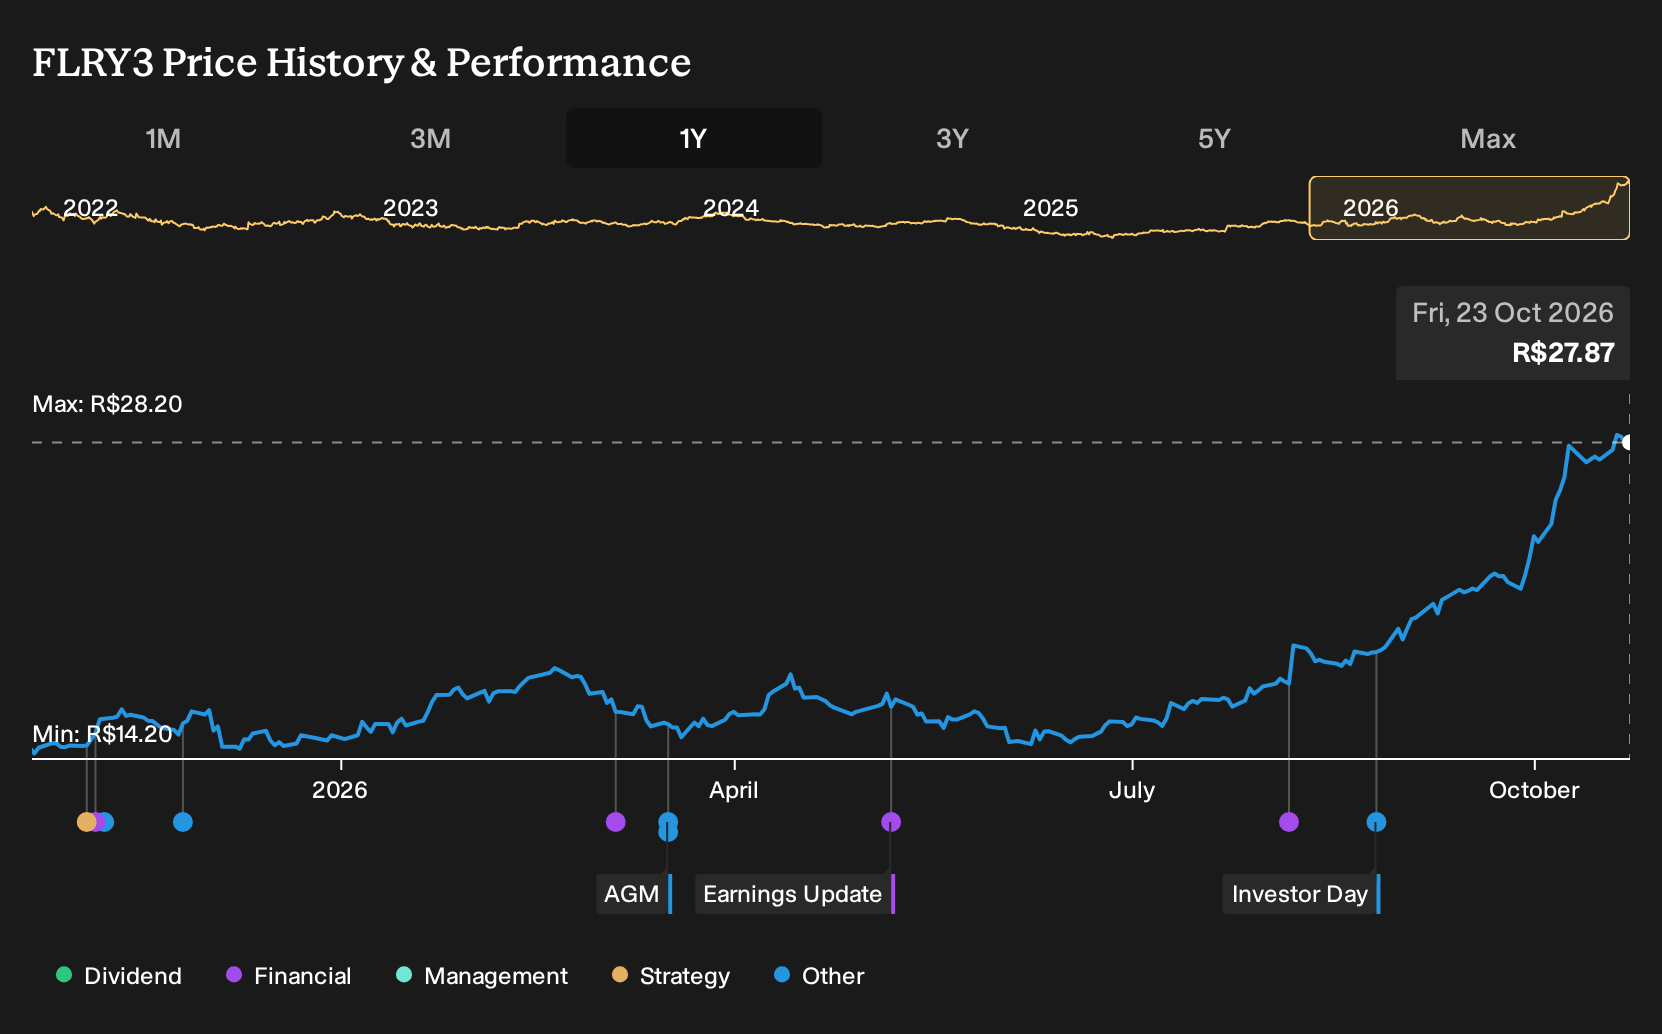
Fleury spent the year quietly turning AI promises into a concrete outcome in its labs, with reported processing times in key workflows cut by over 90% even before the latest results. Investors who held Fleury over the past year are up 105.3%, including dividends. If you had bought at the start of that run, you would now be asking a simple question: What exactly had to be believed about this diagnostics group before any of that upside looked reasonable?
Fleury has already moved. See which of 195 high quality undervalued stocks still trade below our estimates.
The Two Fleury Stories Investors Had To Weigh
The shares cost R$14.2 at the start of the period, and anyone looking at Fleury then had to pick between two very different yet credible stories.
On the optimistic side, the bullish camp argued that aging demographics and AI could reshape preventive care. Their Fair Value was R$19.5, presented as the price implied if that thesis played out, anchored on Fleury using acquisitions and technology to scale, widen margins, and lift returns.
The cautious view set Fair Value at R$12.25, again as a price implied by its own set of assumptions, built around rising inequality, government cost controls, and digital disruption compressing pricing power and profitability over time.
What The Results Changed For The Fleury Argument
The clearest fresh data point was Fleury's latest quarterly report. Total revenue and net income both rose between Q2 2025 and Q2 2026, and net margin increased from 7.5% to 9.6%. That margin shift leaned toward the optimistic story that imagined better profitability from scale and AI, although one reporting period still left the cautious case alive.
The lesson to take elsewhere is simple. When a thesis hinges on efficiency and pricing power, anchor your check on changes in net margin and absolute profit, not just headline revenue.
What Fleury's One Year Run Already Prices In
Fleury now trades at R$27.87 after a 105.3% gain over the past year, while the selected Narrative places its Fair Value below that level. The Narrative still sees real strengths in Fleury's push into AI, digital services, and broader diagnostics.
The key question for anyone paying today's price is what has to keep working. A buyer needs to judge whether heavy digital and automation spend can keep improving productivity, without letting contract concentration, cost pressure, and Brazil-only exposure drag on margins and cash generation.
"CapEx intensity increased notably (up 44.9% QoQ, with IT/digital investments a major component), while top-line growth slowed (only +2.8% YoY in the quarter); if technological investments do not translate to operational leverage or market share gains, this could lead to margin pressure and diminished returns on invested capital, risking future free cash flow and earnings growth."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Looking One Step Beyond Fleury
Seeing Fleury lean on AI and diagnostics, you might wonder what supports that kind of testing push globally.
Hospitals and clinics still need reliable kits and systems that turn patient samples into clear, timely results.
Another large healthcare group focuses on that practical job, building tools that help detect infections, monitor chronic disease and guide treatment decisions.
It also supplies nutrition products and medical devices, so its earnings do not depend on a single testing line.
If demand for earlier detection and monitoring keeps broadening, that mix could matter in a different way than Fleury's pure diagnostics focus.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 16% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com