
YONEX (TSE:7906) Could Be 42% Undervalued As Valuation Debate Builds
YONEX (TSE:7906) drew fresh attention after its recent share move, with the stock closing at ¥2,402 on 24 October 2026. Investors are weighing that price against the group’s longer term returns and fundamentals.
Recent trading has been choppy for YONEX, with the share price slipping over the past quarter and the year to date while still sitting well above its levels from several years ago when measured by total shareholder return. The latest 1-day share price gain of 1.26% comes after a year in which total shareholder return declined 38.58%, yet investors who stayed invested over three and five years still saw total shareholder returns of 57.04% and 238.09%. This helps keep the current move in context as part of a longer, uneven reset in expectations around growth potential and risk.
Scan beyond YONEX's latest swing and line up other potential rebound stories with the hand picked 14 high quality undervalued stocks that share strong fundamentals and room for sentiment to catch up.
YONEX now trades well below recent highs yet follows several years of strong total returns. Does the current price still skew the risk reward towards buyers, or has that window narrowed?
Price-to-Earnings of 15.3x: Is it justified?
YONEX changes hands at a P/E of 15.3x, which sits just below both its industry and peer averages even after a tough recent share price run.
The P/E ratio compares the current share price with earnings per share and gives a quick sense of how much investors are paying for each unit of profit. For a sports equipment manufacturer like YONEX that already generates meaningful earnings, P/E is a common yardstick because it links directly to the bottom line rather than purely to sales or assets.
Earnings grew 11.8% over the past year and have compounded at 19.4% per year over five years, yet return on equity sits at 15.7%, which the model classifies as low, and net profit margins eased from 8.2% to 7.9%. That mix suggests the current valuation is not priced for aggressive expansion. The fair P/E estimate of 15.1x signals the market is already very close to the level the regression model indicates it could move towards.
Against benchmarks, the stock trades at a P/E of 15.3x compared with 15.7x for the JP Leisure group and 18.3x for direct peers. This is a clear discount relative to similar companies even though the internal fair ratio estimate sits almost exactly where the market is today.
Explore the SWS fair ratio for YONEX.
Result: Price-to-Earnings of 15.3x (ABOUT RIGHT)
Still, the sharp 38.58% total return decline over the past year and a 28.62% fall year to date show how quickly sentiment on YONEX can reset.
Find out about the key risks to this YONEX narrative.
Another View: What The SWS DCF Model Says
The P/E workup on YONEX paints a picture of a stock roughly in line with its fair ratio. The SWS DCF model tells a different story. On that cash flow view, YONEX at ¥2,402 trades at a 42.4% discount to an estimated future cash flow value of ¥4,167.72. This raises a sharper question: Is the market overly cautious, or is the model assuming a smoother path than the business will actually deliver?
Look into how the SWS DCF model arrives at its fair value.
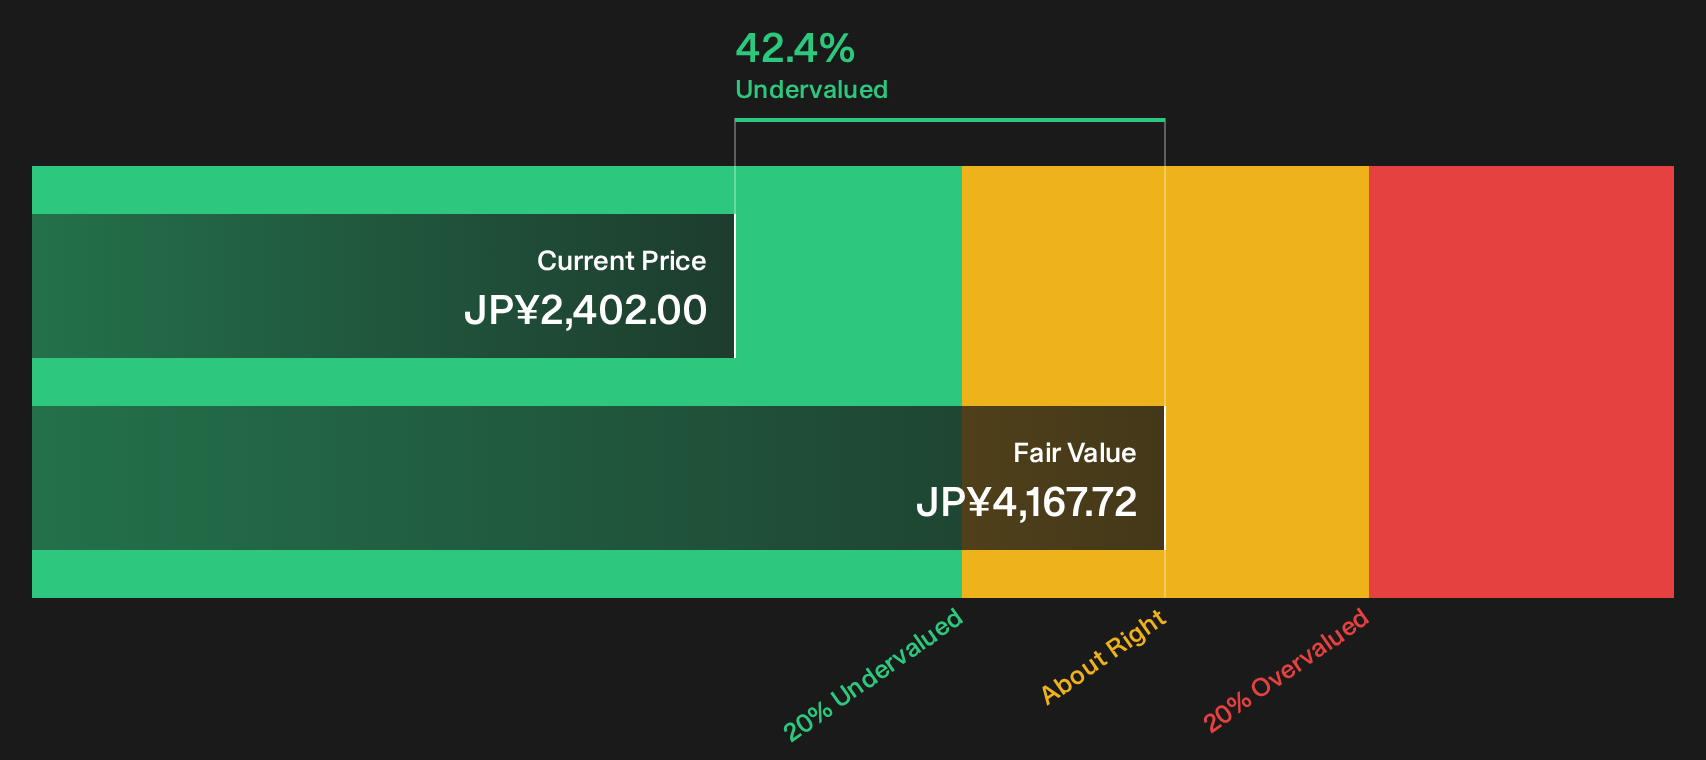
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out YONEX for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 14 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
That mix of caution and optimism around YONEX only matters if you test it against your own reading of the numbers and risks. Take a few minutes to review the key positives investors are watching through the 3 key rewards.
Looking for more investment ideas beyond YONEX?
If YONEX has you rethinking valuations and risk, do not stop here. Fresh opportunities often show up where pricing, balance sheets, and dividends quietly line up.
- Spot potential mispricings early and size up companies where expectations may lag fundamentals by scanning the 14 high quality undervalued stocks.
- Strengthen the defensive side of your portfolio and focus on businesses with room to handle shocks by reviewing the list of solid balance sheet and fundamentals (23 results).
- Build a stream of cash returns and compare payout options that go beyond headline yields using the 30 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com