
Phase 1 2 Cancer Trial Results May Change The Case For Tango Therapeutics Stock
- Tango Therapeutics reported detailed Phase 1/2 data for vopimetostat combinations in MTAP deleted, RAS mutant pancreatic and lung cancers, including high objective response and disease control rates, with defined dosing regimens and safety profiles across daraxonrasib and zoldonrasib arms.
- The company now plans a global randomized registrational trial of vopimetostat plus daraxonrasib in first line MTAP deleted pancreatic cancer, which shifts focus toward potentially label enabling studies, while concentrating research spend around its MTAP selective PRMT5 programs.
- We will look at how Tango Therapeutics' investment narrative evolves as vopimetostat plus daraxonrasib moves toward a planned registrational trial.
Tango Therapeutics Investment Narrative Recap
For a shareholder in Tango Therapeutics, the core belief is that vopimetostat-based combinations can translate early signal into registrational success in MTAP-deleted cancers. The updated vopimetostat plus RAS(ON) data supports moving into a front line, randomized setting in pancreatic cancer, which now looks like the key near-term operational catalyst. The main risk stays the same. Tango is heavily concentrated around vopimetostat and TNG456, with limited backup depth if these regimens disappoint.
In the shorter term, the upcoming launch and execution of the global registrational trial will likely matter more than incremental Phase 1/2 updates. The new data gives Tango Therapeutics clearer dosing, tolerability and response benchmarks to design against, which can help trial setup and discussions with regulators. At the same time, expectations around this program are already high, so delays, lower-than-expected enrollment, or any safety surprises would still be the most material business risk.
The most relevant fresh announcement is Tango Therapeutics planning a global randomized registrational trial that pits vopimetostat plus daraxonrasib against standard chemotherapy in first line MTAP-deleted pancreatic cancer. That decision sits directly on the back of the Phase 1/2 combination results and effectively turns this regimen into the company’s main value driver. Outcomes in this setting could heavily influence how the broader pipeline is funded and prioritized.
For you as an investor, this trial plan creates a clear clinical and operational roadmap. Tango Therapeutics now has a defined regimen and dose that regulators have engaged on, dual primary endpoints in objective response rate and progression-free survival, and a control arm that anchors interpretation. The flip side is higher execution risk. The business must now deliver on trial setup, site activation, enrollment and clean data in a competitive field where other RAS and PRMT5 programs are also advancing.
Tango Therapeutics' narrative projects US$131.1 million revenue and US$20.9 million earnings by 2029. This implies 34.6% yearly revenue growth and an earnings swing of about US$144.6 million from a loss of US$123.7 million today to the forecast profit level.
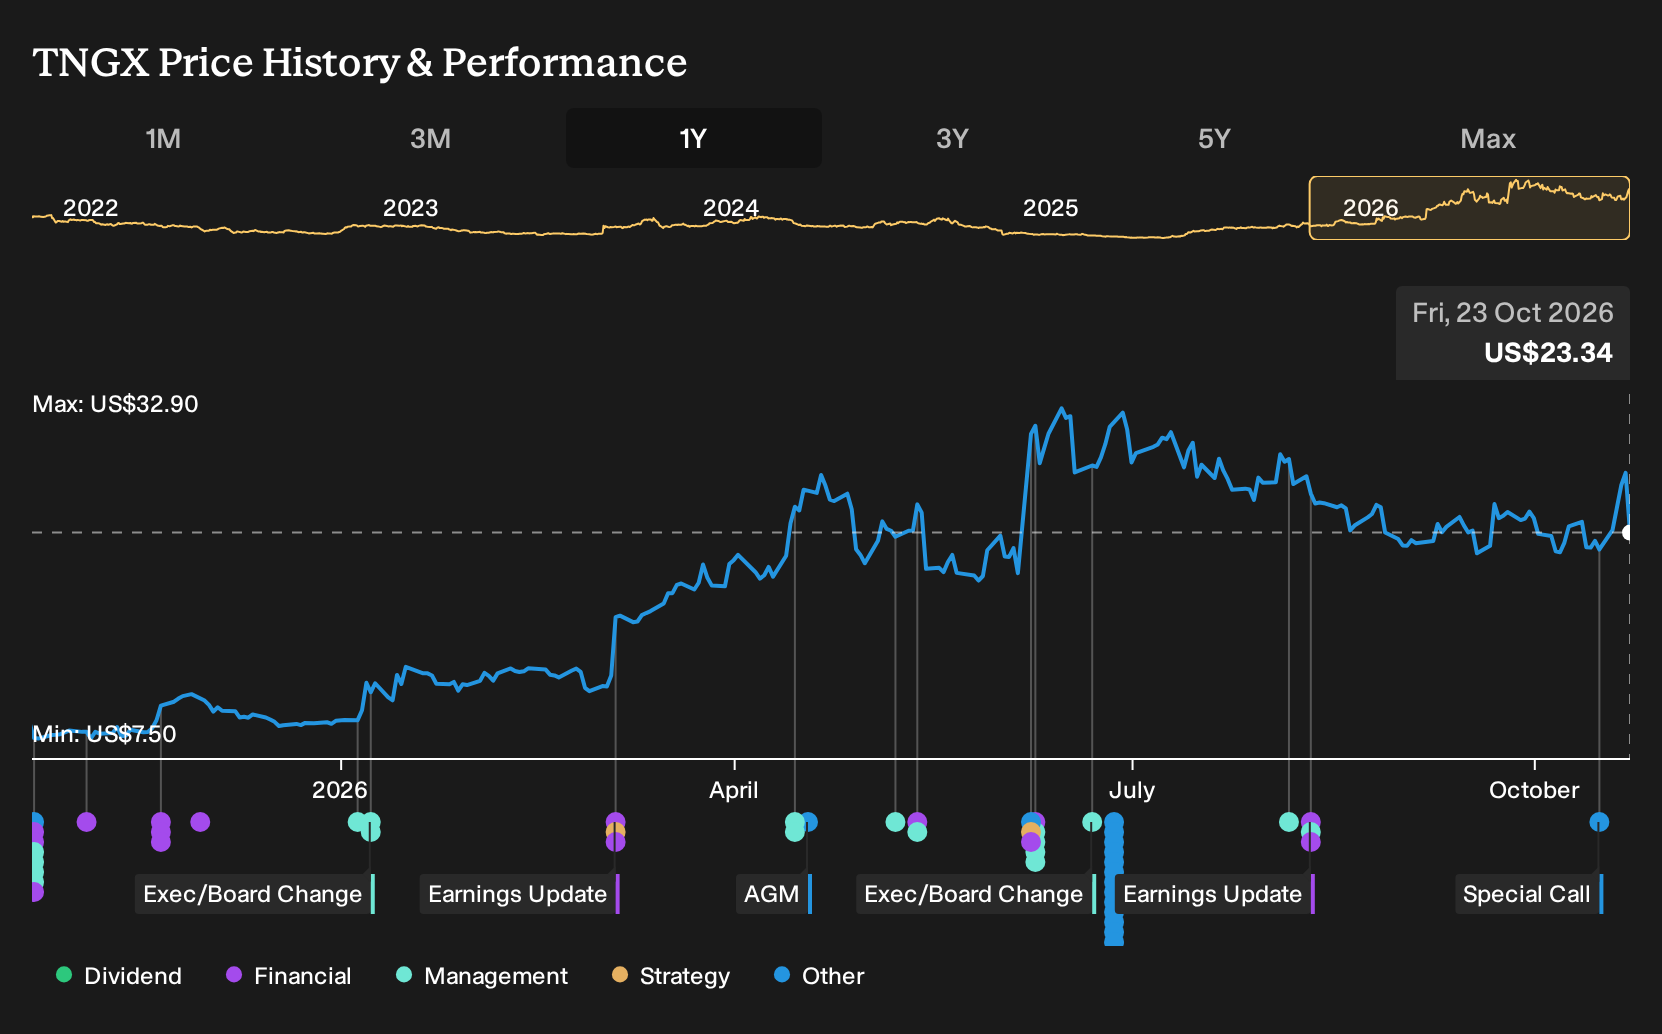
Uncover why Tango Therapeutics' fair value indicates a 102% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most bullish analysts focus less on trial execution risk and more on how broad MTAP coverage could change Tango Therapeutics’ ceiling. Before this vopimetostat update, that group was already penciling in about US$278.6 million of 2029 revenue and US$48.0 million of earnings. That is far above consensus, and the new data may push those narratives to evolve again, in either direction.
Explore 2 other Tango Therapeutics fair value estimates, including one that suggests as much as 102% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your Tango Therapeutics research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Tango Therapeutics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Tango Therapeutics' overall financial health at a glance.
Looking For More Investment Ideas Beyond Tango Therapeutics?
If Tango Therapeutics has sharpened your interest in oncology and high conviction stories, it can help to widen the lens and compare it with other stocks filtered on hard data instead of headlines. The Simply Wall St Screener gives you a quick way to scan for different types of opportunities that might sit alongside or instead of a focused biotech position.
- For investors who want growth potential but still care about balance sheet strength, consider screening for a list of solid balance sheet and fundamentals (24 results) that can better withstand tough conditions.
- If you prefer to lean into quality at a discount, use the Screener to surface a 28 high quality undervalued stocks that may align more closely with your risk and return expectations.
- Those looking for differentiated prospects with less crowding can cast a wider net through a 21 high quality undiscovered gems that focuses on fundamentals rather than headlines.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com