
What Richardson Electronics Doubters Missed
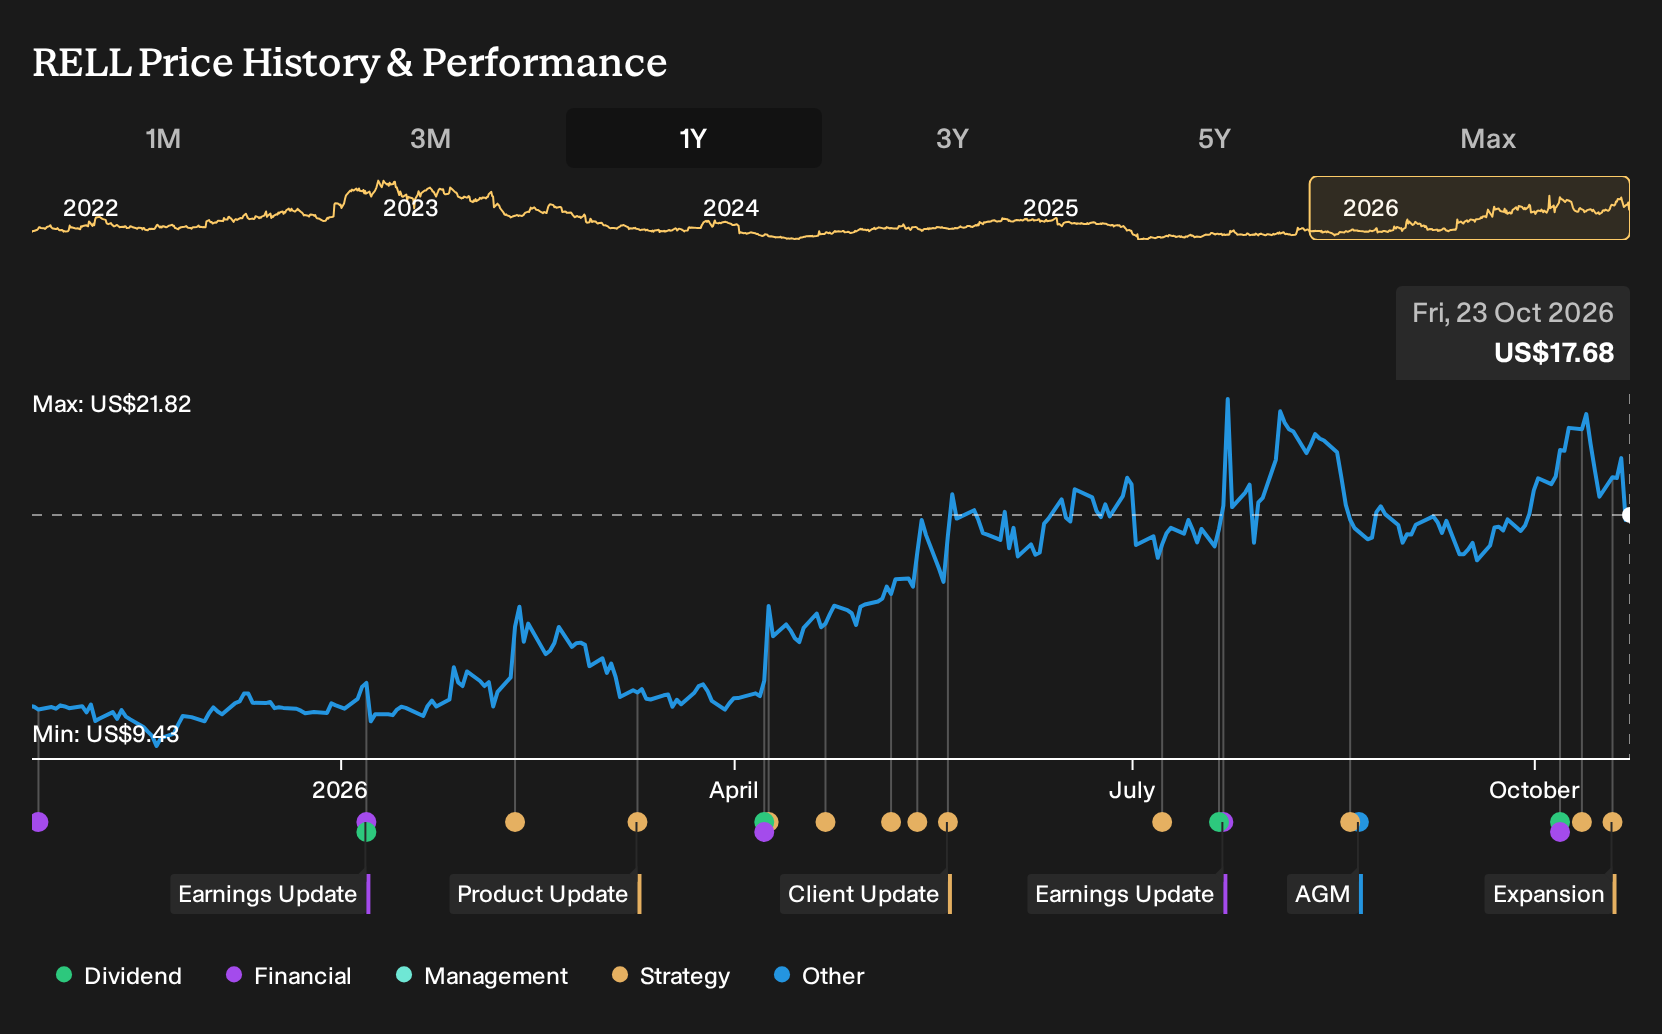
If Richardson Electronics looked like a niche supplier stuck between aging tube products and new energy hardware back in October 2025, the past 12 months told a very different story. For Richardson Electronics shareholders, the return over the past year was 66.4%, including dividends. If you had been weighing rising electrification demand against fears of digital obsolescence at that time, how would you have judged that balance using only the record at hand?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
Richardson Electronics is not the only name tied to this theme. Zero in on 42 power grid technology and infrastructure stocks and compare how each one is priced.
The Two Richardson Electronics Stories Investors Had To Weigh
The shares cost US$10.83 at the start of the period, and anyone looking at Richardson Electronics then had to choose which story felt more convincing.
The bullish narrative put fair value at US$11.50, based on the idea that rising electrification and automation would support demand for engineered energy and display products. It also assumed that investment in proprietary, higher margin hardware could improve profitability.
The bearish view set fair value at US$10, warning that rapid digitalization and solid state technology might shrink the legacy tube market and leave Richardson exposed to cheaper Asian rivals and revenue concentration risk.
What The Results Changed For Richardson Electronics
The key development was Richardson Electronics expanding manufacturing of battery energy storage systems with ComEd and planning Illinois' largest commercial installation. This supported the focus on electrification and energy hardware. Q1 2027 results also showed revenue at US$64.923m and net income at US$4.059m, with net margin at 6.3% versus 3.5% a year earlier. Overall, the period aligned more with the optimistic case than the cautious one.
The lesson to carry to other stocks is simple. When a thesis leans on new segments offsetting legacy risk, track two things together: whether new project wins actually land and whether net margin moves in line with that story in the following results.
What Richardson Electronics' 66% Run Now Asks You To Believe
Richardson Electronics now trades at US$17.68, and the selected Narrative argues that its Fair Value sits above that quote. The focus has shifted from whether tubes are dying to whether higher value power and display programs can carry more of the load.
The Narrative concentrates on how much of the firm’s growing backlog and engineered product mix will actually turn into steadier earnings. It argues that today's price still does not fully credit successful conversion of that order book into margins that hold without tariff refunds.
"The main requirement for the company is continued execution on higher value engineered offerings such as BESS, wind power management, semiconductor and RF components, and custom displays so that these programs translate a growing backlog and pipeline into sustained, profitable growth that offsets healthcare CT tube losses and GES volatility."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Find Your Own Contrarian Opportunity
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 24% below our estimate - embeds conversational AI helpers into existing enterprise office and collaboration software.
- Company 2 - 29% below our estimate - folds field diagnostics and grid monitoring tools into one utility control layer.
- Company 3 - 42% below our estimate - shifts from buying finished film stock to owning integrated production and logistics capacity.
Three companies from the same screener. Open every one of the 28 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com