
3 Defensive Dividend Stocks for a Hawkish Fed and Sticky Inflation
Fed officials are hinting at a hawkish pause, inflation readings are still running hot and cash parked on the sidelines is losing spending power every month. That mix is pulling attention back toward large US dividend stocks that aim to pay investors regularly while trying to smooth out some of the rate noise. This article walks through three defensive dividend picks from our screener that appear most exposed to this latest Fed twist.
The three stocks covered below are just a small sample of this idea, and the full screen surfaced 23 more large-cap defensive dividend companies with similarly detailed narratives that are not unpacked in this article. To identify potential fits for your watchlist and analyze their income strength and balance sheet resilience side by side, head straight into the Large-Cap U.S. Defensive Dividend Stocks screener.
Elevance Health (ELV)
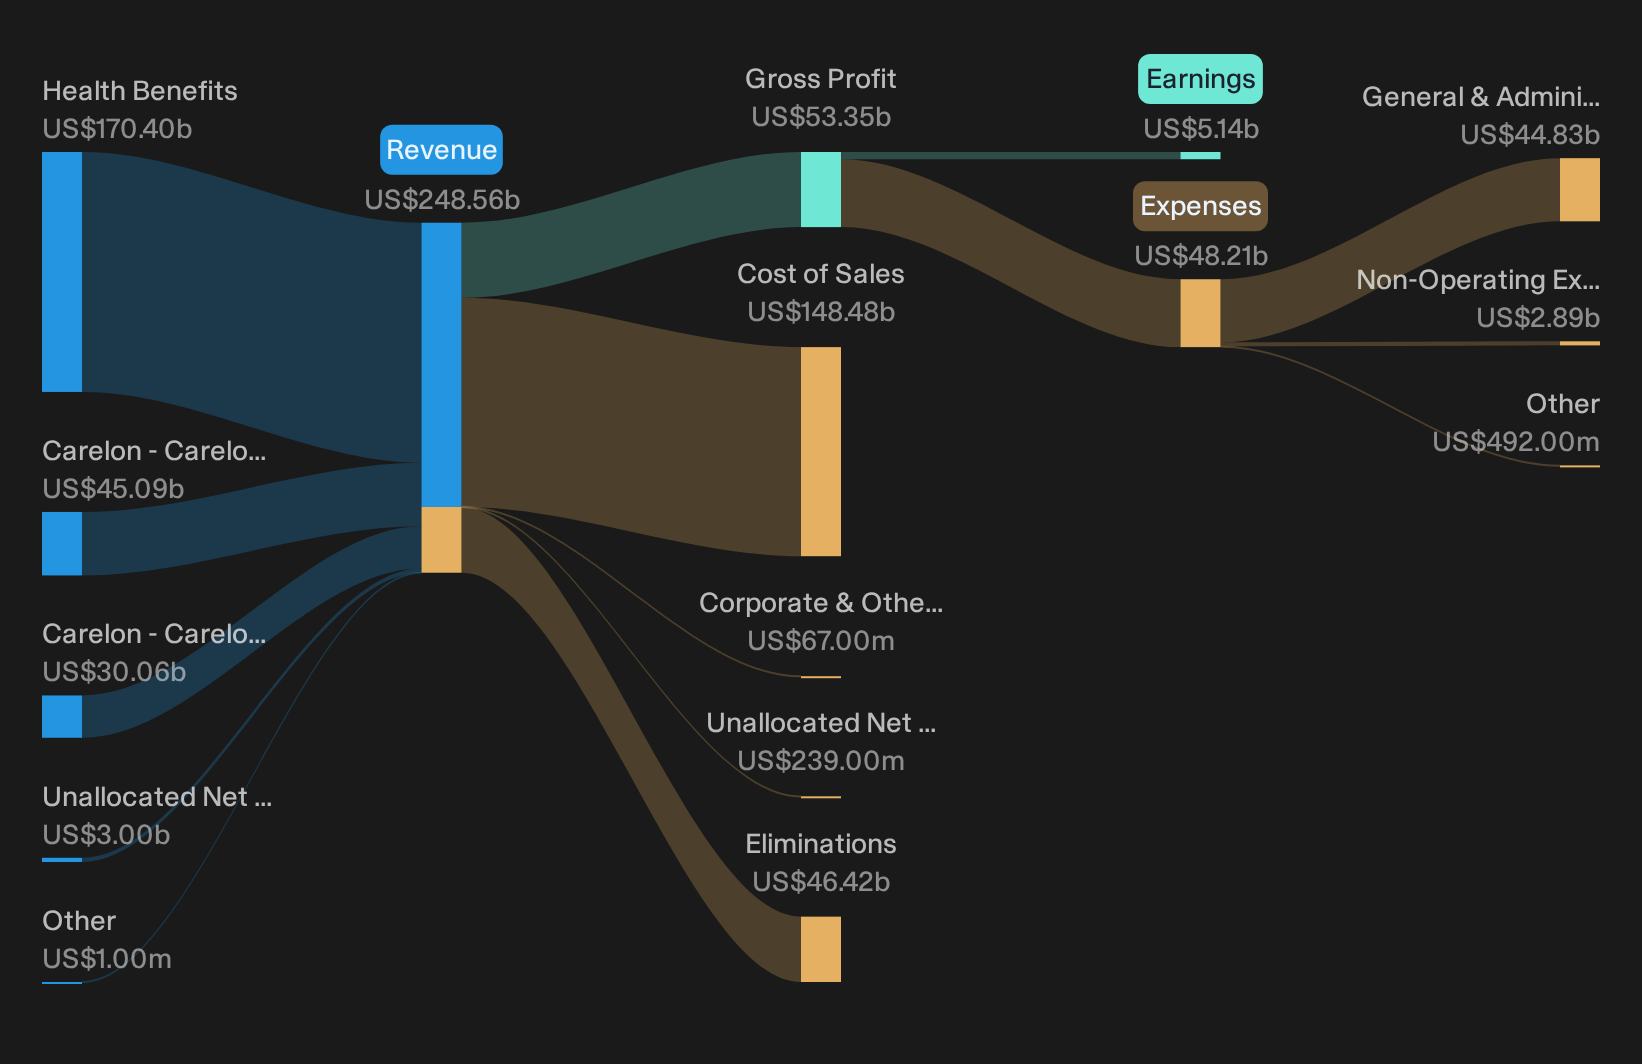
Overview: Elevance Health is a large U.S. health benefits provider that sells medical coverage and related pharmacy and care services to individuals, employers and government programs.
Operations: Elevance Health generates about US$170.4b from Health Benefits and US$75.2b from Carelon pharmacy and services, almost entirely in the United States.
Market Cap: US$95.1b
Elevance Health fits this defensive dividend screen because its core health insurance and services rely on recurring premiums and fees that tend to be steadier when rates stay higher for longer.
"Planned exits from Medicaid markets where Elevance Health does not see a path to sustainable performance, combined with efforts to improve rate alignment and mature care management in remaining contracts, is intended to move Medicaid operating margins higher from the expected 2026 trough and support longer term earnings quality."
What happens if a single unseen pressure on Elevance Health’s medical cost trend breaks differently will likely matter a lot for future margins.
That margin swing is exactly what the full narrative for Elevance Health unpacks, showing how Elevance Health’s Medicaid reset could be masking upside in earnings quality.
Otter Tail (OTTR)
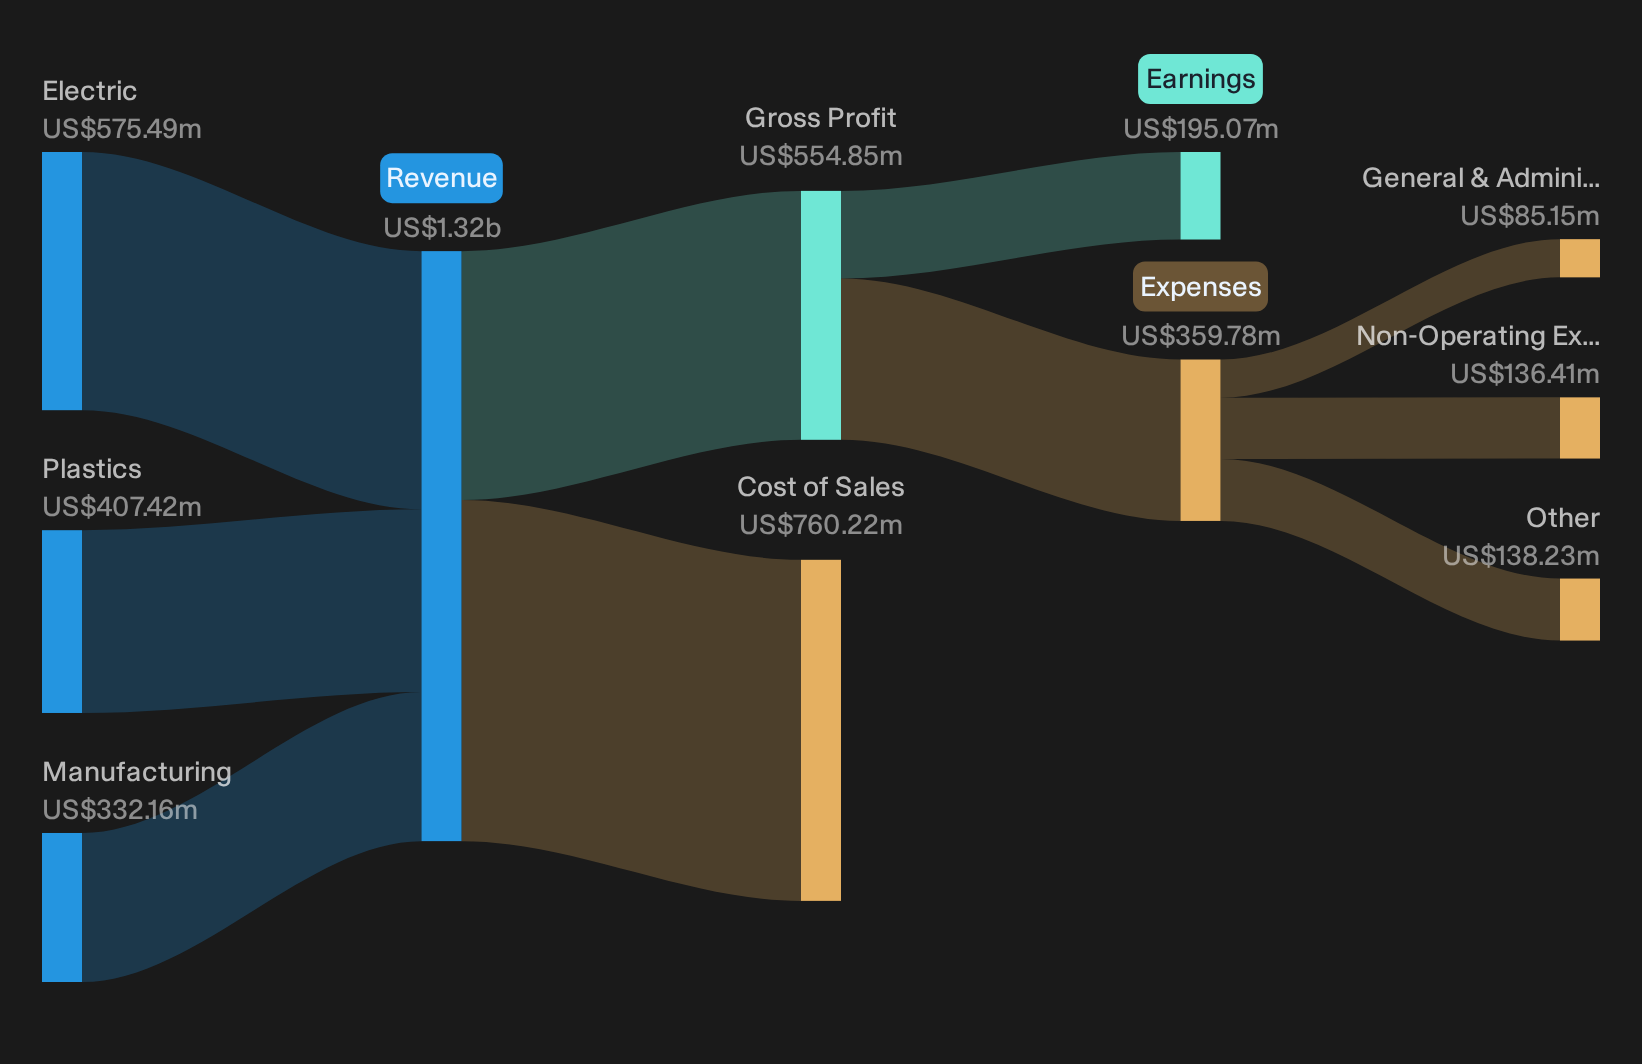
Overview: Otter Tail runs a regulated electric utility alongside plastics and manufacturing operations, giving investors a dividend-focused, infrastructure-heavy business anchored in essential U.S. services.
Operations: Otter Tail generates about US$575 million from Electric, US$407 million from Plastics and US$332 million from Manufacturing activities.
Market Cap: US$3.8b
Otter Tail fits this defensive dividend screen because its regulated power business, paired with steady industrial earnings, targets predictable cash flows even when rates stay higher for longer.
"Continued execution of Otter Tail’s US$1.9b electric capital program, with a reaffirmed 10% rate base CAGR and nearly 1:1 conversion of that rate base growth into utility earnings, is expected to support future EPS."
What happens if a single key assumption about how that capital is funded and recovered through customer bills breaks could reshape the whole earnings path.
If that funding risk matters to you, read the full narrative for Otter Tail to see how Otter Tail’s capital plan could accelerate or stall returns for long term holders.
American States Water (AWR)
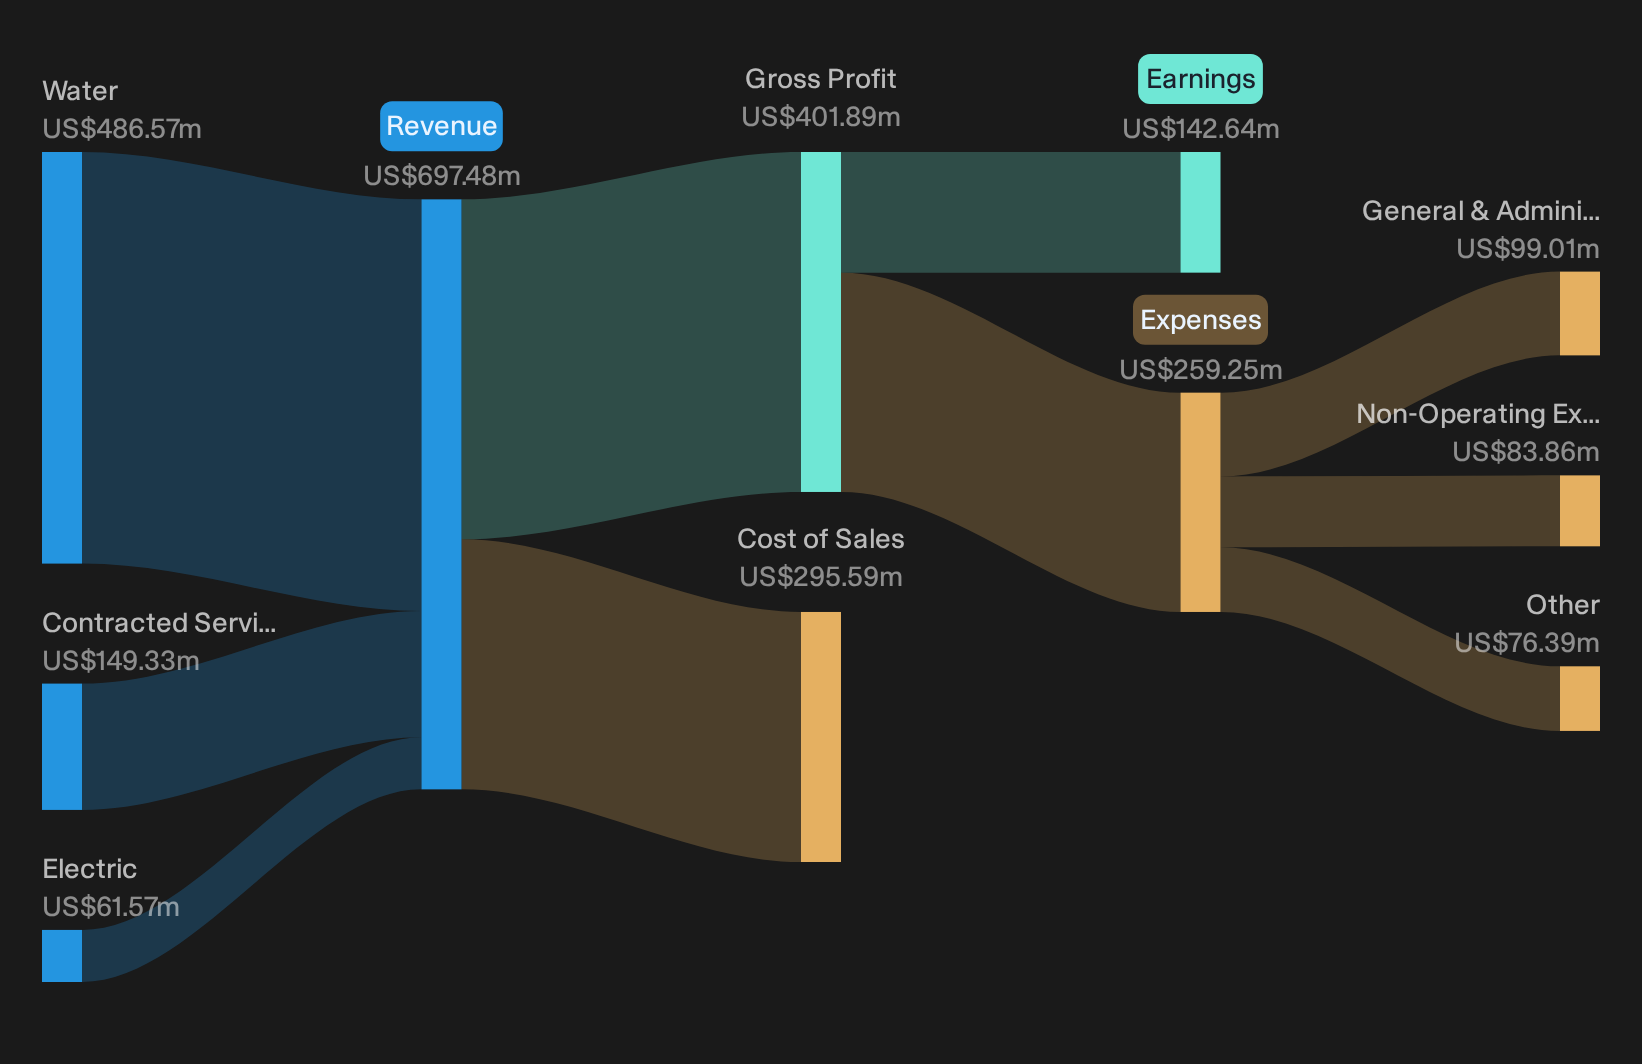
Overview: American States Water provides regulated water, wastewater and electric utility services to households, businesses and military sites across the United States.
Operations: American States Water generates about US$486 million from Water, US$62 million from Electric and US$149 million from Contracted Services, all in the United States.
Market Cap: US$3.4b
American States Water fits this defensive dividend screen as a regulated utility that aims to pair essential services with a long running income profile. This can look appealing when the Fed leans hawkish and investors favor steadier cash flows over more volatile rate sensitive ideas.
"The shift to new CPUC mechanisms such as MRAM and the incremental supply balancing account from 2025 introduces more direct exposure to customer usage and supply mix, which can translate higher consumption and more efficient sourcing into stronger revenue and net margins in favorable periods."
What happens if one core assumption about how those California mechanisms balance usage swings against earnings stability breaks will matter a lot for future dividend comfort.
If that balance between usage swings and earnings comfort is the question on your mind, the full narrative for American States Water shows where American States Water’s risk and income story could be decoupling.
Seeking Alternatives Before Momentum Flies
Fresh stock ideas can move from quiet to crowded fast. Screens catch potential breakouts while they are still under the radar for now. Act now.
- Catch early movers with strong balance sheets by scanning the curated list of solid balance sheet and fundamentals (24 results) before the momentum trade gets crowded and pricing power starts slipping away.
- Ride powerful trends in automation by tracking screened 94 robotics and automation stocks that may be building revenue momentum while attention is still dropping elsewhere.
- Position ahead of potential rate-sensitive shifts by reviewing the targeted 5 dividend fortresses while income ideas remain mispriced and yields stay above the crowd.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com