
Is International Petroleum (TSX:IPCO) Overvalued After A 5 Year Rally?
International Petroleum has delivered a very strong share price run in recent years, which naturally raises a pointed question for anyone looking at the stock today. Is the current price really supported by the revenue the business is generating, or have investors moved ahead of its sales base?
- Over the past 5 years the share price has returned about 4.6x, which puts real pressure on the question of how much sales can justify in terms of valuation.
- The group’s ability to convert its oil and gas operations into steady top line and cash inflows can influence how much investors are willing to pay for each dollar of revenue.
- The analysts covering International Petroleum have run their own numbers. See what analysts think International Petroleum's shares could be worth.
The issue now is whether International Petroleum’s recent share price level, after such a long stretch of gains, is adequately backed by its sales when set against the Fair Ratio benchmark.
If you are weighing whether International Petroleum’s 459.6% five year return is justified by its sales, it can also help to compare that question with 3 high quality undervalued stocks.
Does International Petroleum Look Pricey on Sales?
For International Petroleum, the P/S ratio fits neatly because investors often focus on revenue metrics for resource producers where earnings can swing with commodity prices.
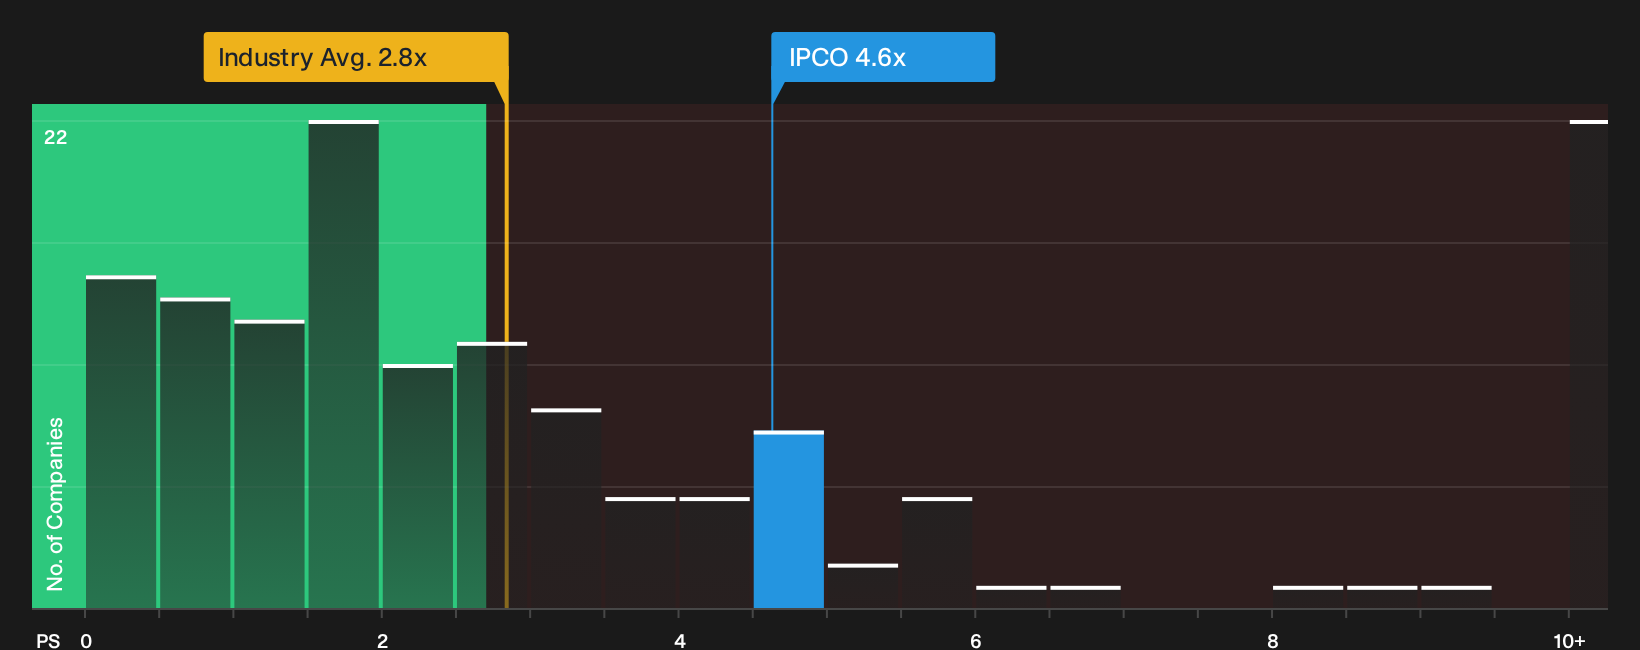
The stock trades on a P/S of 4.6x, which is higher than the Oil and Gas industry average of about 2.8x and a little below the peer group on roughly 5.3x. On a tailored Fair Ratio that blends the company’s own growth profile, profitability, size and risk, International Petroleum screens as overvalued on sales at the current level.
That mix means investors are paying a premium versus the broader sector but not an extreme one relative to closer peers. Anyone assessing the shares needs to decide whether the revenue quality and project pipeline justify that pricing gap. Explore the numbers behind International Petroleum's P/S valuation.
The International Petroleum Narrative: What Would Justify Today's Price?
Narratives pick up where the P/S debate leaves off for International Petroleum, spelling out the specific paths for future revenue, margins and earnings that would need to play out for the shares to look meaningfully higher or lower than today’s level, and they sit on Simply Wall St’s Community page. Instead of a single output from a model or ratio, they map the underlying assumptions so you can watch in real time whether those conditions actually show up in the business.
The International Petroleum community is divided between those who see the current price as roughly aligned with the company’s narrative and those who are more cautious about execution and cash generation.
Bull case: roughly fairly valued
"Completion of Blackrod Phase 1 and favorable market conditions are positioned to boost long-term revenue, margins, and cash flow stability…"
Discover why this Narrative puts International Petroleum at roughly fairly valued.
Bear case: 12% overvalued
"Any delay or underperformance in reaching commercial oil production could leave the company with higher capital tied up for longer…"
Explore why this Narrative puts International Petroleum at 12% overvalued.
One more piece of the International Petroleum puzzle before you move on
Before you lean too much on today’s multiples or recent share performance, it helps to see where professional analysts think this business could be a few years from now, and how that compares with the current setup. Explore where analysts expect International Petroleum to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com