
Lamb Weston Holdings (LW) Rebound Puts Its Valuation Back In Focus
Lamb Weston Holdings: Recent Performance Snapshot
Lamb Weston Holdings (LW) has drawn fresh attention after a recent move in its share price, with the stock closing at US$53.83 on 17 October 2026. Investors are weighing shorter term gains against weaker longer term returns.
Recent trading in Lamb Weston Holdings has been choppy. The stock has a 30 day share price return of 23.52% and a year to date share price gain of 27.29%. However, the 1 year total shareholder return is down 16.64%, which points to momentum rebuilding after a weaker stretch.
Scan beyond Lamb Weston Holdings and see how other food and consumer staples players with rebuilding momentum stack up in the 28 high quality undervalued stocks.
Lamb Weston Holdings has rebounded sharply over the past month, yet multi year shareholders are still sitting on weaker returns. Does that recent surge represent a sensible entry point, or does it skew the risk reward toward sellers taking profits?
Most Popular Narrative: 12% Overvalued
Lamb Weston Holdings closed at $53.83, while the most followed narrative on the stock pins fair value at $48.06, which frames the recent share price recovery as running ahead of that estimate.
The international segment is where the framing has moved the most. Mike Smith attributed EMEA weakness to a slowdown in demand and said the company was “controlling the controllables” while it worked through the Netherlands closures. The call now places the cause on supply. Mike Smith calls the European crop “a tale of two years,” argues that raw potato quality and yield “is likely going to be the limiter,” and says “not all open industry capacity will be used.”
See why 2 investors see Lamb Weston Holdings as 12% overvalued.
Result: Fair Value of $48.06 (OVERVALUED)
Still, the international crop constraints and slower QSR traffic that management flagged could pressure Lamb Weston Holdings if those headwinds persist for an extended period.
Find out about the key risks to this Lamb Weston Holdings narrative.
Another View: Cash Flows Point a Different Way
The earlier narrative framed Lamb Weston Holdings as 12% overvalued at $53.83 against a $48.06 fair value. A different tool tells a very different story. Our DCF model estimates the future cash flow value at $138.49, which makes the current share price look materially undervalued on that measure.
The gap between a $48.06 fair value and a $138.49 cash flow estimate raises a blunt question for investors. Which set of assumptions do you trust more when the same stock is tagged as both expensive and cheap at the same time?
Look into how the SWS DCF model arrives at its fair value.
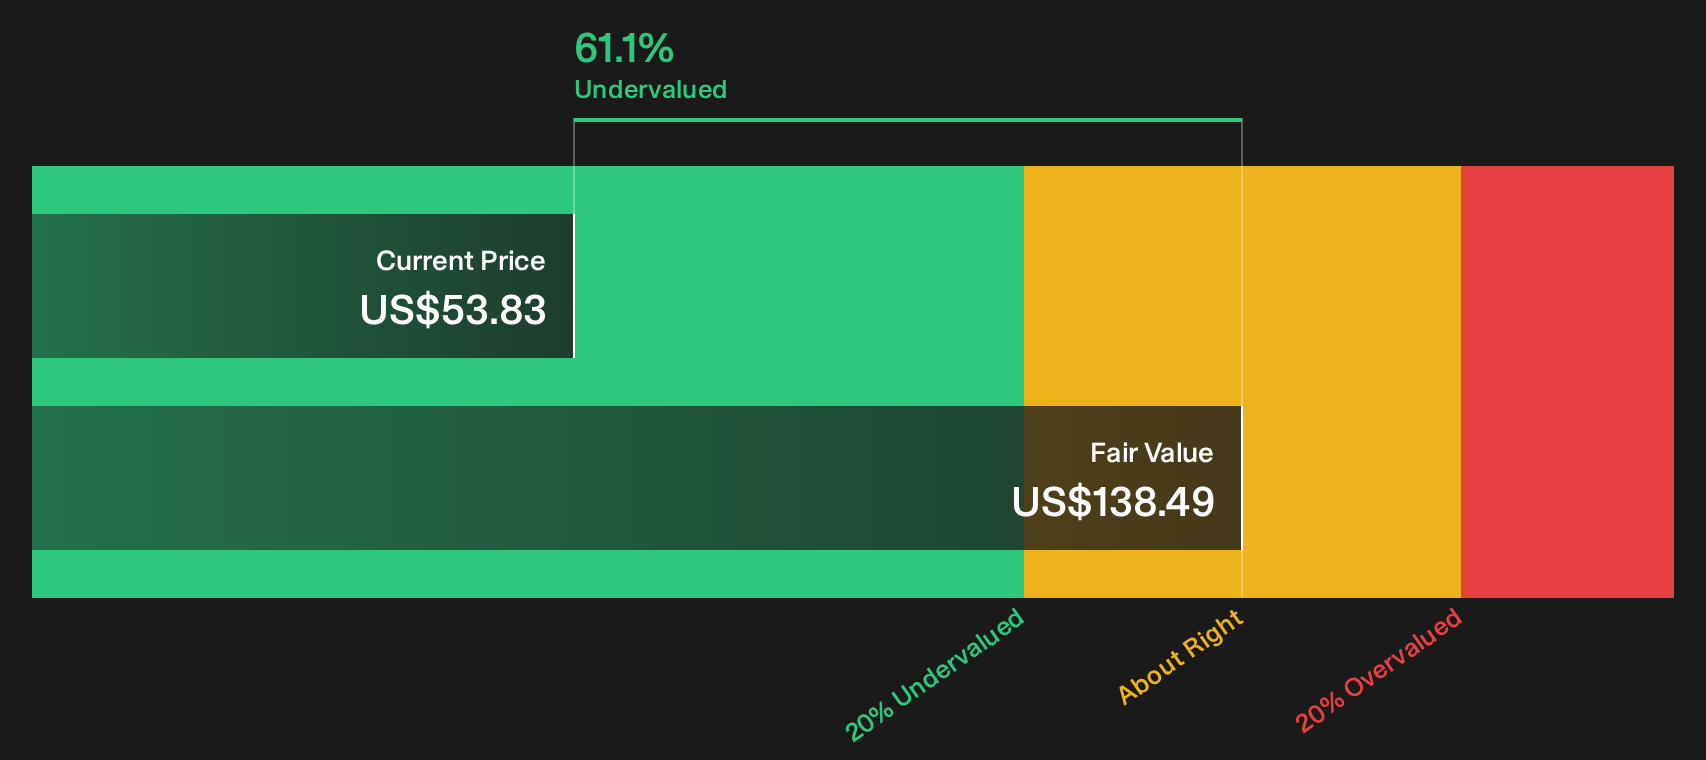
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Lamb Weston Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Lamb Weston Holdings after a sharp rebound and conflicting valuation tools can feel messy. Move fast, dig into the underlying numbers, and weigh both the upside and the red flags by checking the 3 key rewards and 2 important warning signs.
Looking for more Lamb Weston Holdings style ideas?
If Lamb Weston Holdings has you thinking harder about risk and reward, use this momentum to broaden your watchlist before the next move passes you by.
- Target resilient income by focusing on companies that combine higher yields with robust fundamentals through the 5 dividend fortresses.
- Hunt for stronger balance sheets by scanning financially sound businesses that score well on debt and liquidity with the list of solid balance sheet and fundamentals (24 results).
- Spot tomorrow's potential leaders early by reviewing financially healthy smaller players highlighted in the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com