
IDACORP (IDA) Could Be 7% Undervalued Following Its Dividend Increase
IDACORP (IDA) has put fresh emphasis on income today by declaring a quarterly dividend of US$0.90 per share, payable on November 30, 2026, to shareholders of record as of November 5.
At a share price of US$140.68, IDACORP has seen short term momentum build recently, with a 7 day share price return of 3.39% and a 30 day share price return of 8.40%, even though the 90 day share price return is down 5.36% and the 1 year total shareholder return sits at 5.69%. This compares with a much stronger 3 year total shareholder return of 63.23% and 5 year total shareholder return of 52.41%, suggesting the dividend increase lands against a backdrop of solid longer term wealth creation but some mixed shorter term sentiment.
Scan beyond IDACORP and shortlist other income-focused utilities with resilient returns and consistent shareholder payouts using our hand picked 5 dividend fortresses
The stock now trades around 7% below the average analyst target, while IDACORP’s own intrinsic value estimate points in the opposite direction. Is the recent dividend-fueled bounce still too cautious, or already generous?
Most Popular Narrative: 7% Undervalued
Against IDACORP’s last close at $140.68, the most followed narrative points to a fair value of about $151.44, which implies a modest valuation gap built on long term load growth and heavy grid investment.
Massive planned capital investments, with IDACORP expecting to spend between US$1.3b and US$1.5b on CapEx in 2026 and around US$7b from 2026 to 2030 on generation, storage and transmission projects such as B2H and SWIP North, are forecast to drive rate base from about US$5.3b in 2025 to around US$11b by 2030 and increase regulated earnings.
See why 4 investors see IDACORP as 7% undervalued.
Result: Fair Value of $151.44 (UNDERVALUED)
Still, the IDACORP story leans heavily on large industrial demand and smooth regulatory cost recovery, so weaker hydropower conditions or tighter rate decisions could quickly challenge this undervaluation pitch.
Find out about the key risks to this IDACORP narrative.
Another View On IDACORP’s Valuation
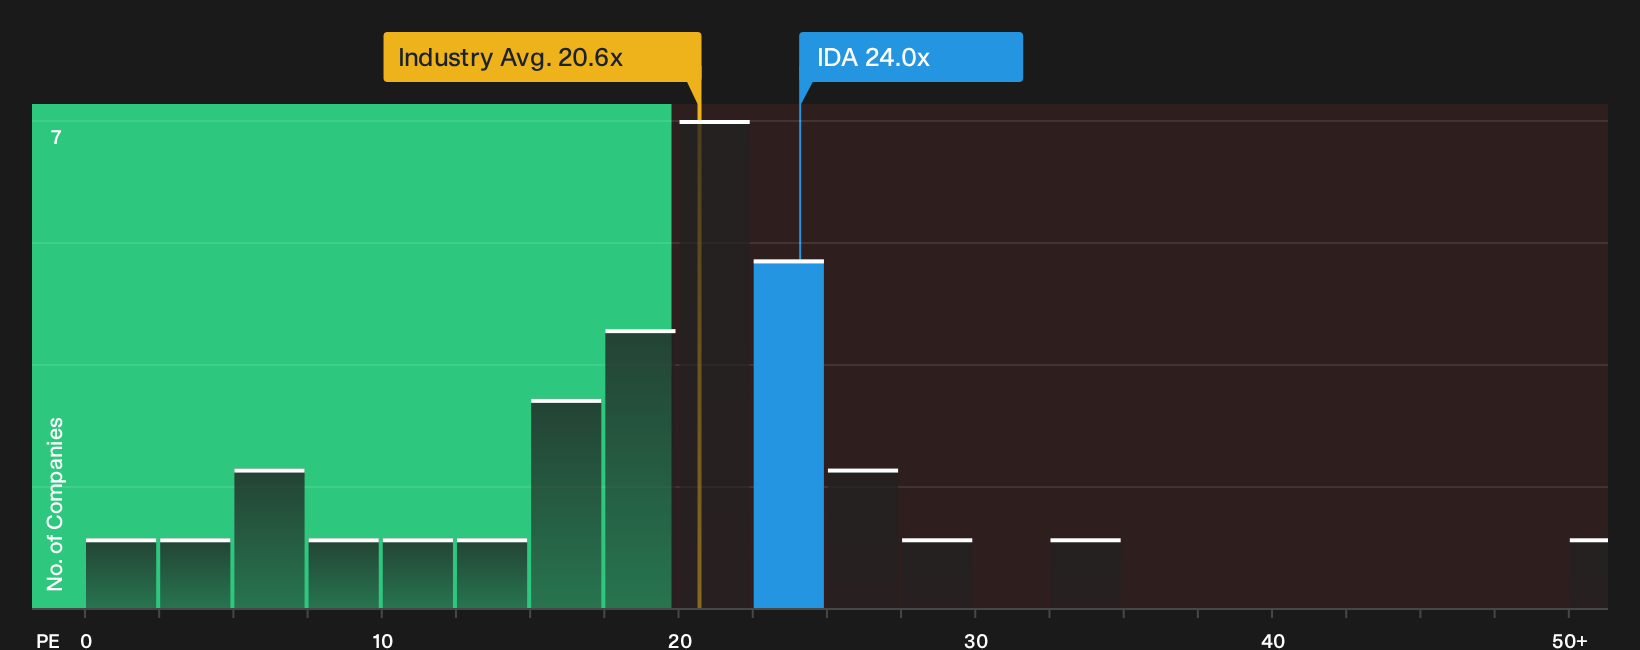
On the flip side of the “7% undervalued” story, IDACORP’s current P/E of 24x screens as expensive compared with the US Electric Utilities industry on 20.6x, its peer group on 23.7x, and a fair ratio of 20.2x. That gap points to less room for error if growth or regulation disappoints, so which signal do you trust more?
See what the numbers say about this price, find out in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on IDACORP’s valuation story so far. If you want a clear view quickly, compare the potential upside and downside for yourself with 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond IDACORP?
If IDACORP has you thinking more broadly about income and resilience, use this moment to widen your watchlist with a few focused stock ideas.
- Target stronger income durability by filtering for companies that appear in our 5 dividend fortresses so you can compare yields with balance sheet strength upfront.
- Hunt for potential mispricing by scanning our 28 high quality undervalued stocks and see which businesses combine quality metrics with market skepticism.
- Prioritize capital protection first by reviewing the 30 resilient stocks with low risk scores which highlights businesses with more resilient risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com