
3 UK Bank Stocks With Earnings Tied Closely To Higher Interest Rates
With the Bank of England signalling that higher interest rates could soon bite, UK financials are suddenly on center stage again. Rising borrowing costs can reshape which businesses quietly collect more income on their loans and which ones feel squeezed. This article breaks down how that backdrop links to three UK Domestic Banks and Financials Benefiting from Rising Interest Rates screener stocks, and why their exposure to this news event deserves a closer look right now.
The stocks highlighted below are only a sample, and the full screen surfaced 8 more UK domestic banks and financial firms with equally compelling rate-related stories that are not covered in this article. To identify potential high-conviction ideas tailored to your own view on higher Bank of England rates, head straight into the UK Domestic Banks and Financials Benefiting from Rising Interest Rates screener.
Lloyds Banking Group (LSE:LLOY)
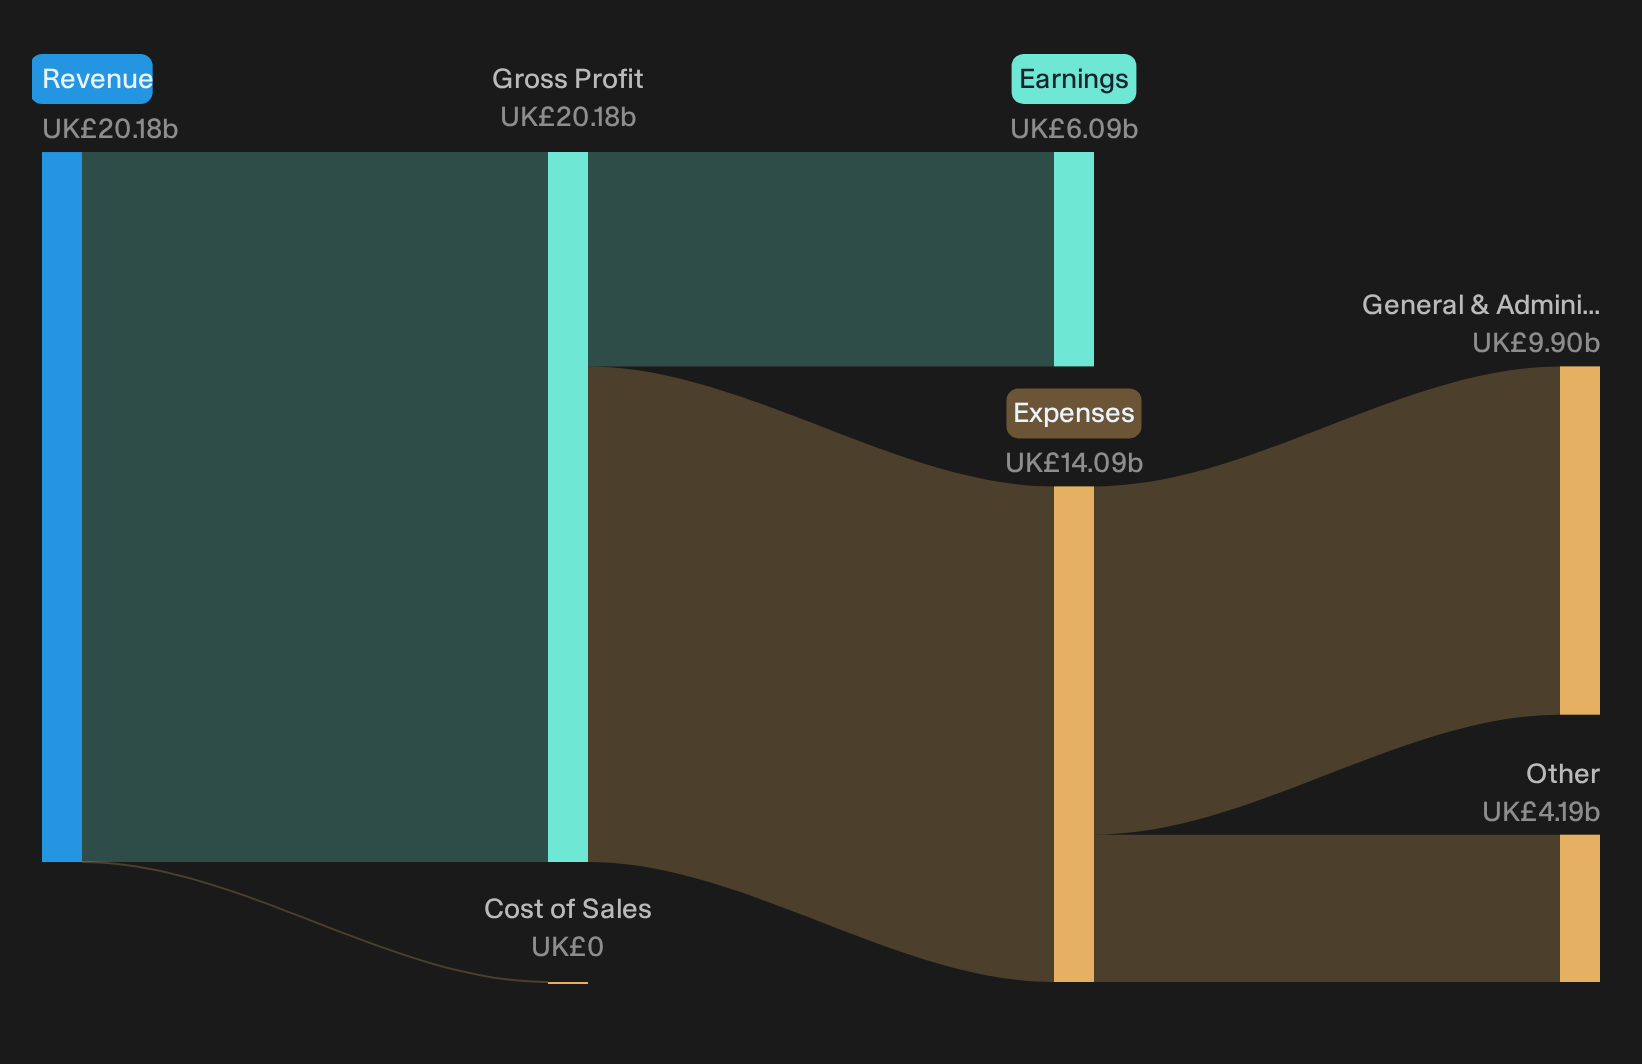
Overview: Lloyds Banking Group is a UK focused retail and commercial lender that earns most of its money from everyday banking, mortgages and financial services closely linked to Bank of England interest rates.
Market Cap: £57.5b
Lloyds Banking Group gives you one of the clearest pure plays on UK interest rate moves, with everyday current accounts, mortgages and small business lending all closely tied to what the Bank of England does next.
"Lloyds Banking Group is moving into a new four year Accelerate 2030 plan that targets mid single digit net income growth, high single digit fee income growth and a cost income ratio below 45% by 2030. The Accelerate 2030 plan leans heavily on AI and digital programmes to deliver about £2b of gross cost savings from 2027 to 2030 and to support high single digit growth in fee based income."
The real swing factor is how one pressure on its funding costs shakes out and filters through to future profit margins.
That pressure point is exactly what the full narrative for Lloyds Banking Group unpacks in detail, including where Accelerate 2030 could be masking both risk and upside.
Secure Trust Bank (LSE:STB)
Overview: Secure Trust Bank is a UK lender focused on consumer, real estate and commercial finance, giving concentrated exposure to domestic interest rate moves.
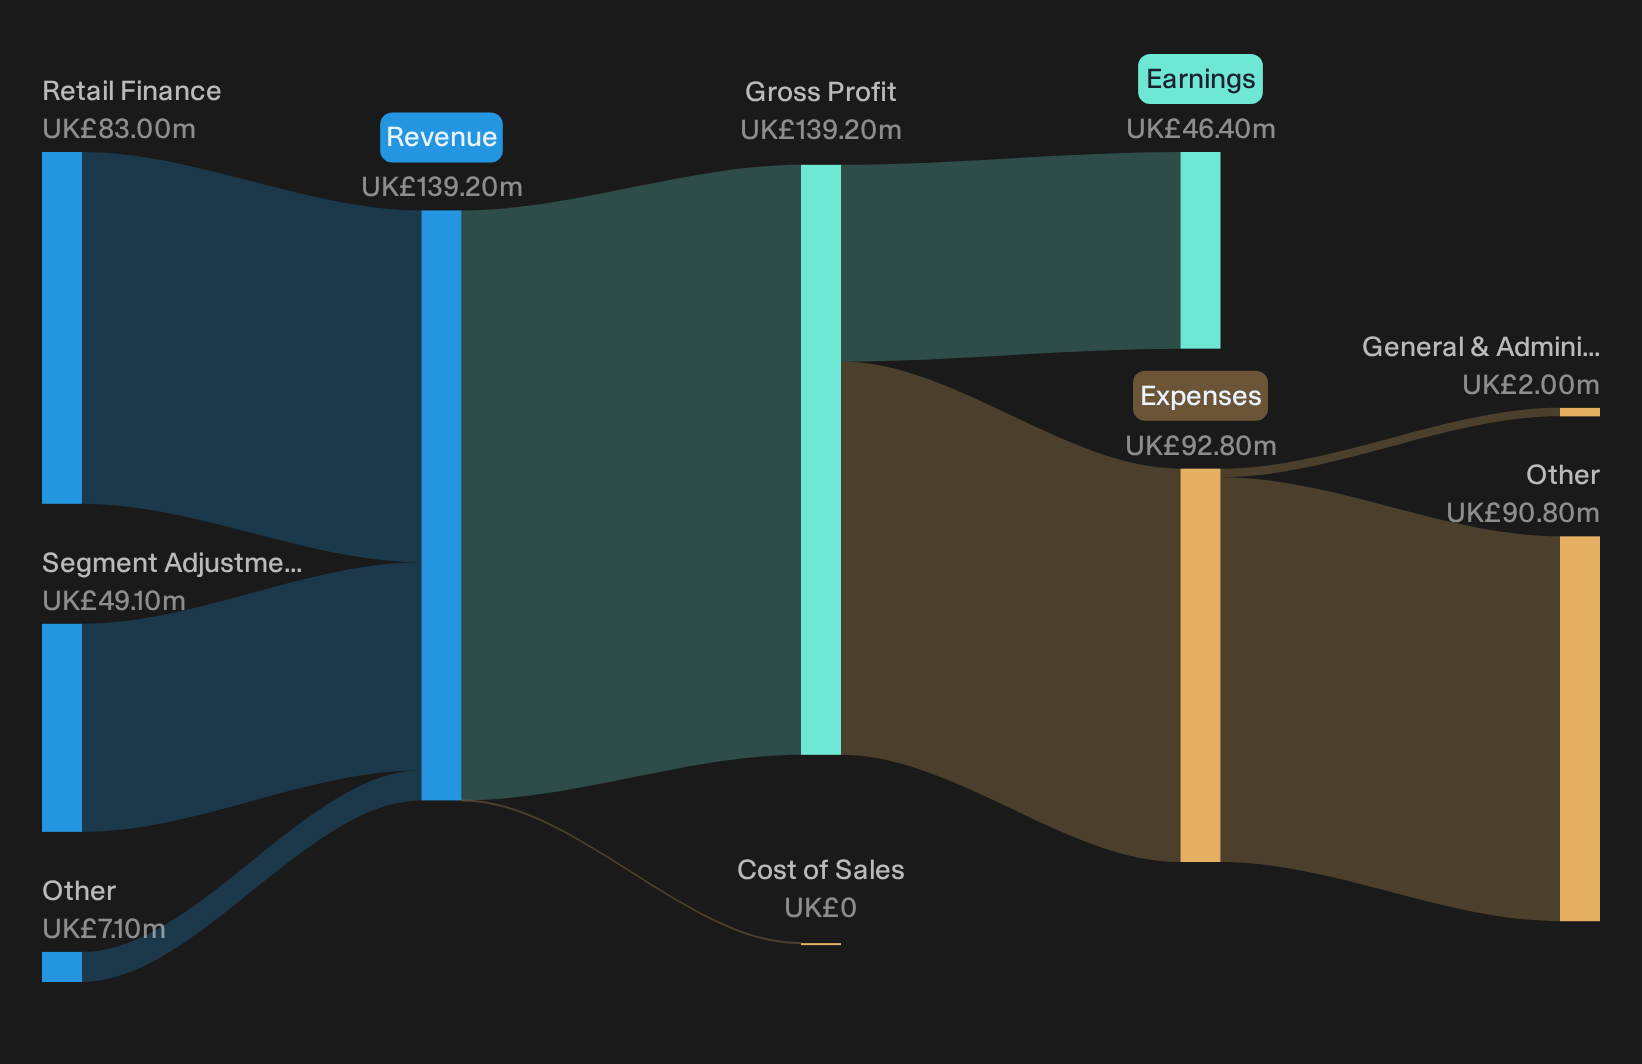
Operations: Secure Trust Bank generates £83 million from Retail Finance, £7.1 million from Other activities and £49.1 million from segment adjustments, all in the UK.
Market Cap: £253.1 million
Secure Trust Bank plugs directly into the screener theme because its lending and deposit engine is firmly anchored in the UK and closely tied to the cost of money the Bank of England sets, which is why management keeps stressing how carefully they track every shift in the rate cycle.
"The ongoing migration of customers to digital channels, such as the rapid adoption of the AppToPay mobile servicing app and enhanced online banking features, is driving efficiency gains, operational cost reductions, and better customer retention, with cost-income ratios continuing to improve toward a targeted range of 44 to 46%, supporting future net margin expansion."
What really moves the needle for Secure Trust Bank now is how one still developing pressure on credit quality interacts with that improving efficiency story.
That credit quality twist is exactly what the full narrative for Secure Trust Bank unpacks, separating temporary noise from the long term potential for Secure Trust Bank.
NatWest Group (LSE:NWG)
Overview: NatWest Group is a UK headquartered retail, private and commercial bank. Its largely domestic loans and deposits closely track Bank of England rate moves.
Operations: NatWest Group generates £6.3b from Retail Banking, £8.9b from Commercial & Institutional, £1.2b from Private Banking & Wealth Management and £385 million from Central Items & Other.
Market Cap: £49.9b
For investors focused on UK Domestic Banks and Financials Benefiting from Rising Interest Rates, NatWest Group offers a direct way to link a predominantly UK loan and deposit book to potential shifts in net interest income as Bank of England policy tightens.
"Completion of the Evelyn Partners acquisition at the end of June 2026, which more than doubled NatWest Group assets under management and administration to £131b and is expected to lift group fee income by about 20%, sets up a larger mix of capital light, recurring revenue that could support earnings resilience relative to pure interest income."
The real test now is how one emerging pressure on funding costs interacts with that richer fee mix to shape future margins.
How that funding squeeze interacts with NatWest Group fee income is exactly what the full narrative for NatWest Group sets out, including where markets may be mispricing both risk and upside.

Seeking Fresh Alternatives Beyond Banks?
Fresh opportunities rarely stay under the radar for long. By the time momentum is flying, ideal entry points can be gone. Review new ideas before the crowd and consider taking action in line with your strategy.
- Target reliable income streams by scanning 5 dividend fortresses that focus on durable payouts investors often consider when rates, inflation or volatility start shifting unexpectedly.
- Identify established tech momentum by reviewing 39 profitable AI stocks that aren't just burning cash where AI companies already generate earnings instead of prioritizing cash-burning strategies while attention moves to new themes.
- Explore the energy transition by checking 16 nuclear energy infrastructure stocks featuring power infrastructure businesses that may become more widely followed as policy developments and demand projections evolve.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com