
What Investors Got Wrong About Brightstar Lottery Before The Drop
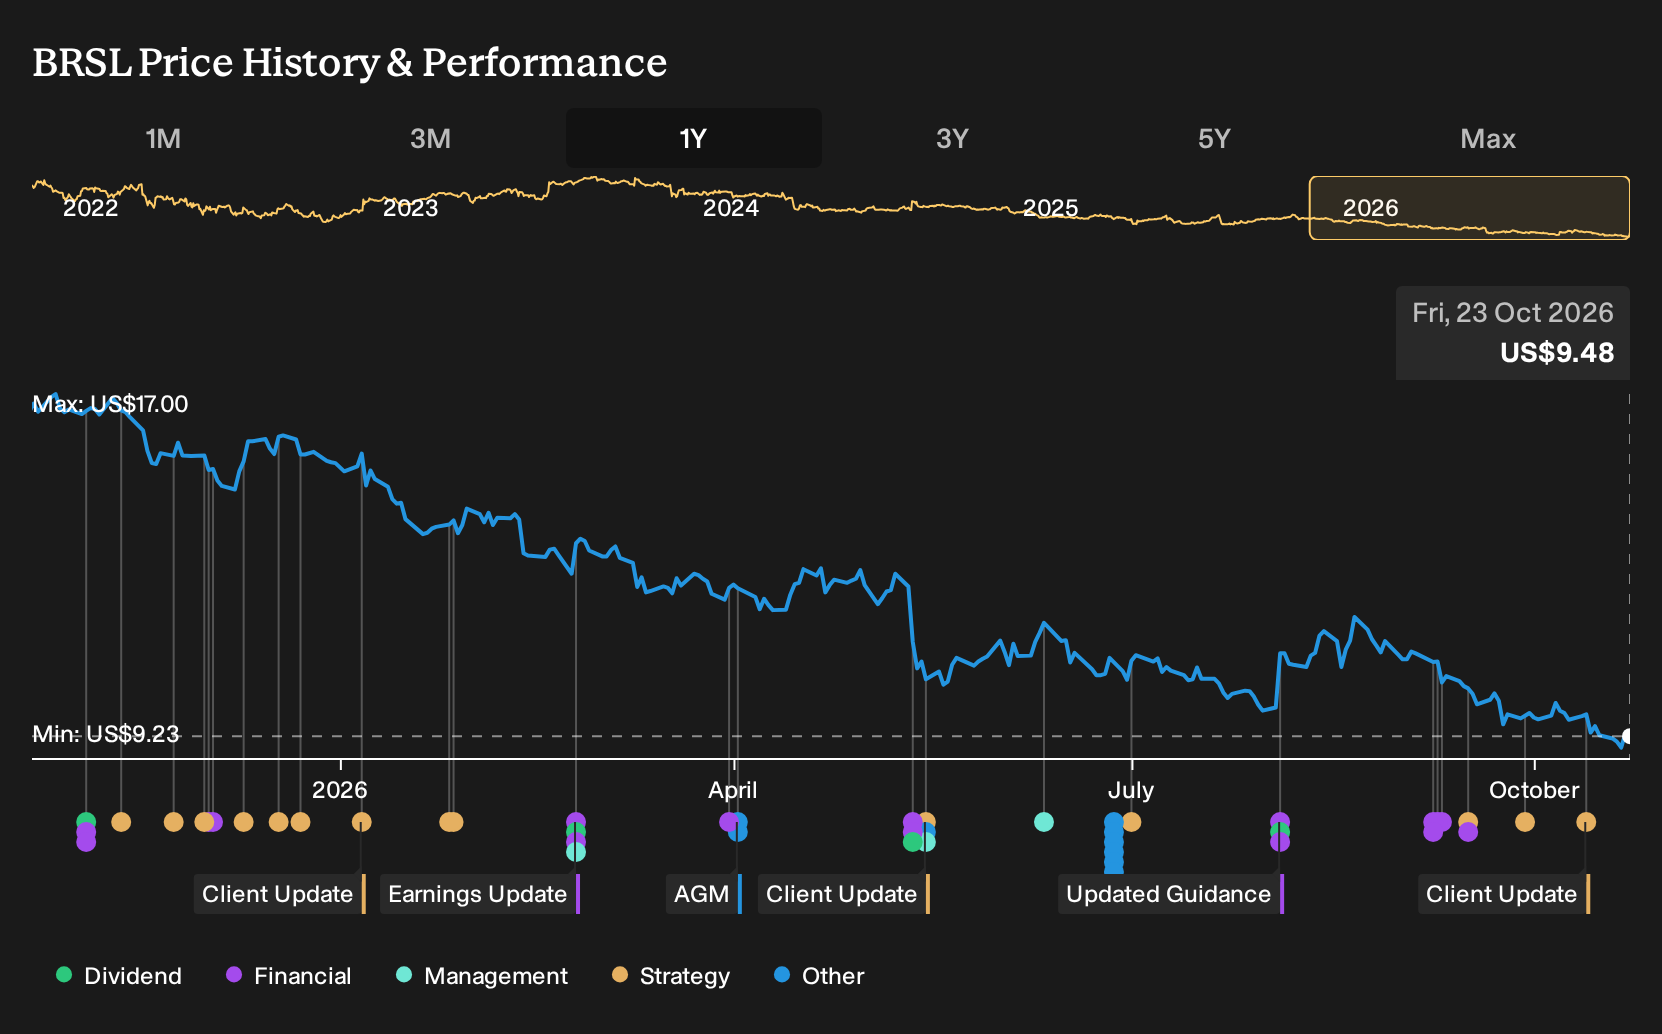
If you had paused on Brightstar Lottery after reading that contract renewals and digital channels could secure its future, the next twelve months might look especially painful. Holding Brightstar Lottery over the past year would have meant a 39.8% loss, including dividends. That is a large gap between hopeful projections and what actually happened. Which assumption in those upbeat forecasts about revenue stability, margins or contract-heavy spending would you have challenged at the time?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
If the move has made Brightstar Lottery harder to judge, start where the gap is still open and scan 28 high quality undervalued stocks.
The Argument You Would Have Been Weighing On Brightstar Lottery
The shares cost US$16.79 at the start of the period, so any opinion on Brightstar Lottery had to measure against that entry point.
The bullish narrative held that a Fair Value of US$18.52, about 10% above the start price, was reasonable if digital lottery growth and renewed contracts such as the Italy Lotto through 2034 kept revenue steady and margins improving.
The bearish view anchored on a Fair Value of US$12.52, about 25% below the start price, and focused on heavy capital needs for Italy and Texas contracts that could pressure cash flows if jackpot driven earnings stayed unpredictable.
What The Results Changed For Brightstar Lottery
Brightstar Lottery’s Q2 2026 numbers gave the bullish case some backing on profitability. Total revenue moved from US$631 million in Q2 2025 to US$584 million in Q2 2026, yet net income shifted from a US$96 million loss to a US$33 million profit and net margin went from 15.2% negative to 5.7% positive. The evidence cut both ways, supporting margin optimism while questioning top line resilience.
The episode turned on one assumption: that contract wins and digital momentum would keep revenue firm while margins improved. When you assess another lottery operator, watch whether net income and margin trends improve without relying on flat or falling revenue, and check whether management commentary on contract economics lines up with those reported figures.
What You Would Be Paying For In Brightstar Lottery Today
Brightstar Lottery now trades at US$9.48 after a 39.8% loss over the past year. The selected Narrative places its Fair Value above that level, arguing the market gives limited credit to the contract base, digital progress and potential free cash flow.
Your decision today rests on one core assumption. A buyer has to judge that Brightstar Lottery can turn iLottery growth, the Italy MyLotteries rollout and OPtiMa 3.3 into durable digital revenue, stable margins and sizeable free cash generation.
"The main thing that has to go right is that Brightstar Lottery converts rapidly growing iLottery wagers and the Italy MyLotteries app rollout into sustained digital revenue and margin gains, while OPtiMa 3.3 delivers the targeted US$100 million in annual savings. The numbers imply the share price embeds limited credit for more than US$400 million of potential annual free cash flow and current digital growth, so the stock trades as if Brightstar Lottery’s long-term contract base and cost programs are worth less than recent performance suggests."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Which Company Could Surprise You Next?
This company's disappointment is already part of the story. Your next idea could come from looking where the price and the possibilities still seem far apart. Here are three companies priced below our estimates.
- Company 1 - 37% below our estimate - advises on complex engineering failures, product safety crises and technical regulatory disputes.
- Company 2 - 33% below our estimate - targets large AI compute build-outs that depend on its accelerated hardware and tools.
- Company 3 - 24% below our estimate - embeds AI copilots across productivity apps, enterprise cloud platforms and developer environments.
Those are three of them. See every one of the 24 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com