
3 Global Growth Companies With High Insider Ownership And 107% Earnings Growth
In recent weeks, global markets have experienced volatility driven by concerns over AI investments and rising oil prices, with small-cap and value stocks outperforming their large-cap counterparts. Amidst this backdrop, investors are increasingly focusing on growth companies with high insider ownership as these firms often exhibit strong alignment between management and shareholder interests. Identifying such companies can be crucial in navigating current market conditions while seeking robust earnings growth potential.
Top 10 Growth Companies With High Insider Ownership Globally
| Name | Insider Ownership | Earnings Growth |
| Pharma Mar (BME:PHM) | 12.1% | 39.9% |
| Meitu (SEHK:1357) | 23.1% | 26.5% |
| Meiko Electronics (TSE:6787) | 19.2% | 34% |
| KebNi (OM:KEBNI B) | 13.1% | 110.7% |
| JHT DesignLtd (SHSE:603061) | 23.1% | 45.3% |
| Guangdong Shenling Environmental Systems (SZSE:301018) | 36.7% | 65.4% |
| Gpixel Changchun Microelectronics (SEHK:3277) | 18.2% | 32% |
| Gold Road International (OB:GOLDR) | 36.7% | 89.8% |
| Gold Circuit Electronics (TWSE:2368) | 29.9% | 46.1% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
We'll examine a selection from our screener results.
Appotronics (SHSE:688007)
Simply Wall St Growth Rating: ★★★★☆☆
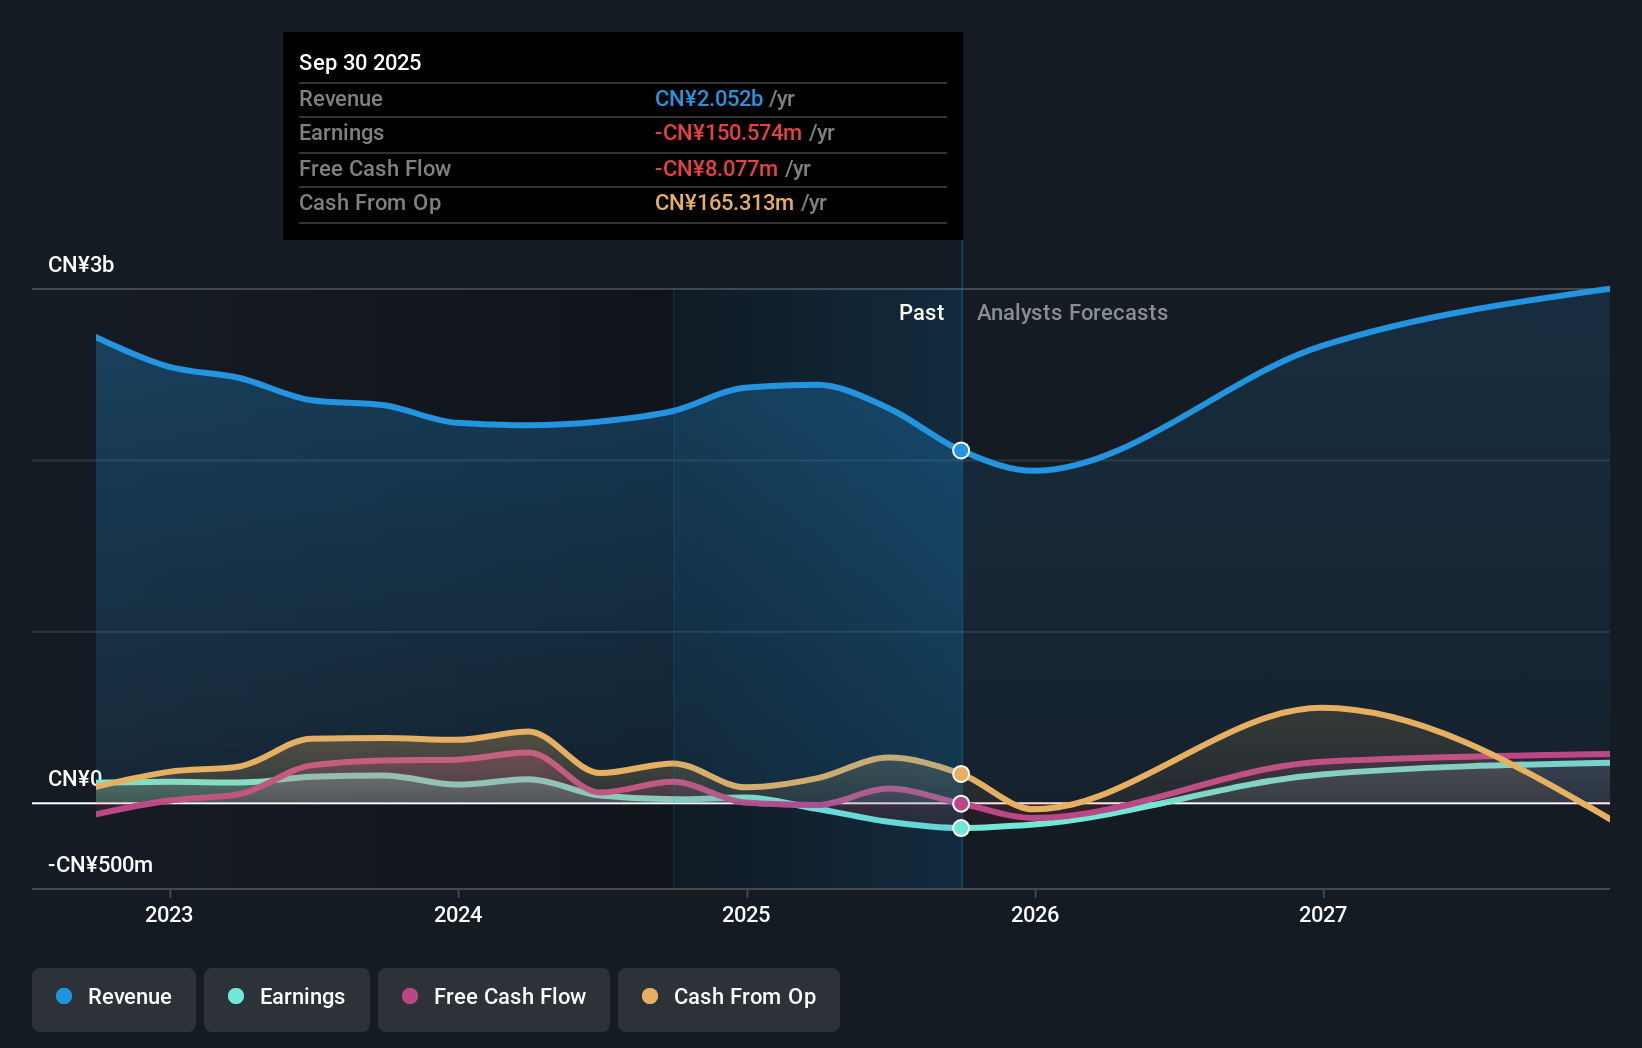
Overview: Appotronics Corporation Limited operates in the laser technology industry in China with a market cap of CN¥5.23 billion.
Operations: The company generates revenue from its operations in the laser technology sector within China.
Insider Ownership: 22.9%
Earnings Growth Forecast: 107.1% p.a.
Appotronics is forecast to achieve significant earnings growth at 107.05% annually and expects to become profitable in three years, surpassing average market growth. Despite trading at 56.1% below its estimated fair value, recent earnings showed a decline with sales at CNY 445.04 million compared to CNY 958.09 million the previous year, and a net loss of CNY 92.35 million down from CNY 130.94 million, indicating challenges amidst potential for growth.
- Click here and access our complete growth analysis report to understand the dynamics of Appotronics.
- The analysis detailed in our Appotronics valuation report hints at an deflated share price compared to its estimated value.
Sunwoda ElectronicLtd (SZSE:300207)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Sunwoda Electronic Co., Ltd, with a market cap of CN¥34.44 billion, is involved in the research, development, and manufacturing of lithium-ion batteries both in China and internationally.
Operations: Sunwoda Electronic Co., Ltd's revenue primarily stems from its expertise in the research, development, and production of lithium-ion batteries for both domestic and international markets.
Insider Ownership: 28.7%
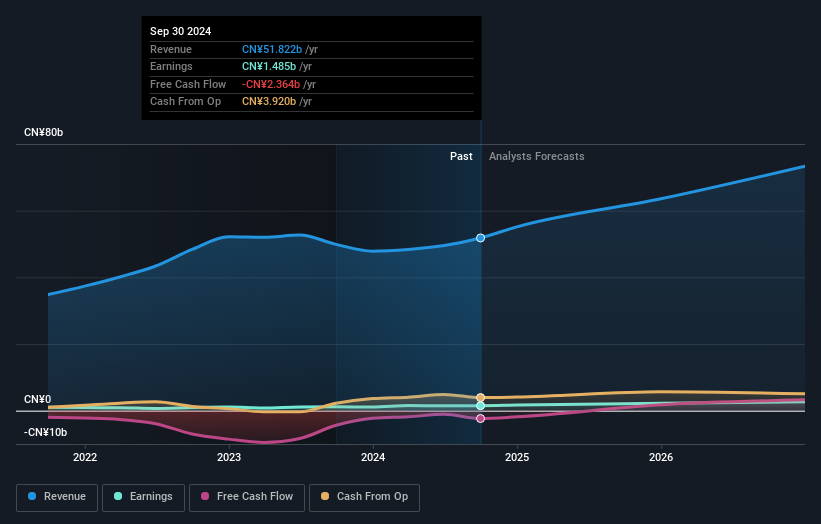
Earnings Growth Forecast: 49.5% p.a.
Sunwoda Electronic Ltd. is poised for substantial growth with earnings expected to rise 49.5% annually, outpacing the Chinese market's 26.7%. Despite a recent decline in net income to CNY 602.62 million from CNY 855.85 million, revenue surged to CNY 38.18 billion from CNY 26.99 billion year-over-year, highlighting robust sales momentum. However, profit margins have decreased to 1.1%, and the stock trades significantly below its estimated fair value, suggesting potential upside amid current challenges.
- Dive into the specifics of Sunwoda ElectronicLtd here with our thorough growth forecast report.
- Our expertly prepared valuation report Sunwoda ElectronicLtd implies its share price may be lower than expected.
Semitronix (SZSE:301095)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Semitronix Corporation offers characterization and yield improvement solutions for the semiconductor industry both in China and internationally, with a market cap of CN¥11.99 billion.
Operations: Semitronix Corporation generates revenue through its provision of solutions aimed at enhancing characterization and yield for the semiconductor sector across domestic and international markets.
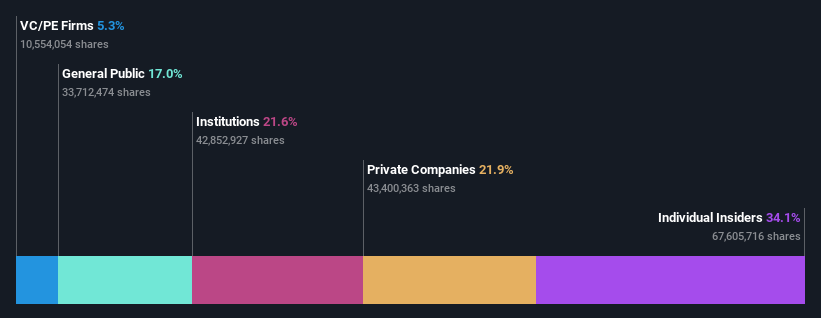
Insider Ownership: 34.1%
Earnings Growth Forecast: 39.4% p.a.
Semitronix has demonstrated impressive growth, with recent half-year sales increasing to CNY 340.51 million from CNY 245.49 million year-on-year, and net income rising to CNY 34.78 million from CNY 15.68 million. Earnings are projected to grow significantly at 39.4% annually, surpassing the Chinese market's average of 26.7%. Revenue is also forecasted to expand by a robust 24.9% per year, although return on equity is expected to remain relatively low at 7.8%.
- Take a closer look at Semitronix's potential here in our earnings growth report.
- Our valuation report here indicates Semitronix may be overvalued.
Turning Ideas Into Actions
- Unlock our comprehensive list of 727 Fast Growing Global Companies With High Insider Ownership by clicking here.
- Ready For A Different Approach? This technology could replace computers: discover the 25 stocks are working to make quantum computing a reality.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com