
What Investors Got Wrong About Helloworld Travel Before The Drop
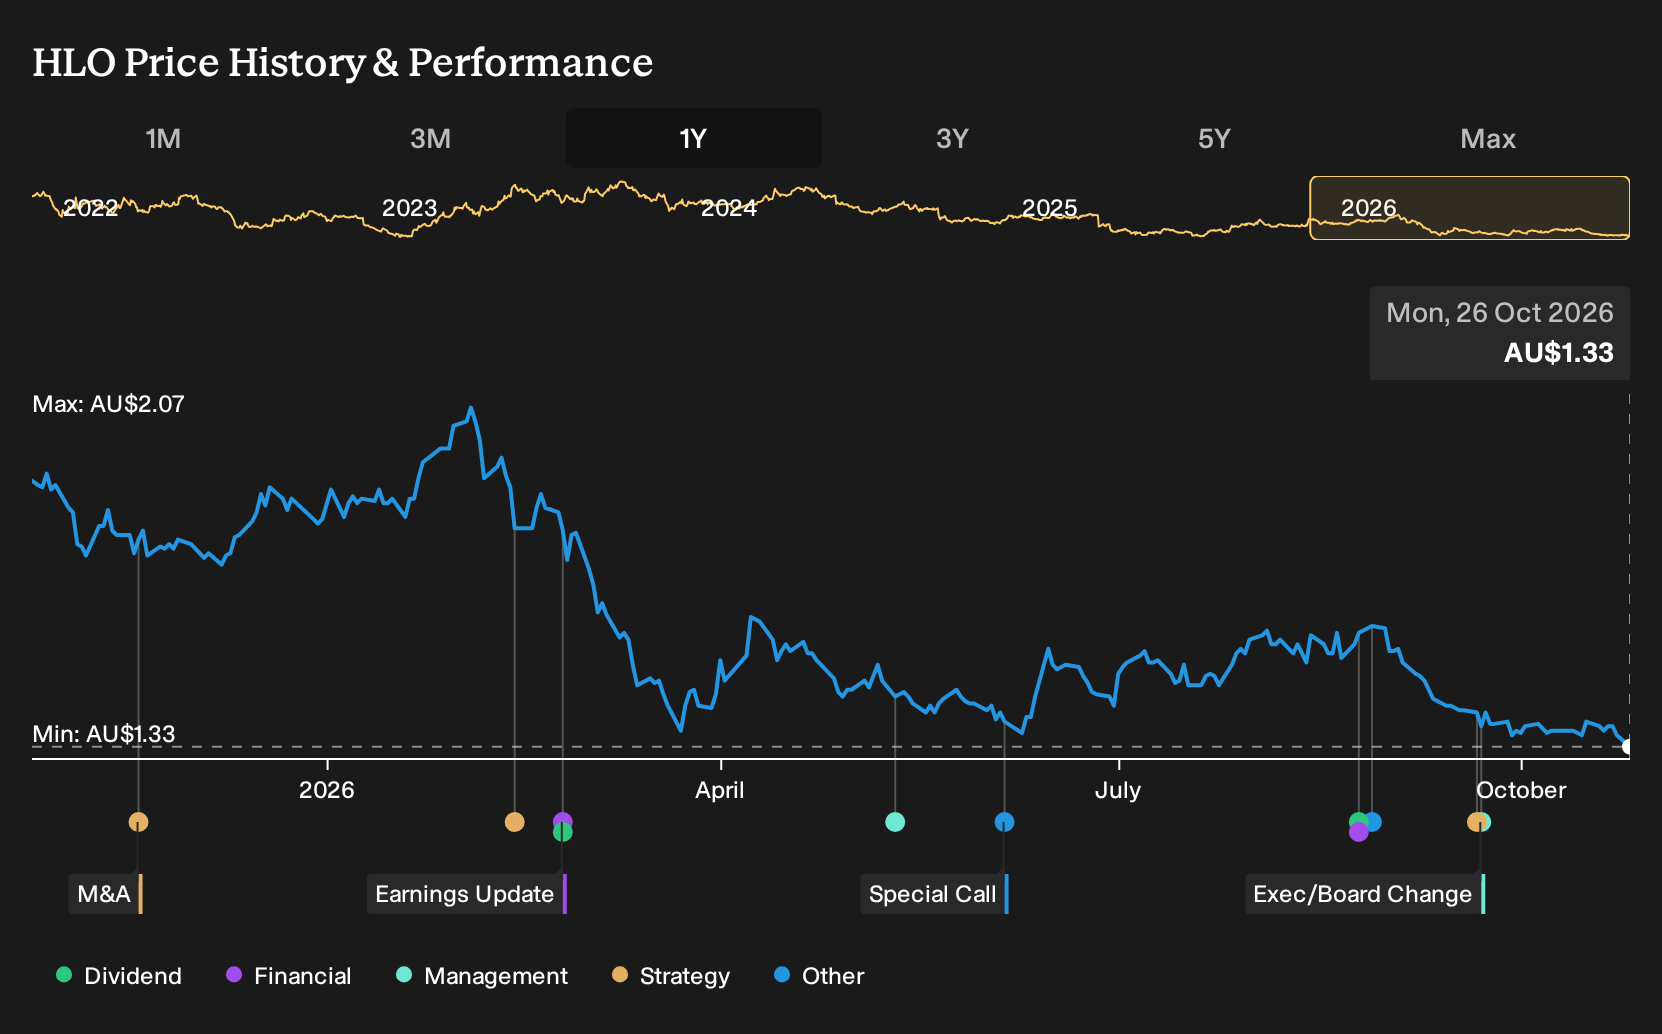
If you only glanced at Helloworld Travel’s headlines, stable trading and upbeat FY27 guidance might suggest a fairly calm ride. For Helloworld Travel shareholders, the loss over the past year was 25.9%, including dividends. That gap between business signals and portfolio outcome is hard to ignore. If you were weighing up a position a year ago, what clues were already on the table about digital pressure, franchise dependence and future profitability?
Helloworld Travel has already moved. See which of 2 high quality undervalued stocks still trade below our estimates.
The Two Futures Helloworld Travel Investors Had To Price In
The shares cost A$1.92 at the start of the period, and anyone looking at Helloworld Travel then had to decide which story felt more plausible.
On the optimistic side, the bullish view saw a Fair Value of A$2.30, a price implied by an outlook of 4.5% annual revenue growth and profit margins easing only to 15.9%, supported by heavier investment in proprietary booking technology.
The cautious camp put Fair Value at A$1.79, based on slower 2.8% growth, margins slipping to 14.9%, and the risk that digital competitors would steadily chip away at franchise driven volumes.
What The Results Changed For The Helloworld Travel Debate
Helloworld Travel’s FY27 guidance, including the Crown Currency Exchange acquisition and TTV outlook of about A$4.8b with A$78m to A$84m in Underlying EBITDA, leaned toward the optimistic scenario on activity and scale. The later H2 2026 figures told a different story. Revenue reached A$96.621m yet profit swung to a loss of A$29.6m and net margin fell to -30.6%, so profitability in the bullish case stayed unproven. The evidence cut both ways.
The hinge assumption here was not demand; it was earnings quality. When you test a growth story at another company, track whether higher sales or guidance show up in Net Income and net margin, rather than assuming volume alone supports the original thesis.
What Helloworld Travel’s Lower Price Now Asks You To Believe
Helloworld Travel now trades at A$1.32. The selected Narrative’s Fair Value sits above that level, based on a view that current expectations look modest if execution improves.
The pitch rests on booking growth, tech platforms and acquisitions eventually feeding through to steadier earnings and cash flow than the recent flat profit suggests.
"The numbers around earnings, dividends and guided EBITDA and TTV indicate that Helloworld Travel’s current share price reflects modest growth expectations that appear conservative if management implements its plans effectively."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
One Step Beyond Helloworld Travel
Helloworld Travel relies on one thing above all else: trip volume.
Your booking keeps revenue flowing, yet it also starts a quiet clock.
Customers often pay well before the flight, hotel stay or tour begins.
Another online travel business leans heavily on that waiting-period cash, holding payments until check in.
Its balance sheet shows a liability, but the money sits on its platform, and knowing who steers that float, and when it unwinds, can reshape how you read the whole sector.
One Narrative has already put a figure on it. → Uncover the company trading 52% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com