
Abbott Laboratories (ABT) Tests Its Valuation On Cancer Data And Nutrition Spin Off
Abbott Laboratories (ABT) has dropped a cluster of market moving headlines in a matter of days, from fresh colorectal cancer test data to a planned Nutrition spin off, new leadership, and mixed quarterly earnings.
Those headlines have landed against a tricky backdrop for Abbott Laboratories, where the share price is down 16.5% year to date despite a 3 year total shareholder return of 18.77% and a 1 year total shareholder return that has declined 16.44%. Recent sessions show a modest lift, with a 1 day share price return of 1.16% and a 30 day share price return of 2.38%. However, the 90 day share price return has fallen 3.33% as investors weigh stronger sales, lower net income and the Nutrition spin off story against the potential of assets like the Oncodetect MRD platform.
Scan how Abbott Laboratories compares with a curated group of resilient healthcare stocks with solid finances in the list of solid balance sheet and fundamentals (24 results).
Abbott Laboratories now trades well below recent highs and sits between upbeat diagnostics data and a pending Nutrition spin off. Is this the moment to lean in, or does patience on price still make more sense?
Most Popular Narrative: 14% Undervalued
On the most followed narrative, Abbott Laboratories screens as undervalued, with a fair value of $120.26 against a last close of $103.70, which puts the spotlight on whether the medical technology pipeline can justify that gap.
The main thing that has to go right is that Abbott Laboratories continues to convert its medical technology pipeline in areas like continuous glucose monitoring, electrophysiology and cancer diagnostics into sustained sales growth and margin expansion, while managing Nutrition legal and regulatory risks.
The current valuation implies the market is treating Abbott Laboratories as a steady healthcare compounder, rather than fully pricing in the earnings contribution suggested by raised 2026 EPS guidance, margin progress and growth investments in Libre, electrophysiology and Cancer Diagnostics, which this narrative views as too low.
See why 191 investors see Abbott Laboratories as 14% undervalued.
Result: Fair Value of $120.26 (UNDERVALUED)
Still, the narrative can crack if Nutrition legal costs re accelerate, or if the higher P/E multiple analysts assume for Abbott Laboratories simply fails to hold.
Find out about the key risks to this Abbott Laboratories narrative.
Another View: What Abbott Laboratories' P/E Ratio Is Telling You
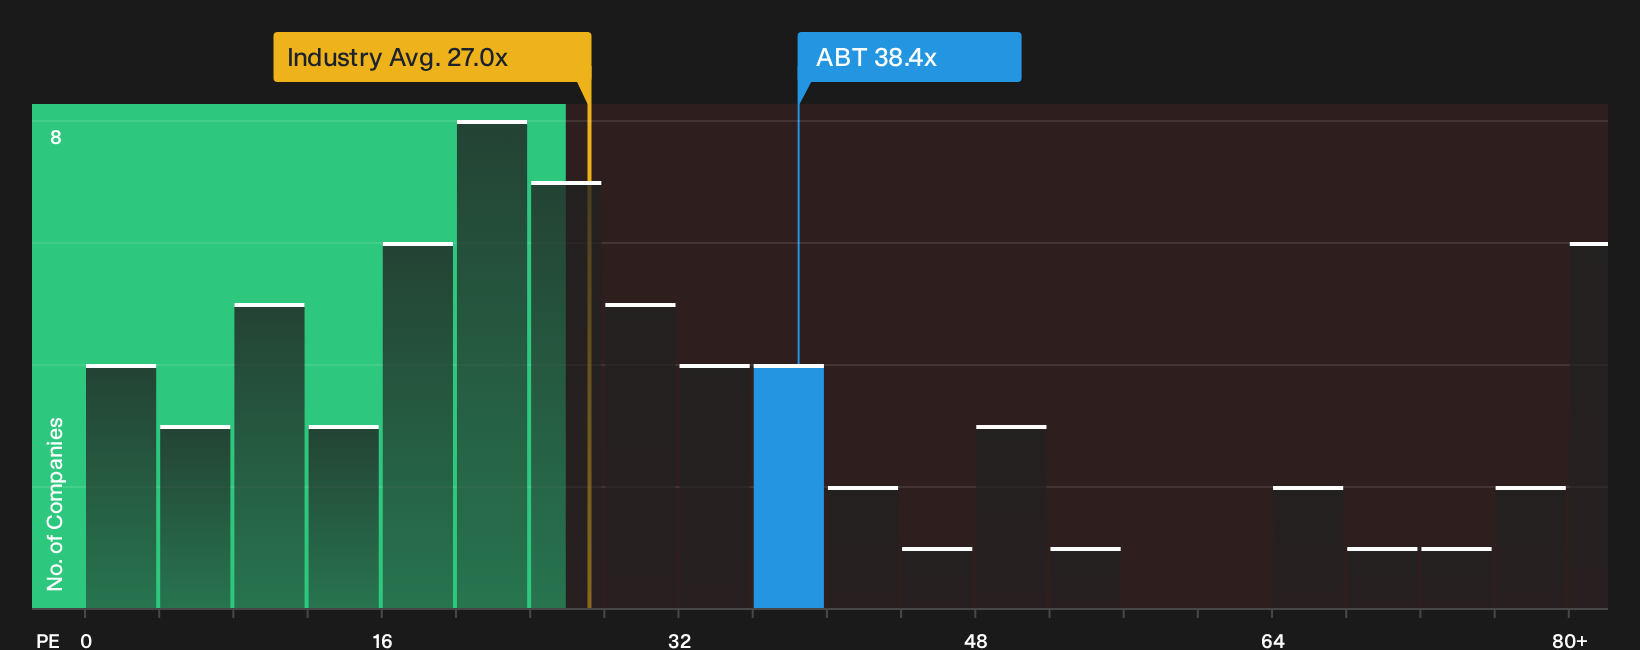
The fair value work suggests Abbott Laboratories is undervalued, yet the P/E story is less relaxed. The stock trades on 38.4x earnings, compared with a fair ratio of 37.3x, the US Medical Equipment industry at 27x and peers at 35x. That leaves you paying a richer multiple for a business already priced above where the market could move toward. Is that premium worth it if sentiment on healthcare cools?
See what the numbers say about this price in more detail in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Abbott Laboratories can feel messy, so move fast, test the numbers against your own framework, and then weigh the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Abbott Laboratories?
If Abbott Laboratories is on your radar, broaden your watchlist now and pressure test your thesis against other high quality opportunities investors are already tracking closely.
- Target resilient balance sheets and disciplined capital allocation using the list of solid balance sheet and fundamentals (24 results).
- Hunt for quality at a discount by scanning the market for 28 high quality undervalued stocks.
- Prioritise defense and consistency by focusing on income opportunities across 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com